


Wellness Retreat Business Insurance UK 2026 | Specialist
Why does UK wellness retreat business insurance need specialist treatment in 2026?
Wellness retreats are one of the fastest-growing segments of the UK lifestyle economy. Yoga retreats in the Cotswolds. Detox retreats in Cornish manor houses. Silent meditation retreats in Welsh hill country. Burnout recovery weekends in converted barns. Plant-medicine adjacent retreats hosted within strictly legal frameworks. Corporate wellbeing residential programmes at country house venues. They all share something the typical commercial insurer doesn't fully understand: the operator isn't just running accommodation, isn't just running therapy, isn't just running catering — they're combining all three (and often more) into a single packaged experience that the law treats as something specific and consequential.
Under the Package Travel and Linked Travel Arrangements Regulations 2018 (PTR 2018), a wellness retreat operator who combines two or more travel services — accommodation plus any "other tourist service" — is operating as a tour operator. That single classification cascades into criminal liability for non-compliance, mandatory financial insolvency protection for client money, statutory pre-contractual information duties, strict liability for the performance of third-party suppliers, and an entirely different insurance programme than the wellness retreat operator's "yoga insurance" policy contemplates. The retreat industry is full of operators who don't realise this — and full of insurance policies that don't respond to it.
Layer onto that the Regulatory Reform (Fire Safety) Order 2005 (most retreats host paying guests in residential accommodation, triggering Responsible Person duties); the Food Information Regulations as amended by Natasha's Law (mandatory allergen labelling on prepacked food) and the new Benedict's Law (which will extend statutory allergen protections from September 2026 — although primarily aimed at schools, it indicates the regulatory trajectory); duty of care obligations for participants with undisclosed mental health conditions; and the contractual liability flowing from third-party practitioners delivering yoga, breathwork, sound healing, cold plunge, ice baths, or guided fasting. The result is a risk profile that mainstream commercial cover treats as either a guest house or a fitness studio — and gets wrong in both directions.
This guide is the definitive 2026 UK wellness retreat business insurance article — built around the regulatory framework, the genuine claim drivers, the cover architecture that responds, and the operational documentation that makes both compliance and claim defence possible. It sits in our wellness and therapy cluster alongside guides on aesthetics business insurance, wellness retreat insurance, cryotherapy business insurance, cold plunge therapy insurance, and the broader alternative therapies insurance product page. For retreat operators with built-in spa, IV, or aesthetics elements there's also direct relevance in our IV drip therapy, oxygen therapy, and aesthetics and beauty resources.
Key facts at a glance
- The Package Travel Regulations 2018 apply to most UK wellness retreats — combining accommodation with any "other tourist service" (yoga sessions, treatments, guided excursions, workshops) into a single price triggers tour operator classification, mandatory financial protection of client money, and criminal liability for non-compliance.
- Tour operator liability is strict liability for the performance of third-party suppliers — if a self-employed yoga teacher, breathwork facilitator, sound healer, or chef causes injury or illness at a retreat, the operator is liable to the guest under PTR 2018 regardless of whether the operator employed or contracted them.
- Most UK wellness retreats trigger the Regulatory Reform (Fire Safety) Order 2005 — paying guest accommodation creates a "Responsible Person" with mandatory documented fire risk assessment, fire detection requirements, and personal liability for non-compliance. Updates from October 2023 made recording the FRA mandatory regardless of staff numbers.
- Natasha's Law (October 2021) and Benedict's Law (statutory guidance September 2026) have transformed food allergen liability. Wellness retreats serving plant-based, low-FODMAP, or detox menus prepared on-site to specific dietary requirements face acute allergen exposure if labelling, preparation, and information disclosure is inadequate.
- Professional Indemnity is now functionally essential for retreat operators — not because the operator delivers therapy themselves (although often they do), but because of vicarious responsibility for practitioner advice, dietary recommendations, programme suitability for participants, and warranty-style claims about retreat outcomes.
- UK wellness retreat insurance premiums typically run £950–£3,800 for small operators and £4,500–£18,000+ for mid-sized residential retreats with tour operator scope, multi-practitioner programming, and 12+ guest capacity — pricing depends on PTR exposure, accommodation type, food handling scope, and claims history.
- The most common cover gap is package travel scope — operators buy "yoga teacher insurance" or "small B&B insurance" without specific tour operator liability declared, leaving the most consequential exposure category uninsured under the Insurance Act 2015's fair presentation requirement.
1. What are the 8 biggest wellness retreat risks: summary table
The risks below are ranked by combined frequency, severity, and regulatory consequence under the 2026 framework. Some — slips and trips, food allergen issues, practitioner liability — are everyday operational realities. Others — package travel insolvency claims, fire enforcement prosecution, mental health crisis liability — are infrequent but business-ending when they occur. The intelligent retreat operator manages all eight simultaneously rather than addressing them in priority order.
| Risk | Frequency | Severity | Primary Cover |
|---|---|---|---|
| Tour operator liability (PTR 2018) | Occasional but rising | High (£15k–£200k+) | Tour Operator Liability / Package Travel cover |
| Practitioner-led therapy claims (PI) | Common — rising under wellness boom | Medium-High (£8k–£75k typical) | Professional Indemnity |
| Slips, trips, and physical injury | Routine | Low-Medium (£500–£40k typical) | Public Liability |
| Food allergens and gastric illness | Occasional | Medium-High (£10k–£100k+ for severe anaphylaxis) | PL with food risk + Product Liability |
| Fire safety enforcement and injury | Rare but severe | Catastrophic (fines up to unlimited, custody) | Legal Expenses, D&O, PL |
| Mental health crisis at retreat | Rising | Medium-High (£15k–£80k+ if duty of care alleged) | PI with treatment risk, PL |
| Cold water, ice bath, breathwork injury | Rising | Medium-High (£12k–£90k) | PL with hazardous activity scope, PI |
| Insolvency protection / client money | Frequent regulatory exposure | Catastrophic (criminal offence, refund liability) | ABTOT/ABTA bonding, trust accounts, financial protection |
2. How do the Package Travel Regulations 2018 make every retreat operator a tour operator?
This is the single most misunderstood regulatory framework in the UK wellness retreat industry, and the single biggest source of accidental insurance non-disclosure. The Package Travel and Linked Travel Arrangements Regulations 2018 came into force on 1 July 2018, implementing the EU Package Travel Directive 2015. The regulations apply to all package travel contracts sold in the UK regardless of where the organiser is based, and they reach far beyond what most operators understand as "travel".
Under PTR 2018, a "package" is created when two or more different types of travel services are combined for the purpose of the same trip and sold at an inclusive price (or as a single contract). The travel services categories include: (1) the carriage of passengers; (2) accommodation (other than for residential purposes); (3) the rental of cars or other motor vehicles; and (4) any other tourist service not intrinsically part of the above. UK government guidance on PTR 2018 confirms that "other tourist services" include treatments, spa sessions, guided activities, workshops, and admission to events — so long as they constitute a significant proportion of the value of the package (commonly the 25% rule of thumb).
The standard wellness retreat structure — two or more nights' accommodation, plus yoga / meditation / breathwork / sound healing / cold plunge / treatments / guided activities, sold at a single price — is therefore a package under PTR 2018. The operator is the "organiser" with full tour operator responsibilities, regardless of whether they describe themselves as a "retreat host", "wellness facilitator", "yoga teacher", or anything else.
What tour operator classification actually means
Once a wellness retreat is classified as a package, four substantial regulatory consequences follow. First, statutory pre-contractual information duties — the operator must provide specific information in writing before the contract is concluded, including the package price, payment arrangements, traveller cancellation rights, complaint procedures, and the entity in charge of insolvency protection. Second, financial insolvency protection — the operator must protect client money paid in advance through bonding (ABTOT, ABTA), trust account arrangements, or insurance, so that if the operator becomes insolvent, travellers are refunded and (where applicable) repatriated. Third, strict liability for the performance of all travel services in the package — including services performed by self-employed third parties such as freelance yoga teachers, contracted chefs, or external practitioners. Fourth, criminal offences for non-compliance — failure to provide pre-contractual information, failure to put insolvency protection in place, and failure to provide the prescribed information at contract conclusion are all criminal offences punishable by fines and (in serious cases) imprisonment.
What about non-residential day retreats?
Day retreats without overnight accommodation typically don't trigger PTR 2018 because there's no accommodation element to combine with the "other tourist service". A standalone day workshop, yoga retreat day, or guided wellness experience without overnight stay sits outside the package travel framework. But the moment overnight accommodation is added — even one night — and combined with any structured activity element sold at a single price, PTR 2018 applies. Operators running mixed portfolios (some day events, some residential) need separate analysis for each event type, and insurance scope to match.
What about retreats hosted at third-party venues?
Many UK retreat operators rent a country house, manor venue, or yoga shala from a third party rather than owning the venue. PTR 2018 doesn't care who owns the venue — it cares who sells the package to the guest. If the operator is selling the combined accommodation + activity package, the operator is the organiser and bears tour operator responsibilities. The venue owner is a supplier, not the organiser, unless the venue itself is selling the package directly.
What about not-for-profit retreats?
UK government guidance is clear: not-for-profit packages are in scope of PTR 2018 unless offered only occasionally and only to a limited group of travellers. Charity-run retreats, faith-organisation retreats, and corporate wellness packages offered to staff all fall within scope where they are offered with any regularity. The exemption for "occasional" not-for-profit packages is narrow and shouldn't be relied on without legal advice.
3. Risk 1: Practitioner-led therapy claims and the PI exposure
Practitioner-Led Therapy Claims — The Dominant PI Exposure
The fundamental challenge of wellness retreat work is that participants arrive in vulnerable states — burned out, in life transition, recovering from illness, or experiencing relationship breakdown — and engage in physical and emotional practices that can have material adverse outcomes when delivered without appropriate care. The PI claim pattern: a guest attends a retreat, undertakes a practice or treatment, experiences harm (physical or psychological), and brings a negligence claim alleging the operator's advice, programme design, practitioner selection, or screening was inadequate. PI claims have grown materially in the UK wellness sector since 2023 and continue to accelerate.
Specific claim drivers include: unsuitable programme design for the participant's presenting condition (e.g. intense breathwork for someone with undisclosed cardiac arrhythmia); negligent advice on dietary protocols (extended fasting recommendations that interact with medication, juice cleanses for diabetic guests); inadequate screening of participants for contraindications; practitioner injury claims (yoga adjustment causing rotator cuff injury, sound healing causing tinnitus); inappropriate trauma processing facilitation outside the practitioner's competence; warranty-style claims about retreat outcomes that didn't materialise.
Health declaration form completed before booking confirmation; documented contraindication screening for high-intensity practices (breathwork, cold plunge, fasting); practitioner qualification verification and ongoing competency review; written programme descriptions with clear scope statements; documented informed consent for hazardous activities; signposting for participants whose declared conditions exceed retreat competency; insurance-backed warranties limited to specific claims (e.g. "you will receive 12 hours of guided meditation" rather than "you will leave transformed").
Professional Indemnity with retreat-specific scope is the primary response. Generic therapy PI typically responds to the practitioner's own work but may not contemplate the retreat operator's vicarious responsibility for third-party practitioner errors, programme design negligence, or screening failures. Specialist retreat PI should explicitly cover: programme design and practitioner selection decisions, advice given to participants outside individual treatment, warranty disputes, and treatment-by-third-party vicarious exposure. Limits £500k–£2m depending on retreat scale. Claim values £8k–£75k typical; severe psychological harm or significant physical injury claims £50k–£200k+.
4. Risk 2: Slips, trips, and physical injury during retreat activities
Slips, Trips, and Physical Injury — The Routine PL Claim
The numerically dominant claim type for UK wellness retreat operators is third-party bodily injury during retreat activities or movement around the venue. The typical scenarios: a guest slips on a wet bathroom floor or yoga deck; trips on uneven outdoor terrain during a guided walk; falls from a meditation cushion stack or yoga prop; sustains rotator cuff injury during a led yoga sequence; sustains back strain from inadequate warm-up or unsuitable posture instruction; sustains hypothermia or cold shock from inadequate cold plunge supervision. Claim values typically £500–£40,000; complex orthopaedic injuries with extended rehabilitation can reach £80,000+.
Documented pre-retreat venue inspection per session (slip hazards, lighting, trip hazards, outdoor terrain); appropriate signage for wet/changing areas; first aid trained staff with documented response protocols; written safety briefings for hazardous activities (cold plunge, breathwork, outdoor walks); participant-appropriate adjustments and modifications offered explicitly; documented practitioner training in injury-conscious instruction; risk assessment per activity type with documented controls.
Public Liability standard response. Limits typically £5m for small retreats; £10m for residential retreats and panel/corporate work. The defence depends on documented venue inspection, activity risk assessment, participant briefing, and practitioner competency. Generic guest house PL covers building risk but may not contemplate guided activity scope; generic yoga teacher PL covers instruction but may not contemplate venue or accommodation scope. Specialist retreat PL bridges both with explicit scope for venue, activity, and integrated programme.
5. Risk 3: Fire safety in retreat accommodation under the Fire Safety Order
Fire Safety in Retreat Accommodation — The Responsible Person Trap
Any UK wellness retreat that hosts paying guests in overnight accommodation triggers the Regulatory Reform (Fire Safety) Order 2005. The retreat operator (or whoever has control of the premises during the retreat) becomes the "Responsible Person" with personal duties to: conduct a suitable and sufficient fire risk assessment; provide adequate fire safety measures including escape routes and fire alarm systems; maintain fire safety measures in good order; provide fire safety information to relevant persons. Following amendments under Section 156 of the Building Safety Act 2022 and updates from 1 October 2023, recording the fire risk assessment in writing became mandatory for paying guest accommodation regardless of staff numbers — previously only required where five or more staff were employed.
The Home Office guidance "A Guide to Making Your Small Paying-Guest-Accommodation Safe from Fire" (revised 2023) applies to most small UK retreats (accommodation for up to 10 people, no higher than first floor). Larger or more complex retreats (more than two storeys or accommodation for more than 10) fall under the more rigorous Fire Safety Risk Assessment: Sleeping Accommodation guidance. The Fire and Rescue Service is the enforcing authority. Non-compliance penalties range from improvement notices and prohibition notices through to unlimited fines and imprisonment for serious offences. The pattern in HSE-equivalent fire prosecutions has been consistently severe in 2024–2025 for accommodation businesses where injury or death occurred.
Documented fire risk assessment per venue (annual review; immediately if material change to occupancy or layout); interlinked fire alarm system to BS 5839 Part 6 LD1 standard minimum for small premises; appropriate fire detection in all sleeping rooms, corridors, and escape routes; clear escape routes with emergency lighting where indicated; documented evacuation plan with fire action notices in guest rooms; competent fire risk assessor engaged where premises are larger or complex; six-monthly servicing of fire detection by competent contractor; assessment of guest mobility/sensory needs at booking and accommodation matching accordingly; documented staff training in fire response.
Legal Expenses with fire safety enforcement scope provides defence cost cover for FRS prosecutions (the fines themselves are uninsurable under UK public policy). Public Liability responds to guest injury claims arising from fire incidents where Responsible Person duties were inadequate. Property cover responds to building and contents damage. Where the retreat operator is also the venue owner, comprehensive Property + BI cover is essential. Where the retreat operator is using a third-party venue, contractual indemnity provisions need careful review — the operator may still bear Responsible Person duties as the person with control during the retreat. Defence costs for contested fire safety prosecution routinely £40,000–£200,000.
6. Risk 4: Food allergens, Natasha's Law, and the catering exposure
Food Allergens and Catering — The Rising 2026 Exposure
Wellness retreats sit at a particularly acute intersection of food allergen risk. The clientele is health-conscious and often carries food sensitivities — approximately 6% of UK adults have a clinically confirmed food allergy according to Food Standards Agency data, and the cohort attracted to wellness retreats over-indexes substantially against the general population. The menu offering is typically plant-based, gluten-free, or specifically designed for elimination diets and detox protocols — increasing complexity of ingredient handling. The catering is typically on-site preparation by retreat staff or contracted chefs rather than industrial supply. Under Natasha's Law (the Food Information (Amendment) (England) Regulations 2019, in force October 2021), any prepacked-for-direct-sale food must carry full ingredient labelling with the 14 major allergens emphasised — directly applicable to grab-and-go elements at retreats (packaged snacks, prepared salads available for guests, packaged meals for take-away).
The newer development is Benedict's Law, announced by the UK Government in March 2026 following the inquest into the 2021 death of 5-year-old Benedict Blythe from a milk-induced anaphylactic reaction. Statutory guidance is being consulted on through 2026 with implementation in September 2026. While primarily directed at schools (allergy policies, individual healthcare plans, mandatory adrenaline auto-injectors), the legislation signals a clear regulatory direction of travel — heightened scrutiny of allergen handling, formalised allergy management in settings catering to vulnerable individuals, and increased liability exposure for catering operations that fail to meet evolving standards. Wellness retreats catering to allergy-sensitive guests should expect equivalent best practice standards to apply commercially and contractually within 12–24 months.
The specific claim profile: a guest with declared food allergy attends a retreat, consumes a meal containing the allergen due to inadequate ingredient communication, suffers an allergic reaction (ranging from discomfort to anaphylaxis), and brings a claim. Claim values: £10,000–£40,000 for moderate reactions with hospital treatment; £75,000–£200,000+ for anaphylaxis with intensive care or lasting harm; potentially fatal cases involve unlimited liability and corporate manslaughter exposure.
Pre-arrival health and dietary declaration form with structured allergen disclosure capture; documented food preparation protocols including cross-contamination controls; allergen training for all catering staff (Level 2 Food Safety minimum, Level 3 for the catering lead); ingredient lists maintained for every meal with allergens emphasised in line with Natasha's Law requirements; verbal allergen confirmation at point of service for each guest; written communication of allergens for grab-and-go items per PPDS requirements; immediate access to adrenaline auto-injectors on site with staff trained in emergency response; food incident reporting protocol; documented response to any allergen near-miss; review of catering arrangements where contracted to third party with contractual indemnity in place.
Public Liability with food risk scope responds to guest illness or injury arising from food served at the retreat. Product Liability responds where prepacked food provided to guests caused harm. Legal Expenses responds to food hygiene prosecution by local authority Environmental Health. The defence depends entirely on documented allergen handling — without dietary declaration records, ingredient lists, and verbal confirmation evidence, claims are very difficult to defend. Generic guest house PL often sub-limits or excludes food risk specifically; specialist retreat cover includes it explicitly.
7. Risk 5: Mental health, vulnerability, and undisclosed conditions
Mental Health and Vulnerability — The Underestimated Exposure
Wellness retreats actively attract participants in vulnerable states — burnout recovery, relationship breakdown, bereavement, post-illness convalescence, life transition. The retreat experience itself can be intense: silent meditation, breathwork, plant-based fasting, sleep restriction, group emotional processing, and exposure-based practices (cold plunge, ice baths, fire ceremonies). Participants may arrive with undisclosed mental health conditions including history of psychosis, eating disorders, severe depression, suicidal ideation, or active addiction. The intersection of vulnerable population + intense experience + frequently inadequate clinical screening creates a meaningful and rising claim category.
Specific claim drivers include: psychiatric decompensation during or after retreat (psychotic episode triggered by breathwork or fasting in genetically predisposed participant); worsening of eating disorder pathology during dietary restriction programmes; trauma response provoked by emotional processing sessions delivered outside practitioner competence; suicidal crisis at retreat venue with inadequate safeguarding response; medication non-compliance during retreat (some retreats encourage participants to "pause" medication without medical input). Claim values typically £15,000–£80,000; severe outcomes including permanent psychiatric injury or death involve unlimited liability and potentially Health and Safety at Work Act prosecution.
Comprehensive pre-arrival health declaration capturing mental health history, current medications, recent psychiatric admissions, current psychological treatment; explicit contraindication policy for high-intensity practices where mental health history indicates risk; documented decision-making on participant suitability with clear scope statements; on-site crisis management protocol with relationships to local NHS mental health services; staff training in mental health first aid (Mental Health First Aid England curriculum); explicit policy on medication continuation during retreat; clear referral pathways for participants who decompensate during the retreat; written boundary statements clarifying what the retreat does and does not provide (we do not provide therapy, we do not replace medical treatment, we are not a substitute for psychiatric care).
PI with retreat scope responds to negligence claims around participant screening, programme design, and crisis management. PL responds to physical injury arising from psychiatric decompensation at retreat venue. Generic therapy PI may not contemplate mental health crisis scope specifically; specialist retreat PI should explicitly cover screening decisions and crisis response. The single most important defensive evidence is the documented health declaration plus the contraindication decision record — without these, claims are very difficult to defend.
8. Wellness retreat insurance cover checker
Select your retreat type below to see the cover matched to your specific risk profile. For broader product context see our alternative therapies insurance product page, our aesthetics and beauty resource for retreats with treatment elements, and the professional indemnity insurance hub for PI considerations.
Wellness Retreat Insurance Cover Checker
Select your retreat type to see the recommended insurance programme matched to the 8 main wellness retreat risks
Sole-Led Day Retreat (No Overnight)
- ESSENTIAL Public Liability £2m–£5m with hazardous activity scope where breathwork, cold plunge, or fasting included
- ESSENTIAL Professional Indemnity £250k–£500k with practitioner advice and programme design scope
- ESSENTIAL Personal Accident — primary income protection for sole practitioner
- ESSENTIAL Equipment cover (mats, props, sound equipment, ice baths)
- RECOMMENDED Legal Expenses with regulatory and contract dispute scope
- RECOMMENDED Cyber insurance — participant booking and health data
- CONSIDER Employers' Liability immediately if any sub-contracted facilitator engaged for the day
- CONSIDER PTR exemption likely applies (no overnight accommodation) — confirm scope at proposal
Weekend Residential Retreat (Third-Party Venue)
- CRITICAL PTR 2018 applies — tour operator liability and financial protection essential
- LEGAL Employers' Liability £10m where any staff or sub-contracted facilitators engaged
- ESSENTIAL Public Liability £5m with tour operator liability scope, food risk, and hazardous activity scope
- ESSENTIAL Professional Indemnity £500k–£1m with retreat-specific scope (screening, programme design, third-party practitioner vicarious)
- ESSENTIAL Insolvency protection for client money — ABTOT bonding, trust account, or insurance-based
- ESSENTIAL Equipment cover
- ESSENTIAL Legal Expenses with PTR, fire safety, and food hygiene scope
- RECOMMENDED Cyber insurance for participant health and booking data
- RECOMMENDED Cancellation cover for material loss if retreat must be cancelled
Venue-Owning Residential Retreat
- CRITICAL Responsible Person duties under RR(FS)O 2005 — fire safety documentation essential
- CRITICAL PTR 2018 applies — full tour operator scope required
- LEGAL Employers' Liability £10m comprehensive scope
- ESSENTIAL Public Liability £5m–£10m with tour operator, food risk, and hazardous activity scope
- ESSENTIAL Professional Indemnity £1m with retreat-specific scope
- ESSENTIAL Insolvency protection for client money
- ESSENTIAL Property insurance — buildings, contents, fixtures, fittings, gardens and outbuildings
- ESSENTIAL Business Interruption — fire, flood, or major incident closing the venue
- ESSENTIAL Legal Expenses with fire safety, PTR, food hygiene scope
- ESSENTIAL Cyber insurance comprehensive scope
UK-Organised Overseas Retreat
- CRITICAL PTR 2018 applies regardless of overseas location — UK organiser bears full tour operator liability
- CRITICAL ABTOT or ABTA bonding strongly indicated for overseas package insolvency protection
- ESSENTIAL Tour Operator Liability cover with overseas territorial scope
- ESSENTIAL Worldwide PL £5m–£10m with strict liability for overseas supplier performance
- ESSENTIAL Professional Indemnity £1m with worldwide territorial scope
- ESSENTIAL Group travel insurance for participants (separate from operator's liability cover)
- ESSENTIAL Legal Expenses with PTR, contract, and overseas jurisdiction scope
- ESSENTIAL Repatriation cover
- ESSENTIAL Cyber insurance with cross-border data scope
Corporate Wellbeing Retreat Operator
- CRITICAL Corporate contracts typically specify minimum cover terms — review carefully
- CRITICAL PTR 2018 likely applies to packaged corporate retreats
- LEGAL Employers' Liability £10m comprehensive
- ESSENTIAL Public Liability £10m (typical corporate panel requirement)
- ESSENTIAL Professional Indemnity £1m–£2m with retreat-specific scope and warranty exposure
- ESSENTIAL Insolvency protection for client money where deposits exceed nominal
- ESSENTIAL Cyber comprehensive — corporate participant data sensitivity
- ESSENTIAL Legal Expenses comprehensive
- ESSENTIAL Confidentiality cover for sensitive corporate and participant data
- RECOMMENDED Directors and Officers (D&O) liability for corporate retreat operator at scale
Multi-Discipline Residential Operator
- CRITICAL Multi-discipline scope (yoga + breathwork + cold plunge + nutritional + treatments) requires specialist placement
- LEGAL Employers' Liability £10m comprehensive
- ESSENTIAL Public Liability £10m with full tour operator, food risk, and hazardous activity scope
- ESSENTIAL Professional Indemnity £1m–£2m with comprehensive retreat scope
- ESSENTIAL Insolvency protection comprehensive
- ESSENTIAL Property and Business Interruption
- ESSENTIAL Legal Expenses comprehensive with PTR, fire safety, food, employment scope
- ESSENTIAL Cyber insurance comprehensive scope
- ESSENTIAL Directors and Officers (D&O) liability
- ESSENTIAL Cancellation cover for material loss
9. Package Travel Regulations readiness self-check
The Package Travel Regulations 2018 are the single most consequential regulatory framework for UK wellness retreat operators. Tick each compliance discipline you have in place. The unchecked items are your priority gaps.
Package Travel Regulations 2018 Readiness Self-Check
Click each PTR compliance discipline you have in place. The more ticked, the lower your PTR downstream exposure.
-
You have confirmed PTR applicability for each retreat product — written analysis of whether each event combines two or more travel services into a package
-
Pre-contractual information is provided in writing before booking — package price breakdown, payment terms, cancellation rights, complaint procedures, insolvency protection details
-
Financial protection for client money is in place — ABTOT bonding, ABTA membership, trust account arrangement, or insurance-based financial protection
-
Contract terms reflect PTR requirements — implied terms regarding performance, traveller rights to terminate, force majeure handling, complaint and dispute resolution
-
You retain documented evidence of pre-contractual information delivery — booking confirmation system captures what was provided to each traveller and when
-
You understand strict liability for third-party supplier performance — sub-contracted yoga teachers, breathwork facilitators, sound healers, chefs, transport providers
-
Supplier contracts include indemnity provisions back to the operator — written contracts with third-party facilitators, chefs, venues confirming their own insurance and indemnifying the operator for their negligence
-
Insurance is specifically declared for tour operator scope — written broker confirmation that PTR 2018 tour operator liability is within cover scope
-
Complaint handling procedure is documented and complies with PTR timeframes — traveller complaint receipt, acknowledgement, investigation, response within statutory periods
-
Cancellation and termination policies reflect PTR traveller rights — significant change to package terms triggers free cancellation right; price increases beyond 8% trigger cancellation right
-
Marketing materials accurately describe the package — descriptions, photographs, included services, excluded items, accommodation type and quality match what is delivered
-
Where overseas retreats are organised, ATOL compliance is considered — if flights are included or are facilitated as part of the package, ATOL protection may apply in addition to PTR
10. Wellness retreat operation risk assessor
Two factors drive wellness retreat operational risk above all others: the complexity of the retreat format and the maturity of your compliance and documentation. Use the tool below for your specific risk profile.
Wellness Retreat Operation Risk Assessor
Select your retreat format and your compliance maturity to see your specific risk profile and indicative insurance package
11. Risk 6: Cold water immersion, ice bath, and breathwork injury
Cold Water, Ice Bath, and Breathwork — The Wim Hof-Era Exposure
Cold water immersion, ice baths, sauna-cold contrast, and intensive breathwork (Wim Hof Method, holotropic breathwork, conscious connected breathing, transformational breathwork) have moved from fringe to mainstream wellness retreat programming since 2022. The Wim Hof Method alone has trained over 20,000 UK instructors, and the average UK residential wellness retreat now includes some combination of these practices. They are not inherently dangerous when properly delivered but they sit closer to "exercise prescription" than "yoga class" on the risk spectrum, and the claim pattern reflects this. Specific injury types include: cold shock response triggering arrhythmia in undiagnosed cardiac participants; hypothermia from inadequate exposure timing or supervision; loss of consciousness from breath retention triggering injury during fall; pulmonary barotrauma from intensive breathwork techniques; psychological decompensation triggered by intensive breathwork in trauma-history participants; secondary drowning from cold water immersion without supervision.
The legal framework around these practices is evolving. There is currently no UK statutory regulation of cold water immersion or breathwork facilitator competency, but professional bodies (UK Cold Water Therapy Association, Breathwork Practitioners Association) have published guidance and minimum competency standards that are increasingly treated as the working insurance benchmark. The Health and Safety Executive treats organised cold water immersion as a regulated workplace activity under the Health and Safety at Work Act 1974 with documented risk assessment, competent supervision, and emergency response procedures required.
Specific contraindication screening before each cold or breathwork session (cardiac conditions, hypertension, pregnancy, epilepsy, recent surgery, medication interactions); competent facilitator with documented qualifications and ongoing competency; documented session protocols with maximum exposure times; supervision ratios appropriate to participant numbers; emergency response equipment immediately accessible (rescue equipment for cold immersion, oxygen for breathwork); informed consent obtained in writing including specific contraindication acknowledgement; first aid trained staff in attendance; documented incident reporting for any adverse event during these sessions.
Public Liability with explicit hazardous activity scope responds to participant injury claims. PI responds where facilitator competency or programme design negligence is alleged. Generic PL frequently excludes cold water immersion and breathwork specifically; specialist retreat cover should explicitly include them with documented operational protocols as the underwriting basis. Claim values £12,000–£90,000 for moderate injuries; severe outcomes (significant cardiac event, anoxic brain injury, lasting psychological harm) can reach £200,000+.
12. Risk 7: Insolvency protection and client money exposure
Insolvency Protection — The Criminal Offence Hidden in Every Retreat Deposit
Under Regulation 19 of the Package Travel and Linked Travel Arrangements Regulations 2018, every organiser of packages sold in the UK must provide effective security for the refund of all payments made by travellers and (where the package includes the carriage of passengers) for repatriation of travellers in the event of organiser insolvency. This applies whether the operator is a one-person business hosting a single residential retreat per year or a mid-sized retreat company running monthly events. Failure to provide insolvency protection is a criminal offence — not a civil non-compliance matter — punishable by fine and (for serious cases) imprisonment.
The protection must be effective and accessible: travellers must be able to access refunds reasonably quickly in the event of operator failure. Acceptable mechanisms include: ABTOT bonding (Association of Bonded Travel Organisers Trust); ABTA membership and bonding; participation in an approved trust account scheme where client money is held separately from operating funds until the retreat is delivered; insurance-based financial protection where a specialist insurer underwrites the refund obligation. The right mechanism depends on retreat scale, package values, and operator preference. Trust accounts are popular for smaller operators because the capital outlay is lower; bonding is preferred for higher-volume operators because the cost is more predictable. Insurance-based financial protection is widely available through specialist Lloyd's market schemes.
The compliance failure pattern is depressingly consistent: operator takes a £1,500 deposit per guest, six months before the retreat, deposits go into the operating account, get used for ongoing business expenses, retreat happens, guests are happy, no issues. Operator hasn't realised they were committing a criminal offence every time they took a deposit. The exposure crystallises in two scenarios: (1) the operator becomes insolvent and 30+ travellers have paid in advance with no protection — multiple criminal prosecutions plus potentially unlimited civil liability for refunds; (2) a competitor or disgruntled traveller reports the operator to Trading Standards and the operator faces prosecution for non-compliance even though no insolvency has occurred.
Engage ABTOT or ABTA at retreat business setup; alternatively establish a compliant trust account arrangement with appropriate banking partner; alternatively arrange insurance-based financial protection through a specialist broker; ensure pre-contractual information to travellers identifies the insolvency protection in place and how to access it; review protection adequacy annually as retreat values and volumes scale; retain documented evidence of protection at every annual review point.
Insurance-based financial protection through specialist Lloyd's market schemes provides the underwritten refund obligation. Legal Expenses provides defence cost cover for any PTR prosecution by Trading Standards. Standard commercial insurance does not include PTR financial protection — it must be arranged specifically. Costs typically run 1–3% of forward-booked package revenue depending on scheme.
13. Risk 8: Insurance non-disclosure under the Insurance Act 2015
Insurance Non-Disclosure — The Most Preventable Catastrophe
The single most common reason UK insurance claims are reduced or declined isn't underwriting fraud or bad luck — it's non-disclosure at the proposal or renewal stage. Wellness retreat operators routinely buy yoga teacher policies, small B&B policies, or generic commercial cover without specifically declaring tour operator activity, packaged retreat sales, cold water immersion or breathwork programming, food handling for participants with allergies, or third-party practitioner engagement. The Insurance Act 2015 requires businesses to make a "fair presentation of the risk" — proactively disclosing every material fact the insurer would want to know. Failure to do so allows the insurer to: avoid the policy (treating it as never having existed); reduce the claim proportionally; impose terms that would have applied with proper disclosure.
Annual review of declared activities against actual operations; written confirmation from broker that all current retreat formats are within scope; specific declaration of each activity at proposal (tour operator scope, residential vs day, overseas vs UK, cold/breathwork vs yoga only, food handling, treatment elements); mid-term notifications to broker when new programme elements are added; documented response to broker enquiries at renewal; retention of policy documents and broker correspondence as evidence.
There is no insurance response to insurance non-disclosure — that's the point. The cover that should have responded doesn't. The only mitigation is at the proposal stage: detailed declaration, broker discipline, and renewal review. Specialist wellness retreat broker placement makes a material difference here — generic brokers often miss the specific declarations that retreat work requires (PTR scope being the most consequential), while specialist brokers know exactly what each insurer expects to see at proposal.
14. What drives the cost of wellness retreat insurance in 2026?
Wellness retreat insurance pricing in 2026 reflects the regulatory complexity (PTR 2018, fire safety, food allergens) and the genuine claim exposure differential vs generic small business cover. Indicative annual premium ranges, which can be benchmarked against our broader specialist cost guides:
| Business Profile | Indicative Annual Premium 2026 |
|---|---|
| Sole day retreat operator — no overnight, £15k–£40k turnover | £480–£950 |
| Weekend retreat operator (third-party venue) — £40k–£150k turnover | £1,400–£3,800 |
| Venue-owning residential retreat — £150k–£500k turnover | £3,500–£8,500 |
| Multi-discipline residential operator — £200k–£700k turnover | £5,500–£12,500 |
| UK-organised overseas retreat operator — £300k–£1m turnover | £7,500–£15,000 |
| Mid-sized regional retreat operator — £500k–£2m turnover, multi-venue or multi-event | £9,500–£18,000+ |
The factors below drive both insurance premium and overall risk management investment. The rating impact within each profile band is typically larger than the differential between profile bands — meaning a small operator with excellent documentation can pay less than a larger operator with poor documentation.
| Rating Factor | Impact on Premium | What You Can Do |
|---|---|---|
| Retreat format and discipline mix | Day retreats lowest; overseas and multi-discipline highest | Declare every format and activity type specifically; misdeclaration is the #1 claim dispute |
| PTR 2018 compliance maturity | Mature compliance reduces premium 10–20% across programme | Documented PTR analysis, financial protection in place, pre-contractual info systematised |
| Annual turnover and number of retreats | Primary scaling factors for PL, EL, PI | Declare accurately including planned growth |
| Cold water and breathwork programming | Adds 15–30% to PL where included; essential to declare | Document facilitator competency, contraindication screening, session protocols |
| Food handling scope | On-site catering for allergen-sensitive guests adds 10–20% | Level 2/3 Food Safety training records, allergen procedures, Natasha's Law compliance |
| Venue ownership | Owned venue adds Property + BI but improves overall portfolio rating | Comprehensive Property cover essential; fire RA documentation reduces loadings |
| Overseas territorial scope | Worldwide cover typically adds 30–50% to PL line | Specific declaration; ATOL compliance where flights included |
| Claims history | 5+ year impact; PI claims for retreat outcomes particularly material | Root cause analysis and remedial documentation after any claim |
| Practitioner certification and ongoing training | Recognised body affiliations (Yoga Alliance, CNHC, etc.) reduce 5–10% | Maintain at staff level; evidence at every renewal |
| Limits selected | £5m/£10m PL rate differently; £500k/£1m PI material | Match to retreat values and corporate panel requirements |
| Broker placement | Specialist retreat brokers access better terms than generic placement | Use a broker with specialist hospitality and PTR experience |
| Continuity with insurer | 3+ years with same insurer typically reduces renewal premium 5–10% | Strategic continuity decision; don't chase £100 savings |
15. Real claims and how to manage them
Claim — Breathwork-Triggered Psychiatric Decompensation, £68,000 PI Settlement
A mid-sized residential retreat operator hosted a 4-day "transformational" retreat at a country house venue including yoga, group emotional processing, plant-based meals, and three sessions of conscious connected breathwork (a high-intensity holotropic-style breathing technique). A guest in her late 30s with undisclosed history of bipolar II and recent SSRI medication adjustment attended having been recommended by a friend. Her booking health declaration was a single-page form asking only about physical contraindications (cardiac, pregnancy, recent surgery) — no specific question about psychiatric history or current medication.
During the second breathwork session, the guest experienced acute psychosis with persecutory delusions and disorganised thought. She was unable to be calmed within the session and was admitted to a local NHS Mental Health crisis unit for 8 days. Following discharge, she required 4 months off work and intensive psychiatric follow-up. She brought a PI claim against the retreat operator alleging: inadequate health screening for psychiatric history; inadequate practitioner competency in trauma-informed breathwork delivery; inadequate emergency response protocols; failure to advise that intensive breathwork can trigger acute psychiatric episodes in predisposed individuals.
The operator's documentation review identified: health declaration form was generic and did not capture psychiatric history; breathwork facilitator held a 20-hour breathwork instructor certification but no specific training in trauma-informed practice; no documented contraindication policy for breathwork programming; no emergency response protocol for psychiatric crisis. The operator's £1m PI responded after substantial dispute. Settlement: £68,000 (psychiatric treatment costs, lost earnings, future earnings impact, general damages). Defence costs: £14,500. Total claim: £82,500.
Post-claim renewal: PI premium increased 38%. Insurer required: comprehensive health declaration including psychiatric history and current medication; written contraindication policy for high-intensity practices; trauma-informed practitioner training evidenced at proposal; documented emergency response protocol with local NHS pathway. The operator implemented these and at the following renewal premium returned to a 16% loading over baseline.
The lesson: wellness retreats actively recruit vulnerable participants and use intensive practices that can have material adverse effects. Generic health screening fails. The documentation pack that defends these claims — proper screening, contraindication policy, trained facilitators, emergency response — is the same documentation pack that prevents them.
Claim — Food Allergen Anaphylaxis, £124,000 PL Settlement
A small residential retreat operator hosted a weekend yoga and detox retreat at a Devon manor house venue with full on-site catering by a sub-contracted chef. The retreat marketed itself as "anti-inflammatory" with plant-based, gluten-free, dairy-free menus. A guest declared at booking that she had a confirmed nut allergy with previous moderate anaphylactic reactions and carried two adrenaline auto-injectors. The booking system captured the allergy but did not flag it through to the chef's prep list. A Saturday lunch dish included a cashew-based dressing on a salad. The guest consumed approximately three bites before tasting the dressing, immediately experienced lip swelling and tongue tingling, self-administered her first adrenaline auto-injector, and called for help.
The retreat staff response was initially appropriate (999 called, second auto-injector administered, recovery position) but the guest's reaction was severe — she progressed to full anaphylaxis with airway compromise, lost consciousness, and required CPR before paramedics arrived. She was hospitalised for 6 days and required ICU monitoring for 48 hours. Following discharge, she developed psychiatric sequelae including PTSD and panic disorder requiring extended treatment.
The guest brought a PL claim alleging: failure to communicate her declared allergy to the catering team; inadequate ingredient labelling on the meal served; inadequate Natasha's Law compliance for the salad which had been pre-prepared and could be considered PPDS; inadequate staff allergen training. The operator's documentation review identified: booking system did capture the allergy but no documented hand-off process to the chef existed; no written allergen ingredient list for the meal; chef had Level 2 Food Safety certification but no specific Natasha's Law training; no verbal allergen confirmation at point of service. The operator's £5m PL responded.
Settlement: £124,000 (medical costs, lost earnings, future earnings impact, PTSD treatment, general damages). Defence costs: £18,000. Total claim: £142,000.
Post-claim renewal: PL premium increased 32%. Insurer required: documented allergen hand-off process from booking to kitchen; written ingredient lists per meal with allergens emphasised per Natasha's Law; chef Level 3 Food Safety qualification minimum; verbal allergen confirmation at point of service evidenced via service-completion checklist; mandatory adrenaline auto-injector on-site stocked separately from guest's own.
The lesson: food allergen exposure at wellness retreats is acute. The clientele has high prevalence of food sensitivities; the menus are complex and ingredient-rich; the catering scale is typically too small to support formal commercial allergen management systems by default. Documented hand-off and verification procedures aren't optional — they're the only defensible standard, and the only thing that prevents the next claim being a fatal anaphylaxis.
Claim — Operator Insolvency Refund Liability, £186,000 Total Exposure
A medium-sized UK wellness retreat operator running residential retreats in the Cotswolds and an annual overseas retreat in Portugal experienced cashflow difficulties through 2024 after a venue partner increased rates significantly. The operator had taken deposits from 64 forward-booked guests across three upcoming retreats totalling £186,000 in client money. The operator had no ABTOT bonding, no trust account arrangement, and no insurance-based financial protection. Deposits had been used for operating expenses. In early 2025 the operator entered administration.
The administrators discovered that PTR 2018 financial protection had never been put in place. Trading Standards opened a criminal investigation against the operator's two directors personally under Regulation 19 of PTR 2018. Guests collectively brought civil claims for refunds; without protection, they ranked as unsecured creditors and ultimately received approximately 8 pence in the pound. The directors faced personal prosecution; both pleaded guilty to PTR 2018 offences and received community sentences plus combined personal fines of £42,000 (uninsurable). Defence costs (insurable via Legal Expenses where in place — it wasn't): £38,000 personal exposure for the directors.
The lesson here is unusual because it sits outside the standard claim model — the £186,000 was traveller refund exposure, not an insurance claim. But it illustrates the point: the criminal offence under PTR 2018 is committed at the moment client money is taken without protection, not at the moment of insolvency. The operator was committing the offence on every deposit taken across multiple years. Specialist broker placement at any point in those years would have identified the gap and arranged ABTOT bonding (estimated £4,500 annually for the operator's volume) or insurance-based protection (estimated £5,500–£7,500 annually). Either would have prevented the criminal exposure entirely and preserved the option of meaningful traveller refunds. Generic small business insurance brokers don't ask about PTR exposure because they don't recognise wellness retreats as tour operator activity. Specialist brokers do.
Claims Management Steps
How to respond to a wellness retreat incident or regulatory engagement — the steps below are critical given the multi-policy and multi-regulator exposure typical of 2026 retreat work:
- Make the site safe and protect persons first. Standard response. Medical response (999 for acute, escalation to local A&E or psychiatric crisis services) takes priority over administrative steps. For breathwork incidents, anaphylaxis, cold immersion incidents, or psychiatric crisis, the on-site emergency response runs in parallel with claim notification.
- Notify your insurer immediately for any potential claim. Retreat incidents often engage multiple policies (PL, PI, EL, Legal Expenses, Tour Operator Liability). Single notification triggers coordinated response. Threshold is "may give rise to a claim" — much lower than "formal claim received".
- Preserve all documentation rigorously. Pre-arrival health declaration; informed consent forms; programme materials; practitioner qualifications; food preparation records and ingredient lists; fire RA; pre-contractual information delivered to the participant; booking records and payment trail; photographs of venue and incident location; staff statements taken promptly; participant communications. The documentation pack is the defence across all coverage layers.
- Do not admit liability or fault. Provide factual information about what happened, what programming was delivered, what protocols were followed. Do not accept fault, apologise in writing, or commit to remedial work that could be interpreted as admission. Compassionate response to participant welfare is right; admission of liability is not the same thing and should be avoided.
- Manage regulatory engagement carefully. If Fire and Rescue Service, Environmental Health (food incidents), HSE, or Trading Standards (PTR) attend or notify, engage Legal Expenses insurer immediately. Cooperate factually with inspectors but do not provide written statements without legal representation. Regulatory investigation can become criminal prosecution.
- Engage with the participant constructively but procedurally. Offer welfare support and reasonable assistance with immediate practical issues (transport, accommodation, medical access). Do not enter substantive discussion of liability, settlement, or fault. Refer all such discussion to your insurer's claims team or appointed solicitor.
- Conduct root cause analysis and document remedial action. Identify underlying cause and implement remedial action — improved health screening, additional facilitator training, updated allergen procedures, fire RA review, PTR documentation strengthening. Insurers reviewing renewal will ask what's changed since claim; regulators will require evidence of remedial action.
- Update operational documentation to address gap. Where the claim identified a documentation gap (no contraindication policy, no allergen hand-off process, no PTR financial protection), update the standard operating procedure to close the gap. This is both insurance and regulatory defence going forward, and is the primary route back to renewable premium terms.

Glossary of wellness retreat insurance terms
- Package Travel Regulations 2018 (PTR 2018)
- The Package Travel and Linked Travel Arrangements Regulations 2018. UK statutory framework governing the sale of packaged travel services. A package is created when two or more travel services (accommodation, transport, car rental, or "other tourist service" significant to the package) are combined for the same trip. Wellness retreats combining accommodation + activities fall within scope.
- Tour Operator Liability
- The strict liability of a package organiser under PTR 2018 for the performance of all travel services included in the package — including services performed by third-party suppliers (self-employed yoga teachers, contracted chefs, transport providers). Generic Public Liability may not contemplate this scope; specialist tour operator liability cover does.
- Linked Travel Arrangement (LTA)
- A weaker form of package under PTR 2018 where a traveller buys one travel service from a trader and is then prompted to buy another within 24 hours but payment details are not transferred. LTAs have insolvency protection requirements but lighter contractual liability than full packages.
- ABTOT (Association of Bonded Travel Organisers Trust)
- A UK approved body providing financial protection bonding for tour operators under PTR 2018. ABTOT membership provides traveller refund and repatriation protection in the event of operator insolvency and is a common compliance route for smaller and medium retreat operators.
- ABTA (Association of British Travel Agents)
- UK travel industry trade body offering bonding and financial protection for member tour operators. ABTA membership is more typical for larger retreat operators or those with substantial international scope.
- Trust Account (PTR Compliance)
- A separate bank account where client money paid in advance is held in trust until the package is delivered. Provides PTR 2018 financial protection by ensuring client money remains accessible for refund if the operator becomes insolvent. Requires appropriate banking arrangement and protocol discipline.
- Regulatory Reform (Fire Safety) Order 2005
- The UK statutory framework governing fire safety in non-domestic premises including paying guest accommodation. Imposes Responsible Person duties for fire risk assessment, fire safety measures, and maintenance. Updated under Section 156 of the Building Safety Act 2022 and from 1 October 2023 to require written FRA regardless of staff numbers in paying guest accommodation.
- Responsible Person (Fire Safety)
- The person with control of the premises during paying guest occupation under the Fire Safety Order 2005. Bears personal duties including conducting suitable and sufficient fire risk assessment, ensuring adequate fire safety measures, and maintaining them. Non-compliance can result in fines (unlimited) or imprisonment.
- Natasha's Law
- The popular name for the Food Information (Amendment) (England) Regulations 2019, in force October 2021. Requires all prepacked-for-direct-sale (PPDS) food to carry full ingredient labelling with the 14 major allergens emphasised. Applies to grab-and-go food items at wellness retreats prepared and packaged on the premises.
- Benedict's Law
- Announced by the UK Government in March 2026 following the inquest into the 2021 death of 5-year-old Benedict Blythe. Statutory guidance under consultation in 2026 with implementation September 2026, primarily directed at schools but signalling the regulatory direction of travel on allergen management in settings catering to vulnerable individuals.
- PPDS (Prepacked for Direct Sale)
- Food that is made on the premises and packaged for sale before being ordered, including sandwiches, salads, and prepared meals at counter or self-service. Subject to Natasha's Law full ingredient labelling requirements.
- 14 Major Allergens
- The allergens that must be emphasised in food labelling under UK law: celery, cereals containing gluten, crustaceans, eggs, fish, lupin, milk, molluscs, mustard, nuts (tree nuts), peanuts, sesame seeds, soybeans, sulphur dioxide and sulphites.
- Cold Water Immersion / Wim Hof Method
- Practices involving deliberate exposure to cold water (ice baths, plunge pools, cold showers) combined with specific breathing techniques. Mainstream in UK wellness retreats since 2022. Requires documented contraindication screening, competent supervision, and emergency response equipment.
- Holotropic / Conscious Connected Breathwork
- High-intensity breathing techniques used in wellness retreats for emotional processing and altered states. Can trigger psychiatric decompensation in predisposed participants and physical complications (pulmonary barotrauma, loss of consciousness). Requires trained facilitators and contraindication screening.
- Treatment Risk Cover
- Specialist insurance scope covering claims arising from the treatment or therapy work itself — methodology, advice, programme design, third-party practitioner vicarious responsibility. Distinct from generic PI which may respond only to direct professional negligence.
- Run-off Cover (PI)
- Professional Indemnity cover that continues to respond to claims notified after the policy has ended (provided the work was performed during the original policy period). Essential for retreat operators where participant claims can surface months or years after the retreat ended.
- Insurance Act 2015 — Fair Presentation
- UK statutory framework governing the proposal stage of business insurance. Requires the policyholder to make a "fair presentation of the risk" — proactive disclosure of every material fact the insurer would want to know. Failure can result in policy avoidance, claim reduction, or imposition of retrospective terms.
Frequently asked questions
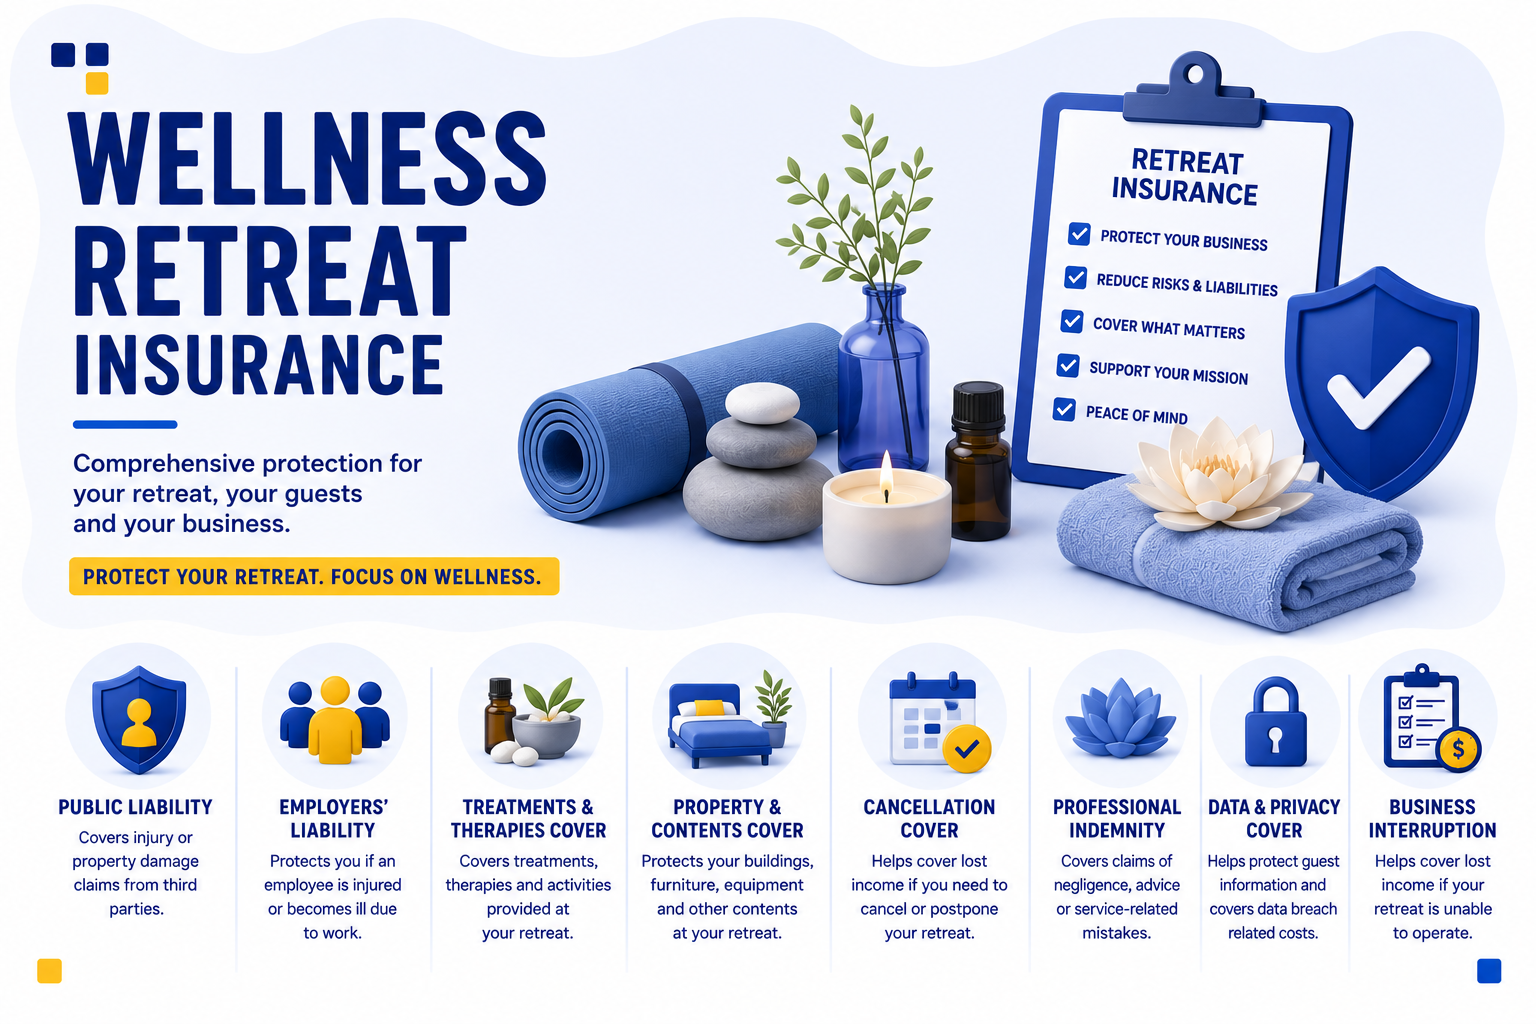
Wellness retreat business insurance is specialist commercial insurance designed for residential and day retreat operators including yoga, meditation, breathwork, detox, cold water, and corporate wellbeing programmes. The core covers in 2026 are: Public Liability with tour operator liability, food risk, and hazardous activity scope; Employers' Liability with practitioner and staff scope; Professional Indemnity with retreat-specific scope including third-party practitioner vicarious responsibility; Property and Business Interruption where venue-owned; Legal Expenses with PTR, fire safety, and food hygiene scope; insolvency protection (ABTOT, trust account, or insurance-based) for client money. The cover differs fundamentally from generic yoga teacher insurance or small B&B insurance — those typically omit tour operator liability scope which is the most consequential exposure for retreat operators under PTR 2018.
Yes — almost all UK residential wellness retreats fall within PTR 2018. The regulations apply when two or more travel services (including accommodation plus any "other tourist service" significant to the package, such as yoga sessions, breathwork, treatments, or guided activities) are combined for the same trip and sold at an inclusive price. The standard wellness retreat structure — overnight accommodation plus programmed activities sold at a single price — meets this definition. The operator is the "organiser" with full tour operator responsibilities including pre-contractual information duties, financial protection of client money, strict liability for third-party supplier performance, and criminal liability for non-compliance. Day retreats without overnight accommodation typically fall outside scope. UK-organised overseas retreats fall within scope regardless of where the retreat takes place.
Indicative 2026 annual premiums: sole day retreat operators £480–£950; weekend retreat operators at third-party venues £1,400–£3,800; venue-owning residential retreats £3,500–£8,500; multi-discipline residential operators £5,500–£12,500; UK-organised overseas retreat operators £7,500–£15,000; mid-sized regional operators £9,500–£18,000+. Pricing depends on retreat format, PTR compliance maturity (mature compliance reduces premium 10–20%), discipline mix (cold water and breathwork add 15–30% to PL), food handling scope, claims history, limits selected, and broker placement type. Specialist placement is typically 1.4–2× generic small business cover but the differential reflects genuine claim exposure differential.
Employers' Liability is legally required if you have staff (including sub-contracted facilitators in some arrangements) under the Employers' Liability (Compulsory Insurance) Act 1969 — fines of £2,500 per day for non-compliance. PTR 2018 financial protection of client money is legally required for packaged retreats and failure is a criminal offence (not a civil insurance question). Public Liability is not legally required by statute but is required by virtually all venue contracts, corporate panel agreements, and insurance brokers placing PTR-compliant cover. Other covers (PI, Property/BI, Legal Expenses) are commercially essential but not legally required.
Almost certainly not for the tour operator liability scope. Yoga teacher policies are designed for the practitioner's own work — delivering classes, teaching sequences, providing instruction. They typically include PL £5m–£10m and PI for the practitioner's negligence in teaching. They do not typically include tour operator liability under PTR 2018, strict liability for third-party practitioners you contract for a retreat, PTR financial protection of client money, food risk for catering you provide, or hazardous activity scope for cold water and breathwork. If you run residential retreats with overnight accommodation and combined activities, you need a specialist retreat insurance programme, not extension of your teacher policy. See our alternative therapies insurance resource for context on the underlying cover differences.
ABTOT (Association of Bonded Travel Organisers Trust) is a UK approved body providing financial protection bonding for tour operators under PTR 2018. ABTOT membership provides traveller refund and repatriation protection in the event of operator insolvency. You need ABTOT membership, ABTA membership, a compliant trust account arrangement, or insurance-based financial protection — but you must have one of these if you take advance payment for packaged retreats. The right choice depends on your retreat volume, package values, cashflow profile, and operational preference. ABTOT is popular for small-to-medium operators because the membership and bonding costs are predictable; trust accounts are popular for very small operators because the upfront cost is lower; insurance-based protection is widely available for established operators. Specialist brokers can advise on the right mechanism for your specific business.
Yes — particularly under the 2026 framework. PI was historically optional for many retreat operators; under PTR 2018 and the rising claim pattern around practitioner-led therapy, programme design, and warranty disputes, it has become functionally essential. The claim drivers are: unsuitable programme design for participant condition; negligent advice on dietary or recovery protocols; inadequate participant screening; practitioner injury from instruction or adjustment; psychological harm from intensive practices; warranty-style claims about retreat outcomes. Limits typically £500k for small operators; £1m–£2m for residential and multi-discipline work. Run-off cover is important — participant claims can surface months or years after the retreat. See our professional indemnity insurance resource for cover principles.
The combination of insurance non-disclosure under the Insurance Act 2015 and PTR 2018 financial protection non-compliance. The pattern: operator buys yoga teacher insurance or small B&B insurance with generic activity declared, runs packaged retreats taking advance payment without specific tour operator declaration or financial protection. Two consequential exposures crystallise. (1) Insurance non-disclosure: any claim involving tour operator liability, food risk, or hazardous activity becomes uninsured because the activity wasn't declared. (2) PTR financial protection non-compliance: operator commits a criminal offence on every advance payment taken. The fix at proposal stage is minimal cost; the retrospective cost is potentially every uninsured claim across multiple policy years plus personal criminal exposure for directors.
Only if specifically declared and scoped. Generic PL frequently excludes cold water immersion and breathwork specifically; specialist retreat cover should explicitly include them with documented operational protocols as the underwriting basis. The cover responds to participant injury during properly conducted sessions where contraindication screening, facilitator competency, and supervision protocols were in place. Where claims surface, the documentation pack (contraindication policy, facilitator qualifications, session protocols, informed consent) is the primary defence. Claim values typically £12,000–£90,000; severe outcomes can reach £200,000+. The premium uplift for hazardous activity scope is typically 15–30% on the PL line; the claim exposure without it is potentially much larger.
Under Natasha's Law (October 2021), prepacked-for-direct-sale food must carry full ingredient labelling with the 14 major allergens emphasised. More broadly, the duty of care owed to participants with declared allergies is acute. The working standard for UK wellness retreats: pre-arrival dietary declaration capturing all allergies and intolerances; documented hand-off process from booking to catering team; written ingredient lists per meal with allergens emphasised; chef qualification minimum Level 3 Food Safety with specific allergen training; verbal allergen confirmation at point of service evidenced via checklist; immediate access to adrenaline auto-injectors with staff trained in emergency response; food incident reporting protocol. The newer regulatory direction under Benedict's Law (statutory guidance September 2026) signals that even higher standards will become expected through 2026–2027.
UK-organised overseas wellness retreats fall fully within PTR 2018 regardless of where the retreat takes place — the regulations apply to all package travel contracts sold or offered for sale in the UK. The insurance programme must include: Tour Operator Liability with overseas territorial scope; Worldwide Public Liability £5m–£10m with strict liability for overseas supplier performance; Professional Indemnity £1m with worldwide territorial scope; Group travel insurance for participants (separate from operator's liability cover, providing medical, repatriation, and cancellation cover for guests); Legal Expenses with PTR, contract, and overseas jurisdiction scope; ABTOT or ABTA bonding strongly indicated for overseas package insolvency protection. ATOL compliance applies in addition to PTR where flights are included or facilitated as part of the package. Costs typically £7,500–£15,000+ for established overseas operators.
Look for brokers with specific experience in wellness, hospitality, and tour operator risk evidenced by: specialist articles or guides discussing PTR 2018 and tour operator liability for retreats; willingness to discuss specific exposures (PTR financial protection, cold/breathwork scope, mental health screening, Natasha's Law) in detail; access to Lloyd's market and specialist MGAs rather than just mainstream commercial markets; FCA authorisation and documented track record. Avoid brokers offering "yoga teacher insurance" or "small B&B package" without discussing PTR specifics; brokers who can only quote one or two markets; brokers who don't ask about tour operator scope at proposal. Miller & Partner specialise in this sector — see our broader alternative therapies insights hub for related guides, and our alternative therapies product page for cover details.
Related guides from Miller & Partner
Related specialist cover
Other wellness and treatment businesses we insure
Treatment-led businesses share the same liability questions. These are the sectors we place most alongside retreats.







Instagram
LinkedIn