


The Expert Guide to Tradesman Liability Insurance Specialist UK 2026
Why is tradesman liability insurance the foundation of every trade business?
Tradesman liability insurance is the spine of every trade business in the UK — and in 2026 it carries more weight than it ever has. Tools sit in the back of vans worth £4,000 on a good day and £15,000 on a bad one. A drilled-through water main floods a kitchen extension on a Friday afternoon. A roof tile slips and damages a customer's neighbour's car. An apprentice falls from a ladder that wasn't properly footed. Each of these scenarios — routine in the trades — generates a financial event that can run from a few hundred pounds to mid-six figures, and the question of whether the trade business survives that event depends almost entirely on whether the liability insurance was set up correctly.
What's changed in 2026 isn't the core risk landscape — that's always been brutal in the trades — but the regulatory, claims, and underwriting environment around it. Tool theft has risen to roughly £99 million in annual losses with "peel and steal" van attacks now the dominant theft method. The Health and Safety Executive (HSE) continues to prosecute sole traders and small construction firms aggressively under the Work at Height Regulations 2005 — including suspended prison sentences for serious failures. The Building Safety Act 2022 Gateway 3 process now applies in earnest through 2026, raising competence expectations even for smaller trades touching higher-risk buildings. And the Insurance Act 2015 continues to allow insurers to avoid policies entirely where work activities weren't properly declared at proposal.
This guide is the definitive 2026 UK tradesman liability insurance article — built around the genuine claim-driving exposures (Public Liability, Employers' Liability, Tools, Contract Works, Professional Indemnity, Commercial Vehicle), the regulatory framework that shapes them, and the trade-specific pricing realities. It complements our broader contractors combined insurance product page and sits alongside our tradesman cluster including cheap tradesman insurance, the trade-specific guides on floor fitters, carpenters, painters and decorators, HVAC engineers, and welders.
Key facts at a glance
- Employers' Liability is legally required from the moment you hire anyone — apprentice, labour-only subcontractor, part-time worker, or family member outside a 50/50 partnership. Failure to hold £5m+ EL exposes the business to fines of £2,500 per day under the Employers' Liability (Compulsory Insurance) Act 1969.
- Public Liability isn't legally required but is contractually unavoidable — virtually every commercial client, local authority, social housing landlord, and main contractor specifies £2m–£5m PL minimum before a job can start. Most trade bodies (Gas Safe, NICEIC, NAPIT) require it for registration.
- UK tool theft hit £99 million in 2025 with 94% of stolen tools never recovered — and "peel and steal" van attacks (where doors are forced open) are now the dominant theft method, having replaced whole-van theft as vehicle security improved.
- Work at height remains the leading cause of UK construction fatalities — over a quarter of fatal worker injuries in 2024/25 — and the HSE prosecuted multiple sole traders and small builders in 2025/26 under the Work at Height Regulations 2005, including an 8-month suspended prison sentence for a Buckinghamshire roofing sole trader.
- The Building Safety Act 2022 Gateway 3 regime is active throughout 2026 — even small trades touching higher-risk buildings now face competence declarations and golden thread documentation obligations that flow back from main contractors.
- Indicative 2026 annual premiums run roughly £150–£400 for a sole-trader low-risk trade (decorator, gardener) and £600–£2,400+ for higher-risk trades (roofer, scaffolder, electrician with employees). Specialist broker placement consistently beats price-comparison routes on cover scope and claim certainty.
- Insurance non-disclosure under the Insurance Act 2015 is the most common reason claims are reduced or declined — typically because the trade declared at proposal didn't match the work actually being carried out, or because work at height, hot works, gas work, or subcontract labour wasn't specifically declared.
1. What does tradesman liability insurance actually cover in 2026?
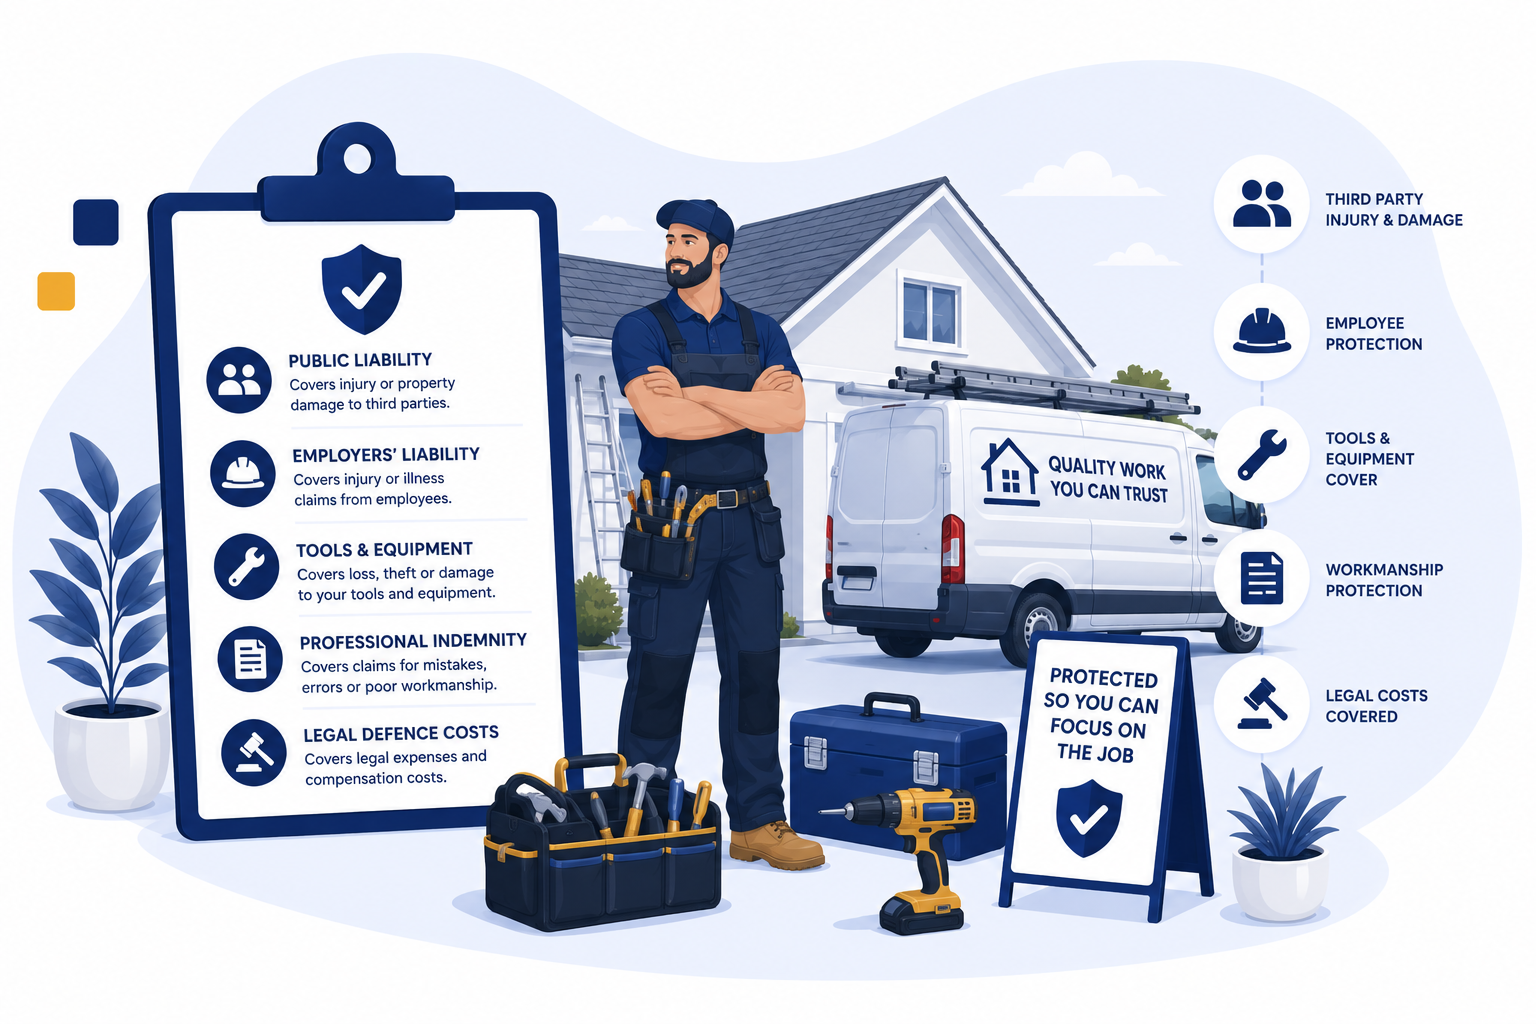
"Tradesman liability insurance" isn't a single policy — it's a programme. Most tradesmen buy it as a packaged product from a specialist insurer where the constituent covers sit alongside each other under one schedule. The table below shows the eight core covers in the 2026 tradesman programme, ranked by criticality, with the legal/contractual status of each. Some are non-negotiable (Employers' Liability if you have anyone working for you); some are contractually required by every meaningful client (Public Liability); some are commercially essential but technically optional (Tools, Contract Works).
| Cover | What It Does | Status |
|---|---|---|
| Public Liability | Third-party injury and property damage claims from your work | Contractually required by virtually every client |
| Employers' Liability | Staff and labour-only subcontractor injury and disease claims | Legally required if you have any staff — £2,500/day fine |
| Tools and Equipment | Theft, accidental damage, fire to hand tools and equipment in van/site/storage | Commercially essential — £99m annual UK theft losses |
| Contract Works (CAR) | Damage to ongoing works before completion — fire, flood, theft, vandalism | Contractually required on most building/extension work |
| Commercial Vehicle | Van/pickup with business use; personal car insurance does NOT cover trade use | Legally required if using vehicle on roads |
| Professional Indemnity | Claims arising from design, specification, advice, or certification work | Required for any design/certification element (electricians, heating engineers, designers) |
| Personal Accident | Income replacement if you're injured and can't work — sole-trader-critical | Commercially essential for sole traders |
| Legal Expenses | HSE investigation defence, contract disputes, debt recovery, employment tribunal | Strongly recommended — HSE prosecutions cost £50k+ to defend |
The error pattern we see most often when reviewing existing tradesman cover is treating this list as a menu where each item is independent. In practice the covers interact — a single incident can engage four or five of them at once. A scaffold collapse on a roofing job triggers Public Liability (third-party injury), Employers' Liability (worker injury), Tools cover (damaged equipment), Contract Works (damaged ongoing works), and Legal Expenses (HSE investigation). Buying these as a coordinated package from a single specialist insurer means one notification triggers all of them; buying them from separate providers fragments the response.
2. Is tradesman liability insurance a legal requirement in the UK?
The legal-requirement question is the most common single misconception in the trades, and getting it wrong creates immediate exposure. The honest answer is layered: Employers' Liability is legally required as soon as you have any employees; Public Liability isn't legally required but is contractually required by virtually every meaningful client; some trade bodies make Public Liability a registration condition.
Employers' Liability — Legally Required
Under the Employers' Liability (Compulsory Insurance) Act 1969 you must hold a minimum of £5 million EL cover from the moment you employ anyone — including apprentices, part-time workers, casual workers, labour-only subcontractors, and short-term hires. The certificate must be displayed where employees can see it (the modern interpretation is electronic display is acceptable). Trading without legally required EL exposes the business to fines of £2,500 per day. The few exceptions are: 50/50 business partnerships where there are no other employees; family-only businesses where only close family members work; and unincorporated bodies where all workers are based outside the UK. Most tradesmen are not covered by these exceptions.
Public Liability — Not Legally Required, But Functionally Mandatory
Public Liability is not a statutory requirement under any UK Act. However, the practical position in 2026 is that virtually every commercial client, local authority, social housing landlord, NHS trust, main contractor, school, and insurance panel requires evidence of PL before a contract can start. Typical minimums: £1m for very small domestic work; £2m for most general trade work; £5m for commercial and local authority contracts; £10m for higher-risk trades (roofing, demolition) and main contractor work on larger projects. Trade body registrations frequently require it as a precondition — Gas Safe, NICEIC, NAPIT, FENSA, PCA, TrustMark, and most scheme operators.
Commercial Vehicle Insurance — Legally Required
If you use a vehicle on UK roads, motor insurance is legally required under the Road Traffic Act 1988. Critically, personal car insurance does NOT cover business use beyond very limited "commuting to a single place of work" scope. Driving a van between client sites, carrying tools and materials, or using a car for sales/inspection visits all require commercial vehicle cover. Driving on personal cover for trade use means the policy doesn't respond at claim stage and the driver is committing a criminal offence under the Road Traffic Act.
3. What does Public Liability insurance cover for tradesmen?
Public Liability — The Foundation Trade Cover
Public Liability responds to claims from third parties — typically clients, members of the public, or property owners — for personal injury or property damage arising from your work or your presence on site. The headline scenarios are well known: a tradesman drills through a hidden water main and floods a client's property; a customer or visitor trips over tools left at a site entrance; a falling roof tile damages a neighbour's car parked on the street; a heating engineer's pipework joint fails overnight after a job is completed. PL claim values are dominated by property damage (typically £500–£25,000 routine, £25k–£150k+ for significant water damage or fire) and personal injury (£5k–£50k for soft tissue/fractures, £100k–£1m+ for life-changing injuries).
Third-party bodily injury including medical costs, loss of earnings, and general damages; third-party property damage including direct repair costs, consequential damage (water spreading to lower floors, fire spreading to adjacent buildings), and alternative accommodation costs; legal defence costs; settlement costs negotiated by the insurer. Pollution caused by sudden and accidental incidents (e.g. an oil spill from a damaged pipe) is typically covered; gradual pollution typically isn't.
Damage to property in the tradesman's custody, care, or control (typically sub-limited or excluded — this is what Contract Works cover addresses); work at heights above the declared limit (commonly 10m default; roofing/scaffolding need declared higher limits); hot works without declared cover (welding, brazing, soldering near combustibles); rectification of the tradesman's own faulty workmanship (this is what Professional Indemnity addresses for design elements, or contractual warranty obligations for workmanship); gradual pollution and asbestos work without specific extension.
£1m: minimal — only suitable for very low-risk solo trade with no work near high-value property or vulnerable persons. £2m: standard floor for most small trade work. £5m: most commercial work, local authority contracts, work in larger residential buildings or near commercial premises. £10m: roofing, demolition, scaffolding, work in higher-risk buildings, larger main contractor work, social housing panels. The premium uplift from £2m to £5m is typically £40–£120; the uplift from £5m to £10m is typically £80–£250. Always carry the limit specified by your largest contract, not the smallest.
4. When is Employers' Liability insurance legally required?
Employers' Liability — The Statutory Cover
Employers' Liability responds to claims from employees, apprentices, labour-only subcontractors, and similar workers for injury or disease arising from their work. The cover is statutorily required from the moment of first hire; the standard limit is £10m even though the legal minimum is £5m, because the underwriting cost differential is minimal and the protection is materially better. The dominant claim categories in the trades are: falls from height (the leading UK construction killer, accounting for over a quarter of fatal worker injuries in 2024/25); manual handling injuries (back, shoulder, knee); hand-arm vibration syndrome (HAVS) from prolonged power tool use; occupational dermatitis and respiratory conditions; cuts, lacerations, and crush injuries.
The legal definition is broader than HMRC's employee/self-employed test. EL is required for: direct employees on PAYE; apprentices and trainees; part-time and casual workers; labour-only subcontractors (where you control how and when work is done); workers from agencies where the agency contract puts the duty on the host business; family members other than close family in unincorporated businesses. EL is generally NOT required for: bona fide self-employed subcontractors on fixed-price contracts with their own insurance; close family in 50/50 family-only partnerships. HSE has published guidance HSE40 on the boundary; the safe default is to assume EL is required and document the exception if it isn't.
Trade EL claims often surface years or decades after the exposure. HAVS, occupational asthma, noise-induced hearing loss, occupational cancers, and musculoskeletal degeneration develop over years of cumulative exposure. The EL policy that responds is the one in force at the time the exposure occurred — meaning records of employment dates, EL policy details, and certificate retention matter enormously. Insurers and the Employers' Liability Tracing Office (ELTO) maintain historical records, but small trade businesses with gaps in their EL history are exposed to claims they have no insurance to meet.
Routine trade EL claims (lacerations, minor falls, manual handling strains) settle £5k–£30k. Significant injuries (fractures, longer-term back problems, HAVS sensitisation) £30k–£150k. Catastrophic claims (spinal injury, head injury, fatality) can reach £500k–£3m+. The £10m standard limit reflects this catastrophic tail — even a small trade business with one operative can face a £1m+ claim from a single serious incident.
5. Do tradesmen need Professional Indemnity insurance?
Professional Indemnity — The Design and Advice Cover
The traditional view that PI is "for consultants, not tradesmen" no longer holds in 2026. Many UK trades now routinely undertake work with a design or specification element — electricians issuing certificates under Building Regulations Part P; heating engineers designing heating systems and Gas Safe certifying installations; renewables installers designing solar PV, heat pump, and EV charging configurations; structural specifications by builders and groundworkers; PAS 2035-aligned retrofit work; and increasingly fire safety, ventilation, and accessibility specifications. Where the work involves design, advice, certification, or specification — as opposed to pure execution of a third-party design — Professional Indemnity is required to cover claims for financial loss arising from errors in that professional element.
PI is essential where the tradesman undertakes: design work (system design, structural calculations, fire safety specifications, layout decisions); certification (NICEIC EICRs, Part P certificates, Gas Safe commissioning certificates, F-Gas declarations); specification and advice (telling a client what to install, sizing equipment, recommending products); and supervision of work designed by others where the supervision creates a duty of care. PI is generally not required for pure execution of a third-party design where the tradesman is following drawings and specifications without exercising professional judgement — though even here some PI exposure exists where the tradesman should reasonably have spotted a design defect.
£100k–£250k for small trade with limited design element; £500k–£1m for trades with substantial certification or design work (electrical contractors, heating engineers, renewables installers); £1m–£2m for trades working on insurance panels, main contractor projects, or higher-risk building work. Run-off cover is critical — PI claims can surface 2–10 years after the work was completed, and standalone PI run-off after retirement or business sale is essential to protect personal assets. See our professional indemnity insurance product page for limit selection guidance.
6. Tradesman liability insurance cover checker
Select your trade and business profile below to see the cover programme matched to your specific risk. For complete contract-works exposure see our contractors combined insurance product page; for very small or budget-focused trades see cheap tradesman insurance.
Tradesman Liability Insurance Cover Checker
Select your trade profile to see the recommended insurance programme matched to the 8 core covers
Sole Trader — Low-Risk Trade (Decorator, Gardener, Handyman)
- ESSENTIAL Public Liability £2m–£5m — declare actual work types accurately
- ESSENTIAL Tools and equipment cover at full replacement value (declare van overnight location)
- ESSENTIAL Commercial vehicle insurance with goods-in-transit scope
- RECOMMENDED Personal Accident — sole trader income protection
- RECOMMENDED Legal Expenses with contract dispute and debt recovery scope
- CONSIDER Contract Works if undertaking longer-duration projects with materials on site
- CONSIDER Employers' Liability immediately if any help is engaged — legal requirement
Sole Trader — Mid-Risk Trade (Plumber, Carpenter, Tiler, Plasterer)
- ESSENTIAL Public Liability £5m — declare water-damage exposure (plumber) or hot works (specific trades)
- ESSENTIAL Tools and equipment cover with declared overnight location and forced-entry conditions
- ESSENTIAL Commercial vehicle with goods-in-transit cover
- ESSENTIAL Personal Accident — your earning capacity is the business
- RECOMMENDED Contract Works £25k–£100k for ongoing project exposure
- RECOMMENDED Legal Expenses with HSE investigation scope
- RECOMMENDED Professional Indemnity £100k–£250k if any design/specification element
- CONSIDER Employers' Liability immediately if help engaged
Sole Trader — High-Risk Trade (Roofer, Scaffolder, Demolition)
- CRITICAL Work at height declared — heights above default must be specifically declared at proposal
- ESSENTIAL Public Liability £5m–£10m — most main-contractor work specifies £10m for roofing/scaffolding
- ESSENTIAL Tools and equipment cover with full forced-entry conditions documented
- ESSENTIAL Commercial vehicle including goods-in-transit and materials
- ESSENTIAL Personal Accident — high-risk income protection
- ESSENTIAL Contract Works £50k–£250k depending on project values
- ESSENTIAL Legal Expenses with HSE investigation scope — leading prosecution category in 2025/26
- CONSIDER Employers' Liability immediately if any labour engaged — legal requirement
Small Firm — 2-5 Staff or Labour-Only Subcontractors
- LEGAL Employers' Liability £10m — required from first hire under 1969 Act
- ESSENTIAL Public Liability £5m–£10m matched to contract requirements
- ESSENTIAL Tools and equipment scheduled across multiple vans
- ESSENTIAL Multi-vehicle commercial fleet insurance
- ESSENTIAL Contract Works appropriate to project values
- ESSENTIAL Legal Expenses with HSE, employment tribunal, contract dispute scope
- RECOMMENDED Professional Indemnity if any certification or design work undertaken
- RECOMMENDED Business Interruption cover for premises-based operations
- RECOMMENDED Cyber insurance for client data and quoting/invoicing systems
Electrical / Gas / Renewables — Certification Work
- CRITICAL Professional Indemnity essential — certification creates direct PI exposure
- ESSENTIAL Public Liability £5m — minimum for trade body registration (NICEIC, Gas Safe, NAPIT)
- ESSENTIAL Professional Indemnity £250k–£1m with certification scope
- ESSENTIAL Tools and equipment including specialist test equipment
- ESSENTIAL Commercial vehicle with goods-in-transit cover
- ESSENTIAL Hot works declared if welding/brazing/soldering near combustibles
- ESSENTIAL Legal Expenses including HSE and gas safe investigation scope
- ESSENTIAL Run-off PI provision for retirement or business sale
- CONSIDER Employers' Liability immediately if subcontract help engaged
Insurance Panel / Main Contractor Work
- CRITICAL Insurance panel and main contractor specifications typically dictate minimum limits — review before bidding
- LEGAL Employers' Liability £10m with full scope
- ESSENTIAL Public Liability £10m typically required by panels
- ESSENTIAL Professional Indemnity £1m–£2m
- ESSENTIAL Contract Works at full contract value or specified panel minimums
- ESSENTIAL Commercial vehicle fleet
- ESSENTIAL Legal Expenses with comprehensive regulatory scope
- ESSENTIAL Cyber insurance — panel data sensitivity
- ESSENTIAL Building Safety Act competence documentation for HRB-touching work
7. How does Tool and Equipment cover work for tradesmen?
Tool and Equipment Cover — The £99m Crisis Cover
Tool theft is the single most common claim category for UK tradesmen and the cover most likely to be inadequate when the claim arrives. The 2025 picture: roughly £99 million in annual UK losses, average claim values up 24% since 2020, and 94% of stolen tools never recovered. Whole-van theft has fallen 98% since 2023 as immobiliser and tracker technology improved — but thieves have adapted with "peel and steal" attacks where van doors are forced open with brute force, often in under 60 seconds. The result is that property damage to vans (broken locks, peeled doors, damaged frames) has become the most reported cause of tool loss in 2025.
Overnight location condition: nearly all policies require tools to be removed from vans overnight or kept only in vans that are locked in a secure compound, garage, or driveway with declared security. Many policies will not respond to overnight theft from a van parked on a public road. Forced-entry condition: cover typically only responds where there is evidence of forced entry — opportunistic theft from an unlocked or insecure vehicle may be excluded. Single-item limits: many policies cap individual tool claims at £500–£1,000 even where overall sum insured is higher, meaning a £2,500 cordless tool combo claim returns the single-item limit only. Excess: tool theft excesses are typically £150–£500 per claim and can apply per item or per incident.
Tool sums insured must be reviewed annually. Average claim values rose 24% since 2020 driven by inflation in cordless tool prices, specialist test equipment costs, and rising replacement costs for diagnostic kit. Underinsurance — where the declared sum is below true replacement cost — triggers proportional claim reduction under the principle of average. Schedule expensive items individually (battery platforms with multiple tools, specialist diagnostic equipment, brand-name power tool stations) rather than relying on a generic "tools" sum.
8. What is Contract Works insurance and when do you need it?
Contract Works (sometimes called Contractors All Risks or CAR) covers damage to the works being carried out — not to third parties or staff, but to the project itself. The classic scenario: a builder's extension is half-built, the partly-finished structure is damaged by fire/flood/vandalism/theft before completion, and the cost of re-doing the work falls on someone. Without Contract Works cover, that someone is typically the contractor. With it, the policy responds for fire, flood, storm, malicious damage, theft of materials on site, and accidental damage during construction.
Contract Works is contractually required on most building contracts (JCT contracts have specific Contract Works requirements built in), required by most main contractors before subbing a package, and increasingly required by clients on extension work, renovations, and refurbishments where the works represent a significant value increase to the existing property. Cover should be set at the full contract value — underinsurance means proportional claim reduction. Most policies extend automatically to materials on site, hired-in plant, and existing structures where work is being carried out (subject to declared values).
9. Why is Commercial Vehicle insurance separate from Public Liability?
Tradesman vehicles need commercial motor insurance separately from the public liability programme. Personal motor policies — even those with "business use class 1" extensions — typically don't cover vans, vehicles carrying tools and materials, or genuine trade use across multiple sites. Commercial vehicle cover for tradesmen typically includes: third-party liability on the road (legally required under the Road Traffic Act); accidental damage to the vehicle; theft; fire; goods in transit (tools and materials carried in the vehicle); breakdown and recovery as optional add-ons.
The interaction with tool cover matters: most tradesman tool policies require goods-in-transit to be insured separately under the vehicle policy for daytime risks (tools being moved between sites); the tool policy typically responds to overnight and on-site exposure. Misalignment between these two policies — where tools fall into a gap between vehicle goods-in-transit cover and standalone tool cover — is one of the most common cover failures we see at claim. See our broader commercial vehicle insurance cost guide for vehicle-specific pricing.
10. Insurance red flags self-check
The list below is the set of insurance red flags we see most often when reviewing existing tradesman cover for new clients. Each item, if true of your current cover, indicates a material gap or non-disclosure risk that needs addressing. Tick the items that match your situation — the unchecked items are your priority remediation list.
Tradesman Insurance Red Flags Self-Check
Click each item that's true of your current insurance setup. The more ticked, the higher your exposure to a reduced or declined claim.
-
Trade declared at proposal matches actual work types performed — including any specialist work like hot works, work at height above default limits, gas work, asbestos work, or roofing
-
Employers' Liability in place from first hire — including labour-only subcontractors, apprentices, casual workers, and family members outside 50/50 partnerships
-
Public Liability limit matches the highest single contract requirement — not the smallest; main contractors and insurance panels typically specify £5m–£10m
-
Tool sum insured reviewed annually with full replacement values rather than depreciated values; expensive items individually scheduled
-
Overnight location and security conditions on tool cover documented and complied with — typically requires van locked in compound, garage, or driveway with declared security
-
Commercial vehicle cover is in place with goods-in-transit scope for tools and materials — personal motor insurance with "business use" extension does NOT typically cover trade vehicles
-
Work at height declared above the policy default limit if you undertake roofing, scaffolding, or work over default (commonly 10m)
-
Professional Indemnity in place if any design or certification work undertaken — including electrical certificates, Gas Safe commissioning, Part P, renewables system design, retrofit specifications
-
Contract Works cover at full project value if undertaking building, extension, refurbishment, or renovation work
-
Hot works specifically declared if welding, brazing, blow-lamp soldering, or hot cutting performed near combustibles
-
Legal Expenses with HSE investigation scope in place — HSE prosecution defence costs typically £50k–£250k and fines themselves are uninsurable
-
Written broker confirmation that all actual work types are within declared scope — provides documentary evidence at claim stage that disclosure was complete
11. Tradesman operation risk assessor
Two factors drive tradesman insurance risk above all others: the trade itself (some trades are intrinsically higher-risk than others) and the operational profile (sole trader vs employer; domestic vs commercial; established vs new). Use the tool below to identify your specific risk profile.
Tradesman Operation Risk Assessor
Select your trade type and operational profile to see your specific risk profile and indicative cover package
12. How do Work at Height Regulations 2005 affect tradesman insurance?
Work at height is the single most prosecuted hazard category for UK trades. According to HSE statistics, falls from height accounted for over a quarter of all fatal worker injuries in 2024/25 — and the prosecution pattern across 2025 and into early 2026 makes clear that sole traders and small builders are not below the HSE's enforcement threshold. Three recent cases illustrate the range of outcomes:
Work at Height — The Dominant HSE Prosecution Category
The Work at Height Regulations 2005 require all work at height to be properly planned, appropriately supervised, and carried out in a manner that is — so far as reasonably practicable — safe. Regulation 4 establishes the duty to plan; Regulation 6 requires measures to prevent falls; Regulation 7 covers protection from falling objects. Breach is a criminal offence under the Health and Safety at Work etc. Act 1974, and the UK Sentencing Guidelines for health and safety offences mean even very small businesses can face £50k–£250k fines for breaches involving serious injury.
August 2025: Sole-trader roofer Gary Smith (trading as GJ Smith Roofing) fined £2,125 plus £5,445 costs at Luton Magistrates after a worker fell 10 feet from an unprotected flat roof — second HSE action against the same sole trader. November 2025: Skyladder Construction Limited fined £33,500 after a man died falling 2.5 metres through an uncovered skylight opening. May 2025: Roofrite (Shropshire) Limited fined £8,000 + £2,990 costs after a worker fell through an unprotected window opening. January 2026: Sole trader Daniel Jenner (trading as Jenner Roofing and Building Services) received an 8-month suspended prison sentence plus 280 hours unpaid work after a worker suffered life-changing injuries falling through a fragile rooflight. The prosecution threshold is low; consequences for sole traders include personal criminal records and suspended prison sentences.
EL responds to the worker injury claim. Legal Expenses with HSE investigation scope responds to defence costs (typically £50k–£250k for contested prosecutions). The criminal fine itself is uninsurable under UK public policy — D&O cover can support personal director defence costs but not pay the fine. Crucially: where work at height is performed above the policy's default declared limit (commonly 10m), or where the work involves fragile surfaces, ladders, or scaffold without specific declaration, the insurer can argue non-disclosure under the Insurance Act 2015 and avoid the EL claim entirely. Declaration discipline at proposal is the single biggest claim-certainty factor for trades with work at height exposure.
13. How does the Building Safety Act 2022 affect small trades in 2026?
The Building Safety Act 2022 introduced the most significant changes to UK building safety regulation in 40 years. Much of the public discussion has focused on developers, principal contractors, and accountable persons — but the cascade effect on small trades through 2026 is substantial. The Act applies in full to higher-risk buildings (HRBs — defined as at least 18 metres or 7 storeys with at least two residential units), and 2026 is the year Gateway 3 applications become routine as the first wave of HRBs constructed under the new regime reach completion.
Building Safety Act — Competence and Documentation Cascade
The three Gateways established by the Act create regulatory hold points at planning (Gateway 1), pre-construction (Gateway 2), and pre-occupation (Gateway 3). The Building Safety Regulator (BSR), housed within HSE, must approve each Gateway before a project can progress. From 2026 onwards, main contractors on HRB projects routinely require sub-contractor and trade competence declarations before placing work — and this cascades down to the smallest trade. A plumber subbed in to do a single bathroom on a 20-storey HRB now faces competence declaration requirements that did not exist in 2023.
Main contractors increasingly require evidence of: trade body registration with recognised competence schemes (NICEIC, Gas Safe, FENSA, NAPIT, PCA, TrustMark); documented training matrix per operative; Professional Indemnity cover where any specification or certification element exists; site-specific risk assessments and method statements; "golden thread" documentation contributions — photographic and written records of work as installed. Trades without this documentation face exclusion from HRB-related contracts and from many main contractor frameworks more broadly. Insurance markets reflect this: trades with documented competence frameworks attract better PI and PL terms; those without face restriction.
Even for trades not directly working on HRBs, the documentation expectations are cascading down the contractor chain. Insurance panels, social housing providers, NHS estates work, and local authority frameworks increasingly mirror BSA-aligned competence expectations even where the underlying property isn't a higher-risk building. The trades that adapted their documentation in 2024-2025 are now winning the work that wasn't available three years ago; those still working on a verbal-quote-and-invoice basis are being squeezed out of the higher-value contract layer.
14. What does tradesman liability insurance cost in 2026?
Tradesman insurance pricing in 2026 spans a wide range driven primarily by trade type, turnover, claims history, and operational scale. Indicative annual premium ranges for typical 2026 placements:
| Business Profile | Indicative Annual Premium 2026 |
|---|---|
| Sole trader, low-risk — decorator, gardener, handyman, £20k–£40k turnover | £150–£400 |
| Sole trader, mid-risk — carpenter, plasterer, tiler, £30k–£60k turnover | £250–£650 |
| Sole trader, plumber/heating — domestic focus, £40k–£80k turnover | £350–£850 |
| Sole trader, electrician — with PI and certification, £40k–£80k turnover | £450–£950 |
| Sole trader, roofer/scaffolder — work at height declared, £40k–£100k | £600–£1,800 |
| Small firm (2–5 staff) — general trade, including EL, £150k–£400k turnover | £1,400–£3,500 |
| Small firm, certification-based — electrical/heating/renewables with PI | £2,000–£4,500 |
| Mid-size firm (6–15 staff) — multi-trade, commercial work, £400k–£1.2m | £3,500–£9,000+ |
The factors below drive both insurance premium and overall risk management investment. The rating impact within each profile band is typically larger than the differential between profile bands — meaning a sole trader with poor documentation can pay more than a small firm with excellent documentation.
| Rating Factor | Impact on Premium | What You Can Do |
|---|---|---|
| Trade type | Primary driver — roofers/scaffolders pay 5-8× decorator rates | Declare actual work mix accurately; don't under-declare specialist work |
| Turnover | Scales PL and EL exposure; primary scaling factor for small firms | Declare accurately including planned growth; under-declaration is non-disclosure |
| Number of employees / labour-only subbies | Primary EL rating factor; £200–£500 per worker typical loading | Accurate headcount declaration; include casual and short-term workers |
| Work at height declaration | Higher declared heights = higher PL/EL premium but essential | Declare actual maximum working height honestly; non-disclosure voids cover |
| Hot works, gas, asbestos declarations | Specific loadings for each; non-disclosure is the dominant cover failure | Declare specifically; written broker confirmation that activities are in scope |
| Trade body registration | NICEIC, Gas Safe, PCA, NAPIT, FENSA etc. reduce premium 5-15% | Maintain registration; evidence at renewal |
| Years trading and claims history | 5+ year claim-free history attracts NCB and renewal discount | Document near-misses internally; don't hide claims history at proposal |
| Limits selected | £2m → £5m PL typically +30-50%; £5m → £10m typically +30-50% | Match to highest single contract requirement, not lowest |
| Tool sum insured | Direct linear pricing; specialist diagnostic kit adds more per £ | Review annually; schedule expensive items individually |
| Van overnight location and security | Compound/garage/driveway vs roadside — material premium difference | Declare honestly; declared security must match reality |
| Operating postcode | London, urban areas higher vehicle and tool theft loadings | Declare home/business address accurately |
| Insurance Act compliance discipline | Mature documentation reduces premium 10-20% across programme | Written proposal records, broker confirmation letters, renewal review discipline |
15. Real tradesman claims and how to manage them
Claim — Plumber Public Liability, £38,000 Water Damage Settlement
A sole-trader plumber undertook a routine bathroom replacement in a first-floor flat. While running new pipework above the kitchen ceiling of the flat below (single-pipe construction with limited access), he drilled through what he believed was timber joist and into the existing mains supply pipe. The leak was not discovered until the client returned home eight hours later to find water damage across the kitchen, hallway, and into the ground-floor flat below.
The PL claim engaged: kitchen reinstatement (units, flooring, plaster ceiling — £14,500); contents damage in upstairs flat (£3,200); downstairs flat reinstatement (ceiling collapse from water saturation, £11,800); alternative accommodation costs for both flats (£4,500); freeholder service charge for communal area drying (£1,800); legal costs (£2,200). Total settlement: £38,000.
The plumber's £2m PL policy responded in full. Post-claim renewal: PL premium increased 28%. Insurer required: documented pre-work survey identifying pipe runs; cable/pipe detector use evidenced; client written confirmation of access route. The plumber implemented these and the following renewal saw premium return to a 8% loading over baseline.
The lesson: routine plumber PL claims are dominated by water damage from drilled-through pipes, leaking joints, and overflow from disconnected systems. The £2m limit was adequate here; on a higher-value property or a multi-flat block, £5m would have been the safer floor. Pre-work survey documentation is now standard insurer expectation and materially defends claim value at renewal.
Claim — Roofer Work at Height EL, £215,000 + HSE Prosecution
A small roofing firm (sole director plus three operatives) undertook re-roofing work on a two-storey domestic property. A worker fell approximately 4 metres from the roof edge while moving battens because edge protection had not been erected — the firm had assessed it as "low risk" given the duration of the work, despite the height being well within Work at Height Regulations 2005 scope. The worker sustained a fractured pelvis, fractured wrist, and concussion requiring 4 months off work and ongoing physiotherapy.
HSE attended within 24 hours and opened an investigation. The investigation identified: no documented site-specific risk assessment for work at height; edge protection equipment was on site but had not been deployed; the worker had not received documented work at height training; the firm's general policy documentation pre-dated the current operations.
The firm's £10m EL responded. EL settlement: £215,000 (medical costs, lost earnings, ongoing care, general damages). EL defence costs: £28,000. The HSE prosecution proceeded separately under Section 33 of the Health and Safety at Work Act 1974 (breach of Regulations 4 and 6 of the Work at Height Regulations 2005). Result: firm fined £45,000 plus £8,200 costs; sole director received an 8-month suspended prison sentence under Section 37 of HSAW. Legal Expenses cover responded to defence costs of £62,000 across both the criminal prosecution and director defence.
Post-claim renewal: EL premium increased 65%; PL increased 40%; Legal Expenses doubled. Insurer required: documented site-specific risk assessments per job; work at height training records per operative; edge protection deployment records; periodic site visits documented. The firm implemented these and at renewal +18 months premium had returned to a 35% loading over baseline.
The lesson: work at height is the dominant HSE prosecution category for UK trades. The combined EL claim + HSE prosecution + director defence exposure can exceed £300k from a single incident. Adequate EL limit (£10m as standard), Legal Expenses with HSE scope, and documented operational compliance are the three elements that need to be in place before the incident — not after.
Claim — Tool Theft "Peel and Steal" Van Attack, £12,400
A sole-trader carpenter parked his van overnight on the driveway of his suburban semi-detached house. He had declared "driveway with security lighting" on his tools cover. At approximately 3:15am on a Tuesday, the van was attacked by two intruders who used a hydraulic spreader to force the rear doors open in approximately 90 seconds — a textbook "peel and steal" attack. They removed his entire kit: cordless drill platform with 6 tools and 4 batteries (£1,800); circular saw and table saw (£1,400); domino joiner (£950); router table and routers (£1,200); SDS hammer drill (£480); various hand tools (£1,200); diagnostic and measuring kit (£800); job-specific timber and ironmongery (£600); planer-thicknesser stored in van (£3,200); van damage including doors, hinges, frame (£2,400 separately under vehicle policy).
The claim engaged: tool cover for £12,400 (sum insured was £15,000); single-item limit applied to two items above £1,000 each requiring schedule scrutiny. The vehicle damage of £2,400 was claimed separately under the commercial vehicle policy. Total recoverable: £14,800 after £250 excess on tools and £350 excess on vehicle. Replacement cost at 2026 retail prices: £17,200 (some items had become more expensive since the sum insured was set), creating a £2,400 out-of-pocket gap.
Post-claim renewal: tools premium increased 35%. Insurer required: additional security on van (Sold Secure Diamond locks, immobiliser tracking, dash cam, motion-activated CCTV at home); tool sum insured increased to £18,000 with annual review; specialist diagnostic kit scheduled individually. The carpenter lost 11 working days during replacement procurement.
The lesson: the £99 million UK tool theft figure becomes personal at this scale. Annual sum insured review is essential — the 2020 sum insured undervalues 2026 replacement cost by 20-25% on most kit. Forced-entry conditions are routinely scrutinised at claim; ensure overnight location declarations match reality. The cover responded but the under-insurance gap was material and the operational lost-days impact was substantial. Many tradesmen invest in additional van security after their first major theft; doing so before the claim is materially cheaper.
Claims Management Steps
How to respond to a tradesman insurance incident or HSE engagement — the steps below are critical given that tradesman incidents routinely engage multiple policies (PL, EL, Tools, Vehicle, Legal Expenses, PI) and may also trigger criminal investigation:
- Make the site safe and protect persons first. Standard response. If serious injury has occurred, medical response takes priority over administrative steps. Call 999 for serious incidents.
- Report under RIDDOR if required within statutory timeframes. RIDDOR 2013 requires reportable injuries within 10 days; fatal and major injuries within hours via the HSE online portal. Non-reporting is itself a criminal offence.
- Notify your insurer immediately for any potential claim. Tradesman incidents often engage multiple policies. Single notification triggers coordinated response. Threshold is "may give rise to a claim" — much lower than "formal claim received".
- Preserve all documentation rigorously. Risk assessments, method statements, training records, photographs, tool receipts, vehicle records, client communications, contract terms, sub-contractor agreements. The documentation pack is the defence across all coverage layers.
- Do not admit liability or fault. Provide factual information about what happened. Do not accept fault, apologise in writing, or commit to remedial work that could be interpreted as admission. Insurance Act 2015 cooperation duties don't extend to self-incrimination.
- Manage HSE engagement carefully. If HSE attend or notify, engage your Legal Expenses insurer immediately. Cooperate factually with inspectors but do not provide written statements without legal representation. Regulatory investigation can become criminal prosecution.
- Report theft to police and obtain crime reference number. Tool and vehicle theft claims universally require a police crime reference number. Report within 24 hours; preserve any CCTV; provide receipts and serial numbers for stolen items where available.
- Conduct root cause analysis and document remedial action. Identify underlying cause and implement remedial action. Insurers reviewing renewal will ask what's changed since claim; regulators will require evidence of remedial action.

Glossary of tradesman insurance terms
- Public Liability (PL)
- Insurance covering third-party injury and property damage claims arising from your work or your presence on site. Typically £2m–£10m for tradesmen depending on trade and contract requirements.
- Employers' Liability (EL)
- Insurance covering employee, apprentice, and labour-only subcontractor injury and disease claims. Legally required under the Employers' Liability (Compulsory Insurance) Act 1969 from the moment of first hire. Minimum £5m by law; £10m is the standard market limit.
- Professional Indemnity (PI)
- Insurance covering claims arising from professional services including design, specification, advice, and certification. Required for trades issuing electrical certificates, Gas Safe commissioning, Part P certificates, renewables system designs, and similar.
- Contract Works / Contractors All Risks (CAR)
- Insurance covering damage to the works being carried out — fire, flood, theft, vandalism, accidental damage during construction. Typically required by JCT contracts and most main contractor sub-packages.
- Tools and Equipment Cover
- Insurance covering theft, accidental damage, and fire to hand tools and equipment. Subject to overnight location conditions, forced-entry conditions, single-item limits, and sum-insured discipline.
- Goods in Transit
- Insurance covering tools and materials while being transported in a vehicle. Often part of the commercial vehicle policy rather than the tools policy; misalignment between the two creates cover gaps.
- Work at Height Regulations 2005
- UK statutory framework requiring all work at height to be properly planned, supervised, and carried out safely. Dominant HSE prosecution category for UK trades. Breach is a criminal offence under the Health and Safety at Work Act 1974.
- Section 37 HSAW 1974
- The section of the Health and Safety at Work etc. Act 1974 allowing prosecution of directors and senior managers personally where the offence was committed with their consent, connivance, or neglect. Includes possibility of imprisonment up to 2 years.
- RIDDOR
- Reporting of Injuries, Diseases and Dangerous Occurrences Regulations 2013. UK regulations requiring reporting of certain workplace injuries, diseases, and dangerous occurrences to HSE within statutory timeframes. Non-reporting is itself a criminal offence.
- Building Safety Act 2022 (BSA)
- UK statute reforming building safety regulation following the Grenfell tragedy. Introduces three Gateways for higher-risk buildings, competence requirements, and "golden thread" documentation. 2026 is the first year Gateway 3 applications become routine.
- Higher-Risk Building (HRB)
- Building defined under the Building Safety Act as at least 18 metres or 7 storeys high with at least two residential units. Subject to the full Gateway regime and Building Safety Regulator oversight.
- Hot Works
- Welding, brazing, blow-lamp soldering, hot cutting, and similar activities involving open flame or temperatures sufficient to ignite combustibles. Typically requires specific declaration on PL policies; non-disclosure is a common cover failure.
- HAVS (Hand-Arm Vibration Syndrome)
- Occupational condition caused by prolonged exposure to vibrating tools (drills, breakers, sanders). Long-tail EL claim category — symptoms develop over years and claims surface long after exposure.
- Insurance Act 2015 — Fair Presentation
- UK insurance law requiring policyholders to make a "fair presentation of the risk" at proposal and renewal — proactively disclosing every material fact the insurer would want to know. Non-disclosure allows the insurer to avoid the policy, reduce claims, or impose retroactive terms.
- "Peel and Steal"
- Tool theft method where van doors are forced open with brute force tools (typically hydraulic spreaders or sledgehammers) rather than picked or bypassed electronically. The dominant van break-in pattern in 2025-2026.
- ELTO (Employers' Liability Tracing Office)
- UK industry body maintaining records of Employers' Liability policies to help injured workers trace insurers years or decades after employment. Critical for long-tail occupational disease claims.
- HSE Sentencing Guidelines
- UK Sentencing Council guidelines for health and safety offences. Fines scale with company turnover and culpability — micro-companies (under £2m turnover) can face £50k–£450k fines for serious offences even where no injury actually occurred.
Frequently asked questions
Tradesman liability insurance is a packaged commercial insurance programme covering the core liability and asset risks of UK trade businesses. The constituent covers typically include: Public Liability for third-party injury and property damage; Employers' Liability for staff injury (legally required if you have employees); Tools and equipment cover; Contract Works for damage to ongoing projects; Commercial vehicle insurance; Professional Indemnity for design and certification work; Personal Accident for sole-trader income protection; Legal Expenses for HSE and contract disputes. Most tradesmen buy these as a coordinated package from a specialist insurer.
Employers' Liability is legally required from the moment you have any employees — including apprentices, part-time workers, labour-only subcontractors, and casual workers — under the Employers' Liability (Compulsory Insurance) Act 1969. The fine for non-compliance is £2,500 per day. Public Liability is not legally required but is contractually required by virtually every commercial client, local authority, social housing landlord, main contractor, and trade body. Commercial vehicle insurance is legally required for any vehicle used on UK roads under the Road Traffic Act 1988. Personal motor insurance with "business use" extension typically does NOT cover trade vans or vehicles used for genuine trade purposes.
Indicative 2026 annual premiums: sole trader low-risk (decorator, gardener, handyman) £150–£400; sole trader mid-risk (carpenter, plasterer, tiler) £250–£650; sole trader plumber/heating £350–£850; sole trader electrician with PI £450–£950; sole trader roofer/scaffolder £600–£1,800; small firm 2-5 staff £1,400–£3,500; small firm certification-based £2,000–£4,500; mid-size firm 6-15 staff £3,500–£9,000+. Pricing depends on trade type, turnover, employee count, work at height declaration, limits selected, tool sum insured, claims history, and broker placement type. Specialist placement consistently beats price-comparison routes on cover scope and claim certainty.
Public Liability covers claims from third parties — typically clients, members of the public, or property owners — for injury or property damage from your work. Employers' Liability covers claims from your own employees, apprentices, labour-only subcontractors, and similar workers for injury or disease arising from their work. They are completely separate policies covering completely separate categories of claimant. EL is legally required if you have any staff; PL is not legally required but is contractually unavoidable. A typical small trade business needs both — PL responds when a customer trips over your tools; EL responds when your apprentice falls off a ladder.
The cover limit should match the highest single contract requirement you have or expect to have — not the smallest. £1m is minimal and only suitable for very low-risk solo trade. £2m is the standard floor for most small domestic trade work. £5m is required by most commercial work, local authority contracts, and larger residential building work. £10m is required by roofing, demolition, scaffolding, larger main contractor work, social housing panels, and higher-risk building work. The premium uplift from £2m to £5m is typically £40–£120; from £5m to £10m typically £80–£250. Always carry the higher limit — turning down a £20,000 contract because your £2m PL doesn't meet the £5m specification is materially worse than the £80 premium uplift.
Yes, where scoped correctly, but the conditions matter enormously. Most policies require tools to be removed from vans overnight or kept only in vans locked in a secure compound, garage, or driveway with declared security — claims for overnight theft from a van parked on a public road are routinely declined. Most policies also require evidence of forced entry — opportunistic theft from an unlocked vehicle may be excluded. Single-item limits typically cap individual tool claims at £500–£1,000 even where overall sum insured is higher. With UK tool theft hitting £99 million annually in 2025 and "peel and steal" attacks now dominant, sum insured review and security upgrade are both essential.
Yes, if any of your work involves design, specification, advice, or certification. This includes electricians issuing EICRs or Part P certificates; gas engineers issuing Gas Safe commissioning certificates; renewables installers designing solar/heat pump/EV charging systems; heating engineers sizing and specifying systems; builders providing structural specifications; PAS 2035 retrofit work. PI covers financial loss claims arising from errors in this professional element — claims that PL doesn't typically respond to. Limits typically £100k–£250k for small trades with limited design element; £500k–£1m for substantial certification work. Run-off cover is essential — PI claims can surface 2-10 years after the work. See our professional indemnity insurance product page.
HSE prosecution of small trades and sole traders is a real and rising risk — particularly under the Work at Height Regulations 2005. Recent 2025-2026 cases include sole traders fined £2,125-£45,000+, suspended prison sentences for serious failures, and personal director prosecutions under Section 37 of HSAW 1974. Defence costs typically £50,000-£250,000 for contested prosecutions; the fines themselves are uninsurable under UK public policy but Legal Expenses insurance with HSE investigation scope responds to defence costs. D&O cover supports personal director defence costs. The single biggest defence to HSE prosecution is documented operational compliance before the incident — risk assessments, method statements, training records, and PPE evidence.
Insurance non-disclosure under the Insurance Act 2015. The pattern: tradesman buys a "general builder" or generic trade package, undertakes specialist work (work at height, hot works, gas, asbestos, labour-only subbies) that wasn't specifically declared at proposal, and at claim stage the insurer points to the proposal documentation and reduces or declines the claim. This isn't fraud — it's the normal operation of UK insurance law requiring "fair presentation of the risk". The fix at proposal stage is minimal cost; the retrospective cost is potentially every uninsured claim. Get written broker confirmation that all your actual work types are within declared scope.
The biggest premium reduction lever is accurate, complete declaration combined with documented operational discipline. Maintain trade body registration (NICEIC, Gas Safe, PCA, NAPIT, FENSA) — reduces premium 5-15%. Document site-specific risk assessments and method statements — reduces premium 10-20% on better placements. Maintain 5+ year claim-free history — material NCB discount. Upgrade van security to Sold Secure Diamond locks and tracking — material tool premium reduction. Match limits to actual contract requirements rather than over-insuring. Use a specialist broker rather than direct or comparison-site routes — typically wider scope at similar or lower price. Annual payment vs monthly typically 5-8% saving. Stack the levers; don't choose between them. Avoid the trap of buying the cheapest generic package — see our cheap tradesman insurance guide for the principles of cost-efficient placement without false economies.
Almost certainly not. Personal motor insurance — even with "business use class 1" or "class 2" extensions — typically covers limited business use scenarios (driving to a single place of work, occasional client visits in a car) but does NOT cover: driving a van for trade use; carrying tools and materials between sites; using a vehicle for genuine multi-site trade work. Trade vehicles require commercial vehicle insurance with goods-in-transit cover for the tools and materials carried. Driving on personal cover for trade use means the policy doesn't respond at claim stage and the driver is committing a criminal offence under the Road Traffic Act 1988. See our commercial vehicle insurance cost guide for trade vehicle pricing.
Look for brokers with specific trade experience evidenced by: published guides on trade-specific risks, work at height, tools cover, and Contract Works; willingness to discuss specific exposures (HSE prosecution, Building Safety Act, Insurance Act 2015 non-disclosure) in detail; access to Lloyd's market and specialist MGAs rather than just mainstream commercial markets; FCA authorisation and documented track record. Avoid brokers offering "tradesman package" without discussing your specific trade work types; brokers who can only quote one or two markets; brokers who don't ask about work at height, hot works, gas work, or labour-only subbies at proposal. Miller & Partner specialise in trade placements — see our contractors combined insurance product page and broader tradesman insights hub.







Instagram
LinkedIn