


Composite Panel Surveys & Cutting Loadings | UK Guide
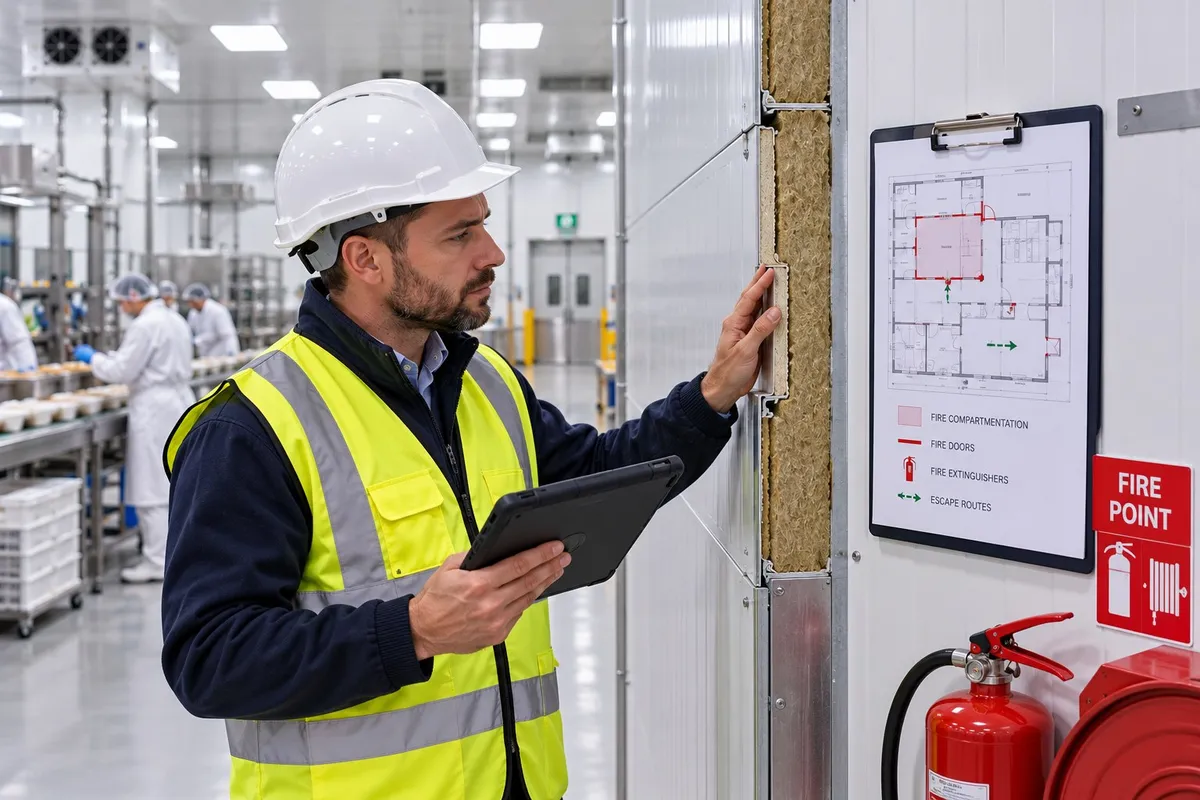
A composite panel survey identifies exactly which panels are in your building, where they are and what condition they are in. Insurers rate unknown panels as the worst type, usually expanded polystyrene (EPS), so a building with no evidence is often loaded, restricted or declined. A good survey, backed by a panel management plan, replaces assumptions with facts. Where it proves PIR, mineral wool or certified panels, the loading usually falls or disappears; where it confirms EPS, it still lets underwriters price what is really there.
Key facts at a glance
- Unknown is treated as worst case. Without evidence, insurers assume combustible cores.
- A survey maps every panel type. Walls, roofs, internal partitions and cold rooms are recorded separately.
- Certification matters. LPS 1181 or FM approved panels are rated very differently from uncertified cores.
- A management plan proves control. Inspection, repair and fire-stopping routines reassure underwriters.
- Evidence goes to market. The survey is only valuable if it is presented properly to the right insurers.
What is a composite panel survey?
Composite panels look the same from the outside. A steel-faced panel with a polystyrene core and one with a mineral wool core can sit side by side on the same building, and only the core decides how a fire behaves. That is why insurers ask for a proportion of combustible panels as a percentage of the building, and why an owner who simply does not know is so often quoted on the worst assumption. Our composite panel building insurance guide explains how underwriters rate the building as a whole; the survey is the document that feeds that rating.
What does a good panel survey include?
| Survey element | What it records | Why insurers care |
|---|---|---|
| Panel schedule | Each wall, roof and internal area with core type and thickness | Gives the percentage of combustible panel by area |
| Marked-up drawings | Panel types colour-coded on the site plan | Shows whether EPS sits next to heat sources or compartment walls |
| Method of identification | Labels, delivery notes, cut edges or core samples | Separates proven facts from assumptions |
| Certification | LPS 1181, FM approval or other test evidence where found | Certified panels are rated far more favourably |
| Condition | Damage, exposed cores, failed seals and unsealed penetrations | Damaged panels let fire reach the core quickly |
| Photographs | Dated images of each panel type and defect | Lets an underwriter verify the findings without a visit |
If you are unsure what the difference between core types actually means for cover, our guide to EPS v PIR v mineral wool panels sets out how each is treated.
What is a panel management plan?
The survey tells an insurer what is there; the plan tells them how it is controlled. A practical plan usually covers:
- a copy of the panel schedule and drawings, kept up to date after any building work;
- a routine inspection of panels, with damage reported and repaired promptly using like-for-like or better materials;
- fire-stopping of every cable, pipe and duct penetration with a fire-rated product;
- a hot work permit system for any welding, cutting or grinding near panels;
- a clear zone keeping pallets, waste and combustible stock away from panel walls, inside and out;
- protection of panels near forklift routes, cookers, fryers, ovens and battery charging.
In food production and cold storage, where internal partitions are common, the plan carries particular weight. Our food factory & cold store panel insurance guide covers the extra conditions those sites usually face.
How do you use a survey to cut loadings?
- Commission the survey early. Allow time before renewal for the report, any core sampling and any repairs it recommends.
- Fix the easy defects. Sealing penetrations and repairing damaged panels often costs little and removes adverse findings from the report.
- Write or refresh the management plan. Align it with the survey so the two documents tell the same story.
- Gather supporting evidence. Fire alarm certificates, electrical inspection reports, thermographic surveys and housekeeping records all help.
- Go to the right markets. A specialist broker presents the pack to insurers with an appetite for panel buildings, rather than mainstream insurers that decline on sight.
- Ask for the loading to be reviewed. Where an existing insurer applied a loading on an unknown-panels basis, the new evidence gives grounds to request a re-rate.
If your current insurer has already declined, non-renewed or heavily loaded the building, start with our guide to composite panel building insurance after a refusal, which explains what each response means.
Is a panel survey worth the cost?
Survey fees vary with the size and complexity of the site, the number of panel types and whether core sampling is needed. Measured against an annual premium loading, a declined renewal or a forced move to a restricted policy, a survey usually pays for itself quickly. It also has value beyond insurance: it supports your fire risk assessment, informs maintenance planning and helps if you later sell or let the building. Landlords should note that tenants increasingly ask for panel evidence before signing a lease, and that lenders may ask the same question. For the wider picture on how we assess non-standard buildings, see the Insurability Framework.
Frequently asked questions
A competent surveyor with fire and building fabric experience: often a specialist panel surveyor, a fire risk consultant or, on larger sites, the insurer's own risk engineer. What matters is that they record how each panel type was identified, not just their opinion of it.
Sometimes. Where there are no labels, delivery records or visible cut edges, a small core sample may be taken. This must be done by a competent person, logged on the drawings and resealed with a fire-rated product, so the inspection does not create a new weak point.
No, but it removes the main reason for many loadings: uncertainty. If the survey proves PIR, mineral wool or certified panels, the risk is usually re-rated. If it confirms EPS, it still allows the insurer to price the actual risk rather than an assumed worst case.
Re-survey after any building work, extension, change of use or panel repair, and refresh the panel management plan record annually. Insurers increasingly ask when the survey was carried out and whether the drawings still reflect the building.
A short written plan showing where each panel type sits, how damage is inspected and repaired, how penetrations are fire-stopped, and how heat sources and combustible storage are kept away from panel walls. Many insurers make one a condition of cover.
Often, yes. Specialist and Lloyd's markets may offer cover on terms that assume unknown panels, with a commitment to review once the survey is delivered. We can place interim cover and then go back to market with the evidence.
Related guides from Miller & Partner








Instagram
LinkedIn