


Golf Simulator Venue Insurance UK | Bays, Bars & Tech Cover
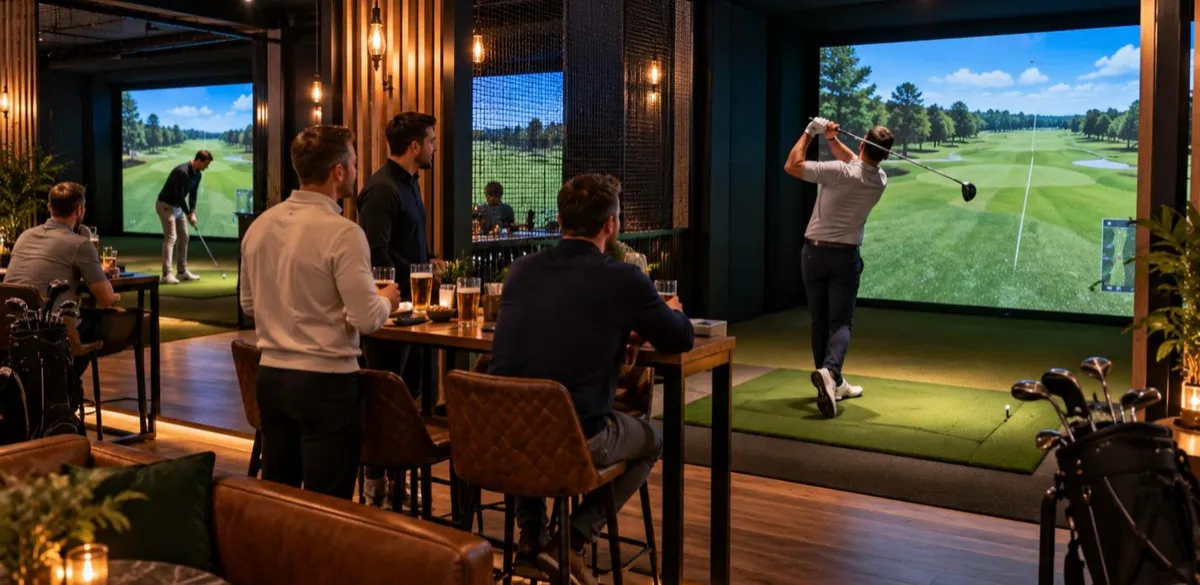
Golf simulator venue insurance covers indoor golf bars, simulator studios and driving-range style venues where customers hit real balls into screens. The core covers are public liability for injuries to customers and spectators, contents cover for the simulator bays, launch monitors, projectors and screens, and business interruption if a fire, flood or equipment failure closes the venue. Most venues also need employers' liability, cover for stock and licensed bar income, equipment breakdown for the technology, and cyber cover for online booking systems. Insurers focus on bay design and spacing, ball deflection protection, how alcohol is managed around active bays, staff supervision and whether you hire out clubs. Many standard pub and leisure policies have no category for simulator venues, so cover usually comes from specialist leisure markets.
Key facts at a glance
- Ricochet injuries are the main liability risk. Insurers want to see bay spacing, side netting and impact screens that stop balls deflecting.
- The tech is expensive and fragile. Launch monitors, projectors and screens need contents and breakdown cover at full replacement value.
- Alcohol changes the risk. Insurers ask how you control drinking around active bays.
- Business interruption matters. A fire or a failed system can close bays for weeks while parts are shipped.
- Most standard policies don't fit. Many pub and leisure insurers have no rating category for simulator venues.
What insurance does a golf simulator venue need?
A golf simulator venue usually needs public liability, employers' liability, contents and equipment cover, equipment breakdown, business interruption and, if you serve alcohol, cover for stock and licensed income.
| Cover | What it protects | Watch out for |
|---|---|---|
| Public liability | Injuries to customers, spectators and passers-by | Exclusions for participants or alcohol-related incidents |
| Employers' liability | Injuries to staff and coaches | A legal requirement once you employ anyone |
| Contents and equipment | Simulators, launch monitors, projectors, screens, clubs | Undervaluing imported technology |
| Equipment breakdown | Electrical and mechanical failure of the tech | Often excluded from basic contents cover |
| Business interruption | Lost income if the venue or bays can't trade | An indemnity period too short for overseas parts |
| Cyber | Booking system outages and customer data breaches | Online payments and stored card details |
Simulator venues are one of several formats covered in our guide to competitive socialising venue insurance.
Why simulator venues are hard to place
Golf simulator venues combine a sports activity, expensive technology and a bar. Standard pub insurers don't rate the activity, and standard sports insurers don't like the alcohol.
The risk that worries underwriters most is the ball. A full swing in an enclosed bay can send a ball back off the frame, the floor or the edge of the screen. If a customer waiting their turn or a member of staff carrying drinks is hit, the claim lands on your public liability. That's why insurers look closely at bay construction rather than just your turnover.
Some liability wordings exclude injuries to people taking part in the activity. For a simulator venue, almost every customer is a participant, so that exclusion would gut the cover. Make sure the policy is written for activity venues.
What do insurers ask about a golf simulator venue?
Insurers ask about the bays, the equipment, the bar, staffing and the people using the venue.
- Bays. Number of bays, width and depth, side netting, impact screen type and floor surface
- Equipment. Simulator brand, launch monitors, projectors and the total replacement value
- Bar and food. Whether you hold a premises licence, alcohol turnover and how you manage drinking near bays
- Supervision. Staff on the floor, safety briefings and rules for children
- Extras. Coaching, club fitting, corporate events and league nights
- Premises. Construction, fire protection, security and whether you lease or own
- History. Any claims in the last five years
Coaching, club fitting and leagues
If you offer coaching or club fitting, you may need professional indemnity or treatment risks added, depending on who delivers it.
A PGA professional working for you is usually covered under your liability policy as an employee. A self-employed coach renting a bay should have their own cover, and you should check it. Corporate events and leagues are normally fine under your venue cover, but tell your insurer if you host large events or bring in outside caterers.
How much does golf simulator venue insurance cost?
Premiums depend on the number of bays, turnover, the value of the equipment, how much of your income comes from alcohol and your claims history.
A small two or three bay studio without a bar is a very different risk from a multi-bay venue with a late licence. The biggest levers you control are good bay design, written supervision rules and a clear alcohol policy. If you've been turned down before, see our guide to business insurance with a claims history.
How do you set up golf simulator venue insurance?
- List your bays and equipment. With replacement values.
- Describe the bar. Licence, hours and alcohol turnover.
- Document your safety rules. Spacing, netting and supervision.
- Check your lease. Landlords often set insurance requirements.
- Choose an indemnity period. Allow for overseas parts and refits.
- Come to a specialist. So the activity is properly declared.
Frequently asked questions
Usually not. Many pub policies don't recognise the activity, and some exclude injuries to participants.
No. If customers pay to use it, you need a commercial policy with public liability.
That's a public liability claim. Insurers expect netting and bay spacing designed to stop it.
Only if you add equipment breakdown cover. Standard contents cover is for damage, not failure.
Usually your venue policy covers them, but tell your insurer about large events or outside caterers.
Yes. New venues are insured on projections and the experience of the people running them.
Related guides from Miller & Partner

Miller & Partner Limited (FRN 1029698) is an Appointed Representative of Gauntlet Risk Management Ltd (FRN 308081), which is authorised and regulated by the Financial Conduct Authority. Miller & Partner Limited is registered in England and Wales (company number 16206282) and trades from Vivian House, Roman Bridge Close, Mumbles, Swansea SA3 5BG. This article is general information, not a personal recommendation or an offer of cover. Cover is subject to insurer acceptance and the full terms, conditions and exclusions of the policy issued.







Instagram
LinkedIn