

FS Register FRN 1029698

Five Star Rated on Google

13+ years specialist broking experience

General information, not advice. Written for general guidance and drawing on external sources as well as our own experience. It isn't a personal recommendation and doesn't take account of your circumstances — full disclaimer and sources.

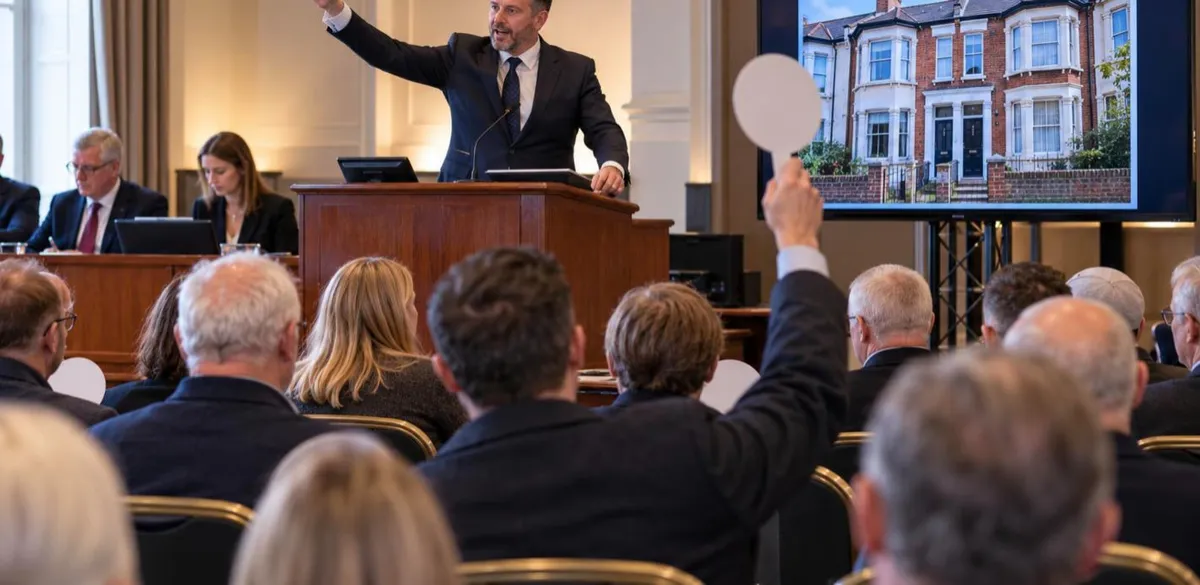
Bidder raising a paddle at a property auction as the auctioneer takes bids for a terraced house shown on screen

Auction Property Insurance UK | Cover From the Hammer

October 26, 2026

Published: 26 October 2026 | Reading time: 7 minutes | Category: Property | Author: John Miller, Miller & Partner

Last reviewed by John Miller, Director & Principal Broker — 26 October 2026
FS Register FRN 102969813+ years specialist commercial brokingLloyd's & specialist MGA market accessIndependent UK broker

Auction property insurance protects buyers of property bought at auction from the moment they become responsible for it. At most UK auctions, contracts are exchanged when the hammer falls, and under the common auction conditions the risk usually passes to the buyer at that point, even though completion may be 28 days or more away. That means you need buildings cover and property owners' liability straight away. Many auction lots are empty, in poor condition or non-standard, so standard home and landlord policies often decline them. Bridging lenders usually require cover with their interest noted before completion. Insurers look at the property's condition, occupancy, construction, location and your plans, such as letting, refurbishment or resale.

Bought or bidding at auction? We'll arrange cover from the fall of the hammer, including empty and non-standard lots.

Key facts at a glance

  1. Risk usually passes at the hammer. Under common auction conditions, the buyer normally bears the risk from exchange, not completion.
  2. Lenders need cover first. Bridging lenders usually require insurance with their interest noted before they complete.
  3. Many lots are empty. Unoccupied property needs specialist cover with security and inspection conditions.
  4. Non-standard lots are common. Auctions attract properties with subsidence, knotweed, RAAC or unusual construction.
  5. Your plans shape the cover. Letting, refurbishing and reselling each need a different policy.

When do you need to insure an auction property?

At most UK auctions you exchange contracts when the hammer falls. Under the common auction conditions the risk usually passes to you at that point, so you need cover from the day of the auction, not completion.

Always check the special conditions in the legal pack, because some sellers keep the property insured until completion and others do not. If the building burns down between exchange and completion, you could still have to complete the purchase.

Arrange cover before the auction

Speak to us before you bid so cover can start the moment you win. Waiting until after the auction can leave a gap.

What insurance does an auction property need?

Most auction properties need buildings cover, property owners' liability and, if empty, unoccupied property cover. If you plan works, you also need contract works and existing structures cover.

SituationCover needed
Empty and awaiting worksUnoccupied property cover and owners' liability
Tenanted at purchaseLandlord buildings cover, liability and loss of rent
Under refurbishmentContract works plus existing structures cover
Derelict or unsafeDerelict building cover with liability
Commercial or mixed-useCommercial property cover

Non-standard auction lots

Auction lots often have issues that put off mainstream insurers and mortgage lenders. Specialist markets can usually cover them.

Common problems include past subsidence, Japanese knotweed, RAAC, non-standard construction, thatched roofs and listed status. See our guides to subsidence history property insurance, Japanese knotweed property insurance and RAAC property insurance.

What do insurers ask about an auction property?

Insurers ask about the property, its condition and occupancy, the auction and completion dates, your lender and your plans.

  • Property. Address, type, construction and age
  • Condition. Survey findings, photos and known defects
  • Occupancy. Empty, tenanted or partly occupied
  • Dates. Auction, exchange and completion
  • Finance. Lender name and requirements
  • Plans. Let, refurbish, convert or resell

How do you insure an auction property?

  1. Read the legal pack. Check when risk passes.
  2. Contact us before the auction. So cover is ready.
  3. Share the details. Condition, occupancy and plans.
  4. Confirm your lender. So their interest is noted.
  5. Start cover at the hammer. Not at completion.
  6. Update cover as plans change. For works, letting or resale.

Frequently asked questions

Usually from the fall of the hammer, because contracts exchange then and the risk normally passes to the buyer.

Sometimes, but not always. Check the special conditions in the legal pack.

Yes. Lenders usually require buildings cover with their interest noted before completion.

Yes, with unoccupied property cover, which has security and inspection conditions.

Yes. Specialist insurers cover non-standard properties that mainstream insurers decline.

Yes. Once works start you need contract works and existing structures cover.

Related guides from Miller & Partner

Need auction property cover quickly? Tell us about the lot and your plans, and we'll come back with terms.

John Miller, Director and Principal Broker at Miller & Partner
Written and reviewed by John Miller Director & Principal Broker, Miller & Partner Over 13 years of specialist commercial insurance experience, formerly with Brown & Brown and AXA. Places hard-to-place property and works risks through Lloyd's syndicates and specialist MGAs, including unoccupied, derelict and non-standard buildings under refurbishment or conversion.
Our regulatory status

Miller & Partner Limited (FRN 1029698) is an Appointed Representative of Gauntlet Risk Management Ltd (FRN 308081), which is authorised and regulated by the Financial Conduct Authority. Miller & Partner Limited is registered in England and Wales (company number 16206282) and trades from Vivian House, Roman Bridge Close, Mumbles, Swansea SA3 5BG. This article is general information, not a personal recommendation or an offer of cover. Cover is subject to insurer acceptance and the full terms, conditions and exclusions of the policy issued.


Back to Blog
About this article General information, not advice. Published for general guidance and drawing on external sources as well as our own experience. It is not a personal recommendation, a quotation, or an offer of cover, and it doesn't take account of your circumstances. Read more + Close −

Where the information comes from

Our articles are compiled from a range of sources: regulators and public bodies such as the FCA, the Civil Aviation Authority, the Health and Safety Executive and Companies House; government publications and legislation; industry and trade bodies; insurer and market documentation; and published research and news reporting. Not everything stated originates from Miller & Partner. Where information comes from a third party we believe it to be accurate at the date of publication, but we haven't independently verified every external source and we don't warrant its accuracy or completeness. Where a point matters to a decision you're making, go to the original source and check it.

Figures, examples and case studies

Premium ranges, cost figures, limits and worked examples are illustrative only. They are not quotations, not offers of cover, and no cover is provided or implied on the basis of them. What you're actually charged depends on underwriting, and what you're actually covered for depends on the policy wording issued to you. Where an article includes a claim example, scenario or case study, it is illustrative unless we say otherwise — such examples are typically composites written to show how a policy section responds, and they don't describe an identifiable client, claim or settlement.

Interactive tools

Any calculators, cover checkers, risk assessors or similar tools on our site produce general guidance from the small number of answers you give them. They can't see your business, and their output is not a personal recommendation, an assessment of your actual risk, or a quotation.

Rules and market conditions change

Law, regulation, tax treatment, insurer appetite and policy wordings all change, sometimes at short notice. Content is accurate to the best of our knowledge on the date shown on the article and we don't undertake to update it as things move. An article you're reading some time after publication may be out of date.

Third parties and external links

References to insurers, underwriters, trade bodies, software, training providers or other organisations are for information only. They don't imply endorsement, recommendation, partnership or affiliation in either direction unless stated. We're not responsible for the content of external websites we link to.

Not legal, tax or accounting advice

Nothing here is legal, tax, accounting or regulatory advice. Where an article discusses statutory duties, contract terms or compliance obligations, take advice from an appropriately qualified professional on your own position before acting.

How we write these

We use AI tools in researching and drafting our published content. Every article is reviewed and signed off by a named, accountable person at Miller & Partner before it is published, and responsibility for what appears here rests with us.

Our regulatory status

Miller & Partner Ltd is an Appointed Representative of Gauntlet Risk Management Ltd, which is authorised and regulated by the Financial Conduct Authority (FRN 308081). Miller & Partner Ltd is entered on the FCA Register under reference 1029698. Registered in England and Wales, company number 16206282. Registered office: Vivian House, Roman Bridge Close, Mumbles, Swansea, SA3 5BG.

Spotted something wrong?

We'd rather know. Email [email protected] or call 01792 001350 and we'll review and correct it.

For advice on your own insurance arrangements, speak to us directly — that's when we can take your circumstances into account and give you a recommendation.

Ready to protect your business?
Get expert advice and a tailored commercial insurance quote today.

✔ Independent broker
✔ Access to leading UK insurers
✔ Fast turnaround

[Request a quote]

[[email protected]]
[Call 01792 001350]

Exclusive Offer

Free Insurance Review
& Zero Broker Fee

Let us review your current insurance and see if we can improve your cover while reducing the cost.

✓
Free no-obligation insurance review tailored to your business
£
Zero broker fee on all new policies
⚡
Fast response from a real insurance specialist

You're in 🎉

Thanks for requesting your free review. We'll be in touch shortly.

🔒 No spam, ever. Your details are safe with us.

We're an Appointed Representative of Gauntlet Risk Management Ltd, which is authorised and regulated by the FCA. You can check our entry on the FCA Register.

MEET THE Director

Hey, I'm John!

I started Miller & Partner with the aim to bring back personable, approachable broking to UK businesses who were tired of large corporate brokers and feeling like they were just another number.

I have built this brokerage up with no pushy sales techniques or big business tactics, just honest, approachable and professional relationships with my clients.

Over 13 years experience in business insurance

Client first approach

5* rated broker on Google

Office: Vivian House, Roman Bridge Close, Mumbles, Swansea, SA3 5BG

Miller & Partner Ltd is an Appointed Representative of Gauntlet Risk Management Ltd, which is authorised and regulated by the Financial Conduct Authority (FRN 308081). Miller & Partner Ltd is entered on the Financial Services Register under firm reference number 1029698. You may check this on the Financial Services Register by visiting the FCA website at https://www.fca.org.uk/firms/financial-services-register or by contacting the FCA on 0800 111 6768. Miller & Partner Ltd is registered in England & Wales, company number 16206282. Registered office: 20 Vivian House, Roman Bridge Close, Swansea, SA3 5BG.




