


Crematorium Insurance UK | Cremators, Liability & BI
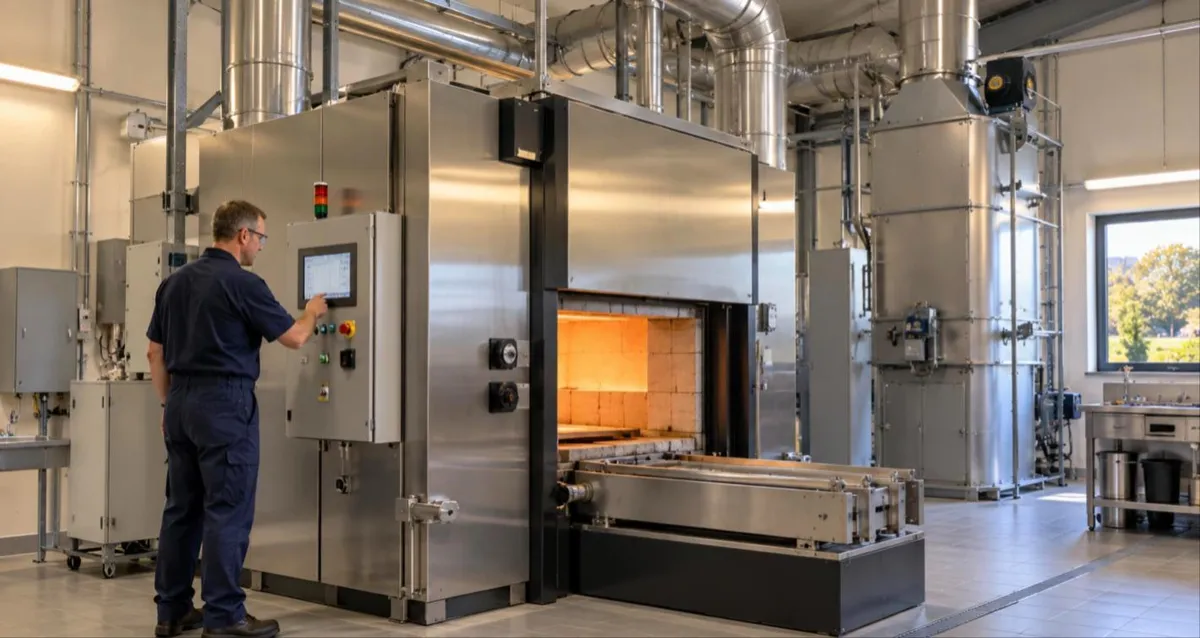
Crematorium insurance covers independent and private crematoria, and the companies building new ones, against damage, breakdown, loss of income and liability. The core covers are property cover for the crematorium, chapel and grounds, machinery breakdown for cremators, mercury abatement and heat recovery equipment, and business interruption because a cremator failure or fire can stop services. Public and employers' liability are essential, and crematoria need professional or legal liability for errors in identification, records or the handling of remains, which can lead to serious claims from families. Projects under construction need contract works and delay in start-up cover. Insurers look at cremator make, age and servicing, abatement equipment, fire separation, the environmental permit, staff training and chain of custody procedures.
Key facts at a glance
- Cremators drive the risk. Breakdown of cremators, abatement and heat recovery equipment can stop services and needs specialist cover.
- Income loss can be long. Major cremator repairs or rebuilding after fire can take months, so the indemnity period needs care.
- Errors carry serious consequences. Mistakes with identification or remains lead to distress claims and reputational damage.
- Permits are part of underwriting. Insurers check the environmental permit and abatement arrangements.
- New builds need cover from day one. Contract works and delay in start-up protect projects before the crematorium opens.
What insurance does a crematorium need?
Most crematoria need buildings and contents cover, machinery breakdown, business interruption, public and employers' liability, professional or legal liability for errors, and engineering inspection for pressure systems and lifts. New crematoria need contract works and delay in start-up cover.
| Cover | What it protects |
|---|---|
| Buildings and contents | Crematorium, chapel, offices, memorial gardens and contents |
| Machinery breakdown | Cremators, mercury abatement, heat recovery and controls |
| Business interruption | Lost income while services are disrupted |
| Public and employers' liability | Injury to mourners, visitors and staff |
| Professional and legal liability | Claims over errors with identification, records or remains |
| Engineering inspection | Statutory inspection of pressure systems and lifting equipment |
Crematoria work hand in hand with funeral directors. See our guide to funeral director insurance.
Why breakdown and business interruption matter most
A crematorium earns its income from a small number of cremators. If one fails, capacity drops immediately, and a fire or major failure can stop services altogether. Breakdown and business interruption together protect the income that pays for the site.
Refractory relines, burner failures and abatement faults all take time to repair. Check how long specialist engineers and parts take to arrive, and set the indemnity period to match. Include the cost of diverting services to another crematorium while yours is out of action.
New crematoria face delay risk too. If damage during construction pushes back opening, delay in start-up cover replaces the income you expected to earn. Our guide to delay in start-up insurance explains how it works.
Claims over identification and remains are the most sensitive a crematorium can face. Make sure your policy includes professional or legal liability, not just public liability.
What do insurers look for?
Insurers look at cremator make, age and servicing, abatement and heat recovery, fire separation, the environmental permit, staff training, chain of custody procedures, visitor numbers and the grounds.
- Cremators. Number, make, age and service contracts
- Abatement. Mercury abatement and heat recovery systems
- Fire. Separation between cremator hall and public areas
- Permit. Environmental permit and compliance history
- Procedures. Identification, records and chain of custody
- Grounds. Memorial gardens, trees, paths and parking
Some crematoria also run burial areas. Our guide to natural burial ground insurance covers the extra liability that brings.
How do you set up crematorium insurance?
- Describe the site. Buildings, cremators, chapel and grounds.
- Value your assets. Rebuild cost and replacement cost of cremators and abatement.
- Confirm your income. Annual cremations and fees.
- Gather your procedures. Servicing, permit, training and chain of custody.
- Set the indemnity period. Allow for major repairs and rebuilding.
- Review each year. Update cover after new cremators or works.
Pet crematoria
Pet crematoria face many of the same breakdown and fire risks on a smaller scale, with collection rounds and veterinary contracts added.
See our guide to pet crematorium insurance.
Frequently asked questions
Buildings and contents, machinery breakdown for cremators and abatement, business interruption, public and employers' liability, and professional or legal liability for errors.
Yes, under machinery breakdown cover for sudden failure, provided the cremator has been serviced.
Long enough to repair or replace cremators and rebuild after fire. Many crematoria choose 12 to 24 months.
Only under professional or legal liability cover. Check that your policy includes it.
Contract works for the build and delay in start-up for lost income if opening is delayed by insured damage.
Yes. We present the claim and the improvements made to specialist property and engineering markets.
Related guides from Miller & Partner

Miller & Partner Limited (FRN 1029698) is an Appointed Representative of Gauntlet Risk Management Ltd (FRN 308081), which is authorised and regulated by the Financial Conduct Authority. Miller & Partner Limited is registered in England and Wales (company number 16206282) and trades from Vivian House, Roman Bridge Close, Mumbles, Swansea SA3 5BG. This article is general information, not a personal recommendation or an offer of cover. Cover is subject to insurer acceptance and the full terms, conditions and exclusions of the policy issued.







Instagram
LinkedIn