


Boat Repair and Storage Yard Insurance UK | Specialist Cover
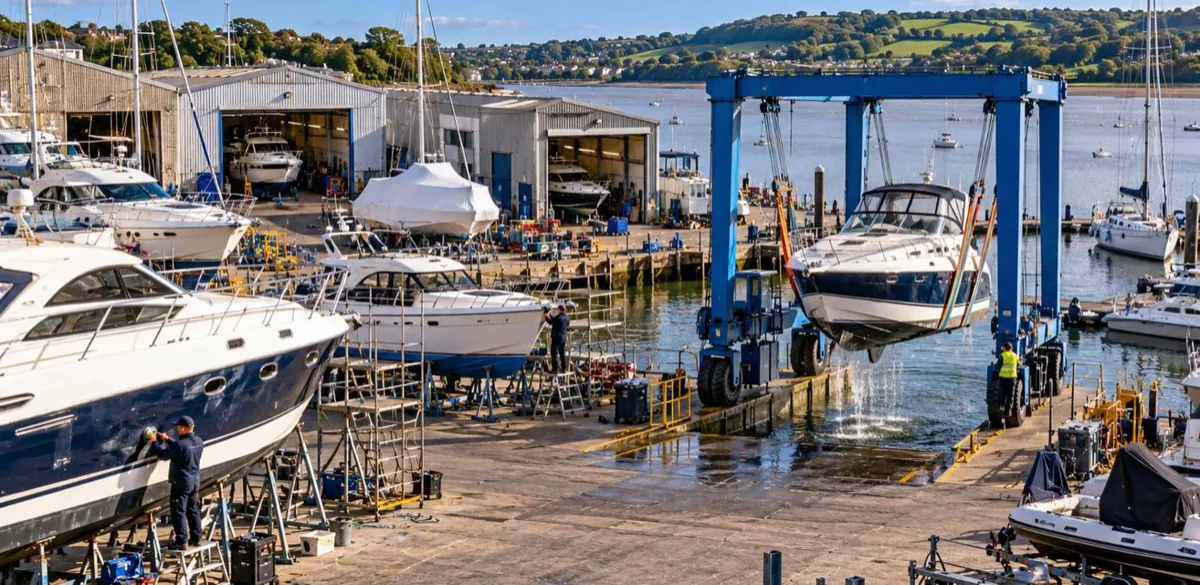
Boat repair and storage yard insurance covers businesses that lift, store, repair and refit other people's boats. The most important cover is liability for customers' vessels in your care, custody and control, because a fall from a cradle, a fire in the shed or storm damage in the yard can affect dozens of boats at once. Alongside that you need public and employers' liability, cover for your own buildings, cranes, hoists and travel lifts, and business interruption. Many yards also need ship repairer's liability, which is written for marine trades and responds to damage caused by faulty work. Insurers look closely at lifting procedures, fire separation in sheds, hot work controls and flood exposure, so presenting those properly is what decides the terms.
Key facts at a glance
- Customers' boats are the biggest exposure. A yard can hold millions of pounds of other people's vessels, so the limit for property in your care needs to reflect the peak, not the average.
- Faulty work needs its own cover. Ship repairer's liability responds to damage caused by your repairs, which general public liability may exclude.
- Lifting is a frequent cause of claims. Travel lifts, cranes and cradles need regular inspection and trained operators, and insurers will ask for records.
- Sheds concentrate fire risk. GRP repairs, resins, solvents and hot work in enclosed sheds make fire separation and hot work permits essential.
- Flood and storm matter. Waterside yards face tidal flooding and wind damage to boats ashore, which affects both price and excesses.
What insurance does a boat repair and storage yard need?
Most yards need cover for customers' boats in their care, ship repairer's liability for faulty work, public and employers' liability, cover for their own buildings, lifting equipment and tools, and business interruption. Yards with marina berths or moorings may also need marina operator's liability.
| Cover | What it protects |
|---|---|
| Care, custody and control | Customers' boats while stored, lifted, moved or worked on in your yard |
| Ship repairer's liability | Damage caused by your repairs, refits and engineering work |
| Public liability | Injury to customers and visitors, and damage to third-party property |
| Employers' liability | Injury to your staff; a legal requirement once you employ people |
| Buildings and contents | Sheds, workshops, offices, stock and spares |
| Lifting equipment | Travel lifts, cranes, hoists and trailers, plus breakdown and statutory inspection |
| Business interruption | Lost income if fire or flood closes the yard |
If you also run berths and pontoons, our main marina and boatyard insurance page explains how marina operator's cover fits in.
How much cover do you need for customers' boats?
Set the limit for customers' boats in your care at the highest total value you hold at any one time, usually during winter lay-up. A single fire or storm can damage many boats together, so the per-event limit matters as much as the per-boat limit.
Winter storage is when the exposure peaks. Boats are packed closely in the yard or inside sheds, and a fire or a storm can reach many of them at once. Work out the value of the boats you hold at the busiest point of the year, and check whether your policy limits apply per boat, per event or in total.
Your storage terms with customers also matter. Clear contracts that set out what you are and are not responsible for, and that ask owners to keep their own hull insurance, reduce disputes after a loss.
Many boat owners assume the yard is responsible for their boat while it is ashore. If your own policy limit is too low, the shortfall can fall on your business.
What do insurers look for at a boat yard?
Insurers look at lifting procedures and inspection records, fire controls in sheds, hot work permits, storage of resins and fuels, boat spacing and chocking, security, and the yard's flood and storm exposure. Good records on these points widen the market and improve terms.
- Lifting. Inspection records for travel lifts and cranes, and operator training
- Fire. Separation between sheds, detection, extinguishers and housekeeping around GRP work
- Hot work. A permit system and fire watch after welding, grinding or cutting
- Hazardous materials. Safe storage of resins, solvents, paints and fuel
- Storage. Spacing, cradles and props checked for storm conditions
- Security. Gates, CCTV and controls on who can access boats
- Flood. Tidal and river flood exposure and the yard's flood plan
Specialist work such as underwater inspection brings its own risks. If you use or employ divers, see our guide to commercial diving insurance.
How do you set up boat yard insurance?
- Value your peak exposure. Total value of customers' boats at the busiest time of year.
- List your services. Storage, lifting, repairs, refits, engineering, rigging and brokerage.
- Gather records. Lifting inspections, hot work permits, fire risk assessment and claims history.
- Check customer terms. Make sure your storage and repair contracts match your insurance.
- Value your own property. Buildings, lifting equipment, tools and stock at replacement cost.
- Review before each lay-up season. Update limits if the number or value of boats has grown.
Refused cover or facing a big increase?
Yards are often declined or heavily loaded after a fire, a lifting accident or a flood. Presenting the improvements made since, and approaching specialist marine underwriters, usually reopens the market.
We use the Insurability Framework™ to identify what is driving the decision and how to present your yard. For broader marine businesses, see our guide to marine trade insurance, and if you have had a recent fire, our guide to business insurance after a fire claim.
Frequently asked questions
Usually, if the damage is caused by your negligence while the boat is in your care. Your storage contract and your care, custody and control cover decide how that responsibility works in practice.
It is liability cover written for marine trades. It responds when your repair or refit work causes damage to the boat or to others, which general public liability may not cover.
Use the highest total value of boats you hold at one time, normally during winter lay-up, and check whether the limit applies per boat or per event.
Only if you have engineering or plant breakdown cover. Statutory inspection of lifting equipment is a separate requirement that insurers can also arrange.
It can, but waterside yards often face flood exclusions or higher excesses. Your flood plan and history will affect the terms.
Yes. We present the cause of the fire and the improvements made since to specialist marine insurers that will look at the detail.
Related guides from Miller & Partner

Miller & Partner Limited (FRN 1029698) is an Appointed Representative of Gauntlet Risk Management Ltd (FRN 308081), which is authorised and regulated by the Financial Conduct Authority. Miller & Partner Limited is registered in England and Wales (company number 16206282) and trades from Vivian House, Roman Bridge Close, Mumbles, Swansea SA3 5BG. This article is general information, not a personal recommendation or an offer of cover. Cover is subject to insurer acceptance and the full terms, conditions and exclusions of the policy issued.







Instagram
LinkedIn