

FS Register FRN 1029698

Five Star Rated on Google

13+ years specialist broking experience

General information, not advice. Written for general guidance and drawing on external sources as well as our own experience. It isn't a personal recommendation and doesn't take account of your circumstances — full disclaimer and sources.

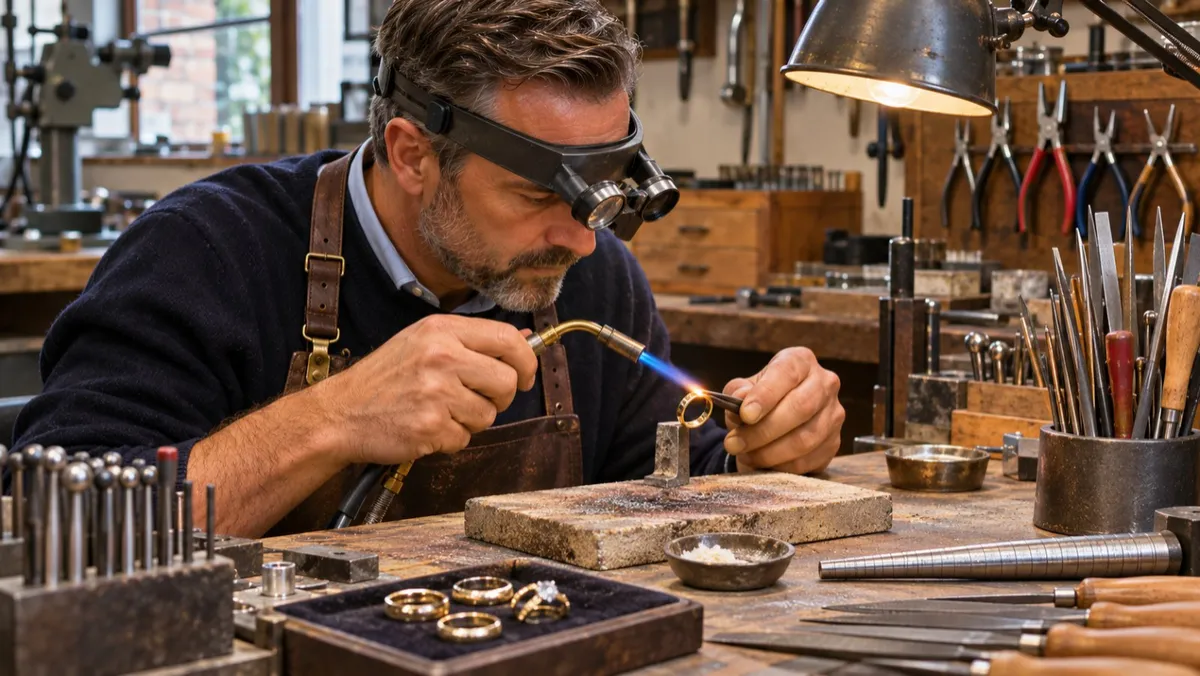
Goldsmith soldering a gold ring with a small torch at a jeweller's workbench, illustrating jewellery workshop insurance

Jewellery Workshop & Goldsmith Insurance UK

November 04, 2026

Published: 4 November 2026 | Reading time: 7 minutes | Category: Shops | Author: John Miller, Miller & Partner

Last reviewed by John Miller, Director & Principal Broker — 4 November 2026
FS Register FRN 1029698 13+ years specialist commercial broking Lloyd's & specialist MGA market access Independent UK broker

Jewellery workshops and goldsmiths in the UK need a combination of block cover for precious metal, stones and customers' goods, and liability cover for the work they do. The block section protects your own metal, scrap and findings, and customers' rings, watches and heirlooms left for repair, on an all-risks basis in the safe, at the bench and in transit, including send-outs to the assay office. Liability cover protects you if a customer's piece is damaged during stone-setting or engraving, if a product you made causes injury, or if an employee is hurt. Underwriters also want to know about hot work, gas torches, pickling and plating chemicals, casting and polishing machinery, how you secure stock overnight, and how much work is out with outworkers at any one time. Cover is usually placed with Lloyd's syndicates and specialist MGAs that understand bench jewellery, because standard shop or tradesman policies rarely deal properly with customers' goods.

Need jewellery workshop insurance?

Cover for customers' goods, metal stock, assay send-outs and workshop liability. Get a quote online or speak to a specialist broker directly.

Key facts at a glance

  1. Customers' goods are your biggest exposure. As bailee, you are responsible for pieces left for repair.
  2. Scrap counts as stock. Filings, lemel and offcuts hold real value and must be insured and secured.
  3. Hot work is rated. Torches, kilns and gas cylinders affect fire terms and conditions.
  4. Assay send-outs are transit. Pieces travelling to and from the assay office need transit cover.
  5. Workmanship damage needs care. Check how the policy treats damage while setting or engraving.

How are customers' goods left for repair insured?

When a customer leaves a ring, chain or watch with you, you hold it as a bailee and are responsible for taking reasonable care of it. A customers' goods section of the block policy covers theft, loss and damage while those items are in your workshop, safe or in transit.

Many claims arise from repair items, partly because sentimental pieces are often worth more than their owners realise. Issue a numbered repair receipt for every job, record a description and photograph, and agree a value in writing on higher-value pieces. Your terms should say what happens if work is uncollected. Keep customers' goods locked away overnight in the same graded safe as your stock, and count them within the safe limit.

Is precious metal stock and scrap covered?

Yes, under the block or stock section. Gold, silver and platinum bar, sheet and wire, findings, loose stones and scrap such as filings, lemel and sweeps are all insurable stock. Underwriters want accurate stock records and expect scrap to be secured overnight like finished goods.

Scrap is easy to overlook. A well-run workshop collects bench sweepings, polishing dust and filings for refining, and that material can build up to a meaningful sum. Insure it, store it securely and record when it is sent to a refiner.

What do underwriters ask about hot work and chemicals?

Underwriters ask how you use gas torches, kilns and casting equipment, how gas cylinders are stored, and what chemicals you hold for pickling, plating and cleaning. Good housekeeping, fire extinguishers, safe cylinder storage and a no-hot-work-unattended rule can make a real difference to terms.
HazardTypical underwriter questionGood practice
Torches and gasType of gas, cylinder storage, shut-offCylinders secured, valves closed at day end
Kilns and castingLocation, clearances, unattended runningNon-combustible surround, never left unattended
Pickling and platingChemicals held, ventilation, storageLabelled, locked store, extraction where needed
Polishing machineryDust extraction, guarding, trainingExtraction fitted, guards in place, staff trained

Machinery such as polishing motors, rolling mills and laser welders can be covered for damage and, if needed, breakdown. Employers' liability is a legal requirement if you employ staff, and underwriters will ask about training and protective equipment.

Are items sent for hallmarking covered in transit?

They can be. Under the Hallmarking Act 1973, many precious metal articles must be hallmarked by an assay office before they are described as gold, silver, platinum or palladium. Sending work to and from the assay office is a transit risk, so check the per-consignment limit and the carrier your policy allows.

The same applies to send-outs to stone setters, engravers, platers and refiners. Your policy should cover your stock and customers' goods at those trade premises and in transit, with limits that reflect how much is out at any one time.

What if a stone breaks during setting or engraving goes wrong?

Damage caused while working on an item is one of the most common disputes in workshop insurance. Some policies cover accidental damage during work, often with a higher excess, while others exclude damage caused by the process itself. Check the wording before you rely on it.

Stones with inclusions, older settings and fragile materials such as emerald and opal carry more risk. Practical steps help:

  1. Inspect the piece with the customer and note existing damage on the receipt.
  2. Explain the risk to fragile stones and get written acceptance before work starts.
  3. Photograph the item before and after work.
  4. Confirm with your broker how the policy responds to damage while working.

Do goldsmiths need public and products liability?

Yes. Public liability covers injury or property damage to visitors and customers, while products liability covers harm caused by items you have made or sold, such as an allergic reaction or a clasp failure. Both are normally arranged alongside employers' liability in the same policy.

If you also sell from a shop, read our retail jeweller insurance guide. The jewellers block insurance pillar explains the stock cover in more depth, and our bullion dealer insurance guide covers holding larger quantities of metal.

Frequently asked questions

Often yes, if stock is modest, there is a graded safe and an alarm, and hot work is managed safely. Home insurance will not cover the business.

Usually while they remain in your care, but set a clear collection policy in your terms so they do not sit indefinitely.

Tools and equipment are normally covered under contents or business equipment, with separate cover if you take them off site.

Yes. Tell your broker, because students using torches and tools changes the liability risk.

It can be, under a section for stock at trade premises and in transit. Check the limit and the refiner's own responsibility.

Specialist markets can still help. See our guide to insurance after a robbery or theft claim.

Related guides from Miller & Partner

Running a jewellery workshop? We place workshop and block cover with specialist and Lloyd's markets.

John Miller, Director and Principal Broker at Miller & Partner, specialist broker for jewellery workshop insurance
Written and reviewed by John Miller Director & Principal Broker, Miller & Partner Over 13 years of specialist commercial insurance experience, formerly with Brown & Brown and AXA. Places hard-to-place commercial risks through Lloyd's syndicates and specialist MGAs, including jewellers and goldsmiths.
Our regulatory status Miller & Partner Limited (FRN 1029698) is an Appointed Representative of Gauntlet Risk Management Ltd (FRN 308081), which is authorised and regulated by the Financial Conduct Authority. Miller & Partner Limited is registered in England and Wales (company number 16206282) and trades from Vivian House, Roman Bridge Close, Mumbles, Swansea SA3 5BG. This article is general information, not a personal recommendation or an offer of cover. Cover is subject to insurer acceptance and the full terms, conditions and exclusions of the policy issued. For hallmarking requirements, check with an assay office.
Back to Blog
About this article General information, not advice. Published for general guidance and drawing on external sources as well as our own experience. It is not a personal recommendation, a quotation, or an offer of cover, and it doesn't take account of your circumstances. Read more + Close −

Where the information comes from

Our articles are compiled from a range of sources: regulators and public bodies such as the FCA, the Civil Aviation Authority, the Health and Safety Executive and Companies House; government publications and legislation; industry and trade bodies; insurer and market documentation; and published research and news reporting. Not everything stated originates from Miller & Partner. Where information comes from a third party we believe it to be accurate at the date of publication, but we haven't independently verified every external source and we don't warrant its accuracy or completeness. Where a point matters to a decision you're making, go to the original source and check it.

Figures, examples and case studies

Premium ranges, cost figures, limits and worked examples are illustrative only. They are not quotations, not offers of cover, and no cover is provided or implied on the basis of them. What you're actually charged depends on underwriting, and what you're actually covered for depends on the policy wording issued to you. Where an article includes a claim example, scenario or case study, it is illustrative unless we say otherwise — such examples are typically composites written to show how a policy section responds, and they don't describe an identifiable client, claim or settlement.

Interactive tools

Any calculators, cover checkers, risk assessors or similar tools on our site produce general guidance from the small number of answers you give them. They can't see your business, and their output is not a personal recommendation, an assessment of your actual risk, or a quotation.

Rules and market conditions change

Law, regulation, tax treatment, insurer appetite and policy wordings all change, sometimes at short notice. Content is accurate to the best of our knowledge on the date shown on the article and we don't undertake to update it as things move. An article you're reading some time after publication may be out of date.

Third parties and external links

References to insurers, underwriters, trade bodies, software, training providers or other organisations are for information only. They don't imply endorsement, recommendation, partnership or affiliation in either direction unless stated. We're not responsible for the content of external websites we link to.

Not legal, tax or accounting advice

Nothing here is legal, tax, accounting or regulatory advice. Where an article discusses statutory duties, contract terms or compliance obligations, take advice from an appropriately qualified professional on your own position before acting.

How we write these

We use AI tools in researching and drafting our published content. Every article is reviewed and signed off by a named, accountable person at Miller & Partner before it is published, and responsibility for what appears here rests with us.

Our regulatory status

Miller & Partner Ltd is an Appointed Representative of Gauntlet Risk Management Ltd, which is authorised and regulated by the Financial Conduct Authority (FRN 308081). Miller & Partner Ltd is entered on the FCA Register under reference 1029698. Registered in England and Wales, company number 16206282. Registered office: Vivian House, Roman Bridge Close, Mumbles, Swansea, SA3 5BG.

Spotted something wrong?

We'd rather know. Email [email protected] or call 01792 001350 and we'll review and correct it.

For advice on your own insurance arrangements, speak to us directly — that's when we can take your circumstances into account and give you a recommendation.

Ready to protect your business?
Get expert advice and a tailored commercial insurance quote today.

✔ Independent broker
✔ Access to leading UK insurers
✔ Fast turnaround

[Request a quote]

[[email protected]]
[Call 01792 001350]

Exclusive Offer

Free Insurance Review
& Zero Broker Fee

Let us review your current insurance and see if we can improve your cover while reducing the cost.

✓
Free no-obligation insurance review tailored to your business
£
Zero broker fee on all new policies
⚡
Fast response from a real insurance specialist

You're in 🎉

Thanks for requesting your free review. We'll be in touch shortly.

🔒 No spam, ever. Your details are safe with us.

We're an Appointed Representative of Gauntlet Risk Management Ltd, which is authorised and regulated by the FCA. You can check our entry on the FCA Register.

MEET THE Director

Hey, I'm John!

I started Miller & Partner with the aim to bring back personable, approachable broking to UK businesses who were tired of large corporate brokers and feeling like they were just another number.

I have built this brokerage up with no pushy sales techniques or big business tactics, just honest, approachable and professional relationships with my clients.

Over 13 years experience in business insurance

Client first approach

5* rated broker on Google

Office: Vivian House, Roman Bridge Close, Mumbles, Swansea, SA3 5BG

Miller & Partner Ltd is an Appointed Representative of Gauntlet Risk Management Ltd, which is authorised and regulated by the Financial Conduct Authority (FRN 308081). Miller & Partner Ltd is entered on the Financial Services Register under firm reference number 1029698. You may check this on the Financial Services Register by visiting the FCA website at https://www.fca.org.uk/firms/financial-services-register or by contacting the FCA on 0800 111 6768. Miller & Partner Ltd is registered in England & Wales, company number 16206282. Registered office: 20 Vivian House, Roman Bridge Close, Swansea, SA3 5BG.





