FS Register FRN 1029698
Five Star Rated on Google
13+ years specialist broking experience
EdTech Insurance — PI, Cyber and Liability for Education Technology Companies
Insurance for education technology businesses: language learning apps, online tutoring platforms, software for schools and colleges, and e-learning content providers. We arrange the technology PI, cyber and safeguarding cover that schools, trusts and investors ask for, including for start-ups with no trading history.
Quick answer · Updated 20 November 2026
What insurance does an edtech company need?
Most edtech companies need technology professional indemnity to cover claims that their platform failed, lost data or didn't do what was promised, and cyber insurance because they hold personal data, often about children. Many also need intellectual property cover for course content, public liability for in-person work, and, if users can interact with tutors or each other, abuse and safeguarding liability. Venture-backed companies usually add directors' and officers' cover. Schools, multi-academy trusts and local authorities will often set minimum limits in their contracts.
Why edtech businesses need specialist cover
Education technology sits between software, publishing and education. A language app is a software product and a content business. A tutoring marketplace is a technology platform and, in practice, a provider of contact between adults and children. Software for schools processes some of the most sensitive data any business holds. Standard business insurance doesn't cover any of that properly.
The gaps we see most often are:
- No technology PI. A general business policy won't respond if a school says your platform failed during exams or lost coursework.
- Cyber cover that excludes children's data or has limits too low for the number of records held.
- No abuse or safeguarding cover for platforms that connect tutors with children.
- IP infringement excluded, even though content is the product.
- Contract limits not met. Procurement frameworks often require PI, cyber and public liability at set levels.
EdTech businesses we insure
Language learning apps
Apps and platforms teaching languages to adults and children.
Online tutoring platforms
Marketplaces and agencies connecting tutors with students online and in person.
School software companies
MIS, safeguarding, assessment, homework and parent communication tools.
E-learning content providers
Course creators, LMS providers and corporate training businesses.
SaaS and software
Wider software and platform businesses.
AI tools
AI consultancies and businesses building AI into learning products.
What cover does an edtech company need?
| Cover | What it protects | Watch out for |
|---|---|---|
| Technology PI | Claims that your platform or service failed, caused loss or didn't meet the contract | Contractual liability exclusions and limits below contract requirements |
| Cyber | Data breach response, ransomware, business interruption and regulatory investigations | Limits too low for the number of records, and minimum security conditions |
| Intellectual property | Claims that your content or software infringes someone else's rights | IP exclusions in standard PI wordings |
| Abuse and safeguarding | Allegations of abuse involving tutors or users | Often excluded from liability policies entirely |
| Public liability | Injury or damage during in-person sessions, events or school visits | Work in schools not declared |
| Directors' and officers' | Claims against directors, including from investors | Investor-backed companies needing higher limits |
Children's data and the law
If children are likely to use your service, the ICO's Age Appropriate Design Code applies, alongside UK GDPR and the Data Protection Act 2018. Schools will also expect you to support their duties under Keeping Children Safe in Education and to hold appropriate security certifications such as Cyber Essentials. Insurers will ask about all of this, and a well-documented approach to data protection makes cyber cover easier to obtain and cheaper.
How we place edtech risks
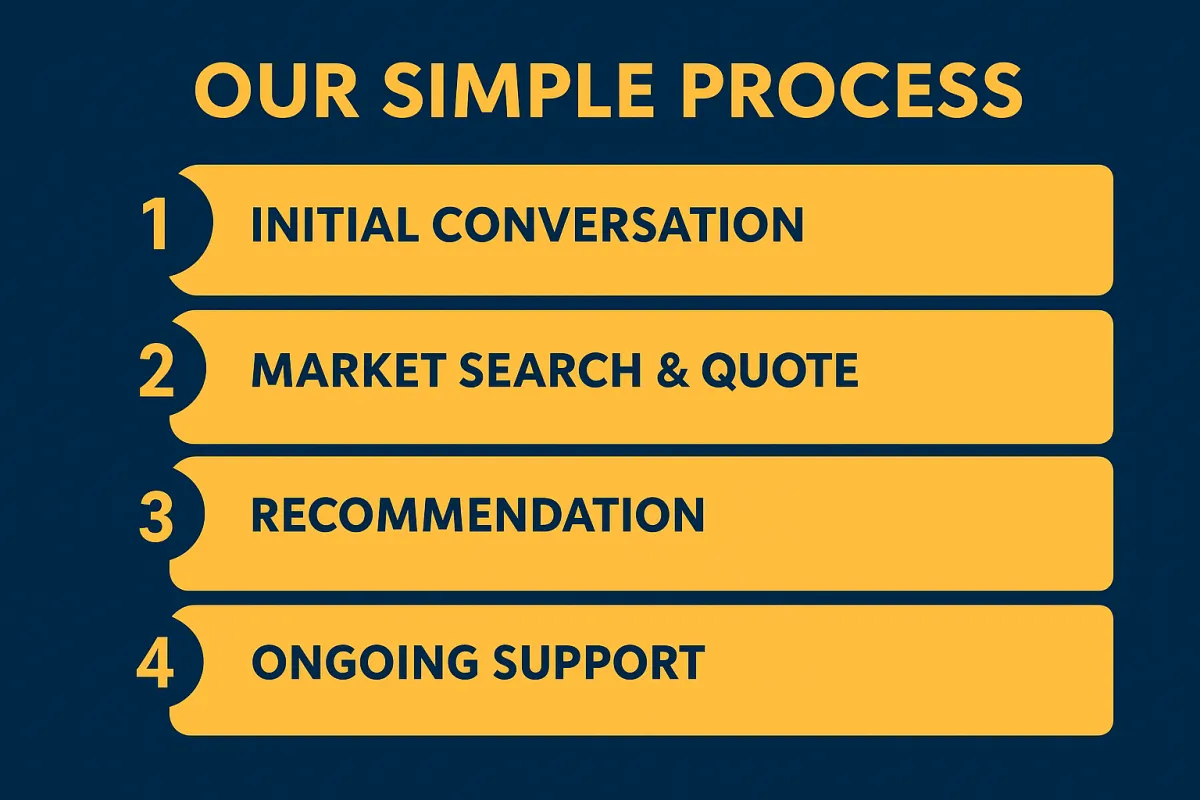
We start with your product and your customers: who uses it, what data it holds, what you promise in your contracts and what your buyers require. From there we arrange a combined technology PI and cyber policy, add safeguarding and D&O where needed, and make sure the limits match the frameworks and contracts you're bidding for. Start-ups and pre-revenue businesses are welcome.
Frequently asked questions
Do edtech start-ups need insurance before launch?
Usually, yes. Schools, trusts and many investors ask for PI and cyber cover before you sign your first contract, and cover can be arranged before you have revenue.
What PI limit do schools require?
It varies, but £1m to £5m is common for technology suppliers to schools, trusts and local authorities. Check the contract or framework.
Does cyber insurance cover children's data?
It can, but insurers will ask how much data you hold and how it is protected. Declare that you process children's data.
Do tutoring platforms need abuse cover?
If tutors interact with children, yes. Abuse and safeguarding liability is often excluded from standard policies and needs to be added specifically.
Can you insure an edtech company using AI?
Yes. Insurers will want to know how AI is used in the product, what data it is trained on and how outputs are checked.
Related guides from Miller & Partner
- AI, SaaS and tech insurance
- SaaS business insurance
- AI consultancy insurance
- Cyber insurance
- Game development business insurance
- Professional indemnity insurance
John was very helpful in an area where other brokers could not find policies that met the needs of my business. Quick responses and always friendly!
I’ve been dealing with John for our specialist crime scene and biohazard cleaning insurance, and the service has been excellent. He took the time to understand the nature of our work and ensured we had the right level of cover in place. Responsive, knowledgeable, and easy to deal with throughout. Would recommend 100%
John M provided excellent support in arranging a policy suited to our needs. Despite our niche requirements, he communicated everything clearly and made the process simple. Highly recommended!
MEET THE Director
Hey, I'm John!
I started Miller & Partner with the aim to bring back personable, approachable broking to UK businesses who were tired of large corporate brokers and feeling like they were just another number.
I have built this brokerage up with no pushy sales techniques or big business tactics, just honest, approachable and professional relationships with my clients.
Over 13 years experience in business insurance
Client first approach
5* rated broker on Google
Office: Vivian House, Roman Bridge Close, Mumbles, Swansea, SA3 5BG
Call 01792 001350
Email: [email protected]
Instagram
LinkedIn