

FS Register FRN 1029698

Five Star Rated on Google

13+ years specialist broking experience

General information, not advice. Written for general guidance and drawing on external sources as well as our own experience. It isn't a personal recommendation and doesn't take account of your circumstances — full disclaimer and sources.

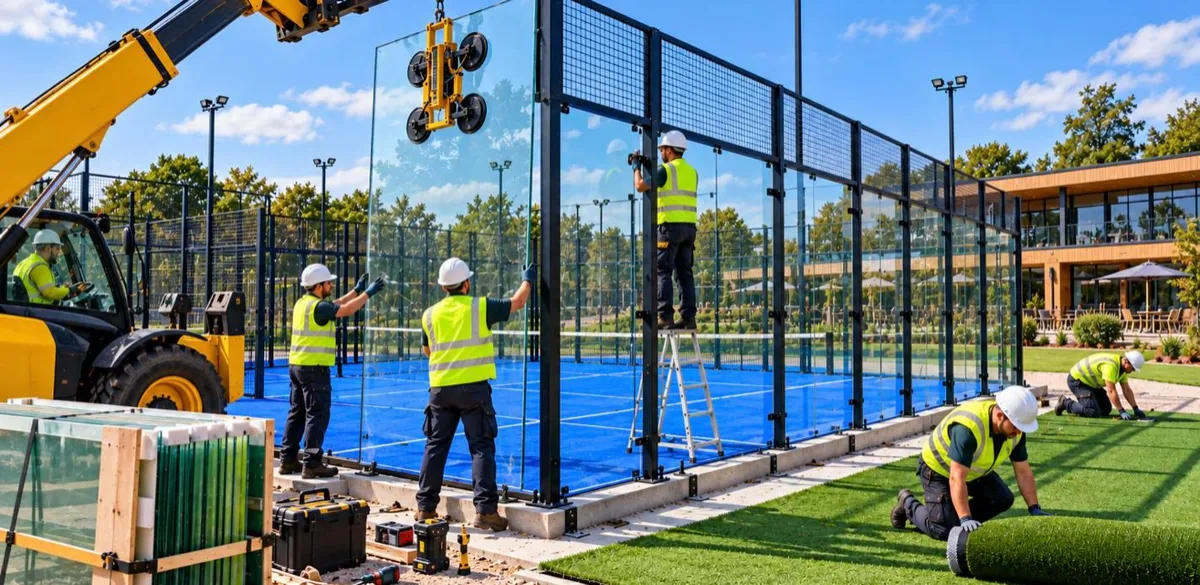
Installers fitting glass panels to a new padel court at a UK club, the work covered by padel court builder insurance

Padel Court Builder & Installer Insurance UK | Specialist Cover

October 25, 2026

Published: 25 October 2026 | Reading time: 6 minutes | Category: Construction | Author: John Miller, Miller & Partner

Last reviewed by John Miller, Director & Principal Broker — 25 October 2026
FS Register FRN 102969813+ years specialist commercial brokingLloyd's & specialist MGA market accessIndependent UK broker

Padel court builder and installer insurance covers contractors who design, supply and install padel courts for clubs, leisure operators, hotels, schools and private owners. The main covers are contractors' all risks for the court while it is being built, public and employers' liability for the work on site, and cover for your tools, plant and lifting equipment. Because courts combine steel frames, toughened glass panels, artificial turf and floodlights, many installers also need product liability for what they supply and professional indemnity if they design the court or its foundations. Clients and main contractors usually ask for set liability limits, often £5 million or £10 million, before work starts. Insurers look at your experience, glass handling, working at height and the size of the contracts you take on.

Building or installing padel courts? We'll arrange contract works, liability and design cover that meets your clients' contract terms.

Key facts at a glance

  1. Contract works cover protects the build. Contractors' all risks covers the court, materials on site and temporary works until handover.
  2. Glass is the critical hazard. Toughened glass panels are heavy and fragile; handling, lifting and breakage are frequent causes of claims and injury.
  3. Product liability follows what you supply. If you supply the frame, glass, turf or lighting, you can be liable if a component fails after handover.
  4. Design brings professional risk. Installers who design foundations, drainage or lighting layouts should consider professional indemnity.
  5. Clients set the limits. Leisure operators and main contractors commonly require £5 million to £10 million of public liability.

What insurance does a padel court installer need?

Most padel court installers need contractors' all risks, public and employers' liability, product liability, tools and plant cover, and professional indemnity if they provide design. Installers who import courts may also need goods in transit and marine cargo cover.

CoverWhat it protects
Contractors' all risksThe court, materials and temporary works during construction
Public liabilityInjury to others or damage to the client's property during the work
Employers' liabilityInjury to your staff; a legal requirement once you employ people
Product liabilityInjury or damage caused by components you supply after handover
Professional indemnityErrors in court design, foundations, drainage or lighting layouts
Tools and plantOwned and hired plant, lifting equipment, tools and vans

Many installers take out a single contractors combined policy that brings the main liability and works covers together.

Why product liability matters for court builders

A padel court is a product as well as a construction project. If a glass panel shatters, a frame weld fails or a floodlight column falls after handover, the claim can come back to the company that supplied and installed it.

Most courts are manufactured abroad and imported. If you are the first UK business to put the product on the market, you may carry the importer's liability as well as your own. Check that your policy covers products supplied and that it applies worldwide if your products are exported.

Keep records of the specification, certificates for the glass and steel, and your installation checks. Good records help defend claims and show insurers that you control the risk.

Don't forget the turf and lighting

Slip injuries on worn turf and failures of lighting columns are common claim types. Make sure your product cover includes every component you supply, not just the frame and glass.

What do insurers look for in a padel court installer?

Insurers look at your experience, contract values, glass handling and lifting methods, working at height, use of subcontractors, the products you import and your contract terms with clients.

  • Experience. Number of courts built and years trading
  • Contracts. Largest contract value, typical clients and any indemnities given
  • Glass and lifting. Lifting plans, trained operators and inspected equipment
  • Height. Work on frames, canopies and lighting columns
  • Subcontractors. Groundworks, electricians and their own insurance
  • Products. Where the courts are made and who the manufacturer is

Foundations and drainage are often subcontracted. If you do that work yourself, our guide to groundworks contractor insurance covers the extra risks.

How do you set up padel court builder insurance?

  1. Describe your work. Design, groundworks, installation, lighting and maintenance.
  2. Estimate turnover. Split between installation, supply only and maintenance.
  3. List your products. Manufacturers, countries of origin and certificates.
  4. Review contracts. Note the liability limits and indemnities your clients require.
  5. Value your kit. Owned and hired plant, lifting gear, tools and vans.
  6. Review as you grow. Update cover when you take on larger or overseas projects.

Refused cover or facing a big increase?

New sports construction firms are sometimes declined because insurers have little claims data on padel. Presenting your experience, products and procedures clearly to specialist construction underwriters usually opens the market.

We use the Insurability Framework™ to show underwriters how your business manages its risks. If you are on the club side rather than the build side, read our guide to padel club insurance.

Frequently asked questions

Yes, if you supply any part of the court. Product liability covers injury or damage caused by components such as glass, frames, turf or lighting after handover.

Most leisure operators and main contractors ask for £5 million, and larger projects often require £10 million.

Only if you have contractors' all risks or the client's works policy covers it. Check the contract to see who is responsible for insuring the works.

If you design the court, its foundations, drainage or lighting layout, professional indemnity protects you against claims for design errors.

Not under a liability policy. You need goods in transit or marine cargo cover for courts shipped from overseas manufacturers.

Yes. We present your experience in construction and sports surfaces to specialist underwriters who will consider newer businesses.

Related guides from Miller & Partner

Want your court building insurance reviewed? Tell us about your projects, your team and your suppliers, and we'll come back with terms.

John Miller, Director and Principal Broker at Miller & Partner
Written and reviewed by John Miller Director & Principal Broker, Miller & Partner Over 13 years of specialist commercial insurance experience, formerly with Brown & Brown and AXA. Places hard-to-place construction and liability risks through Lloyd's syndicates and specialist MGAs, including sports and leisure contractors.
Our regulatory status

Miller & Partner Limited (FRN 1029698) is an Appointed Representative of Gauntlet Risk Management Ltd (FRN 308081), which is authorised and regulated by the Financial Conduct Authority. Miller & Partner Limited is registered in England and Wales (company number 16206282) and trades from Vivian House, Roman Bridge Close, Mumbles, Swansea SA3 5BG. This article is general information, not a personal recommendation or an offer of cover. Cover is subject to insurer acceptance and the full terms, conditions and exclusions of the policy issued.


Back to Blog
About this article General information, not advice. Published for general guidance and drawing on external sources as well as our own experience. It is not a personal recommendation, a quotation, or an offer of cover, and it doesn't take account of your circumstances. Read more + Close −

Where the information comes from

Our articles are compiled from a range of sources: regulators and public bodies such as the FCA, the Civil Aviation Authority, the Health and Safety Executive and Companies House; government publications and legislation; industry and trade bodies; insurer and market documentation; and published research and news reporting. Not everything stated originates from Miller & Partner. Where information comes from a third party we believe it to be accurate at the date of publication, but we haven't independently verified every external source and we don't warrant its accuracy or completeness. Where a point matters to a decision you're making, go to the original source and check it.

Figures, examples and case studies

Premium ranges, cost figures, limits and worked examples are illustrative only. They are not quotations, not offers of cover, and no cover is provided or implied on the basis of them. What you're actually charged depends on underwriting, and what you're actually covered for depends on the policy wording issued to you. Where an article includes a claim example, scenario or case study, it is illustrative unless we say otherwise — such examples are typically composites written to show how a policy section responds, and they don't describe an identifiable client, claim or settlement.

Interactive tools

Any calculators, cover checkers, risk assessors or similar tools on our site produce general guidance from the small number of answers you give them. They can't see your business, and their output is not a personal recommendation, an assessment of your actual risk, or a quotation.

Rules and market conditions change

Law, regulation, tax treatment, insurer appetite and policy wordings all change, sometimes at short notice. Content is accurate to the best of our knowledge on the date shown on the article and we don't undertake to update it as things move. An article you're reading some time after publication may be out of date.

Third parties and external links

References to insurers, underwriters, trade bodies, software, training providers or other organisations are for information only. They don't imply endorsement, recommendation, partnership or affiliation in either direction unless stated. We're not responsible for the content of external websites we link to.

Not legal, tax or accounting advice

Nothing here is legal, tax, accounting or regulatory advice. Where an article discusses statutory duties, contract terms or compliance obligations, take advice from an appropriately qualified professional on your own position before acting.

How we write these

We use AI tools in researching and drafting our published content. Every article is reviewed and signed off by a named, accountable person at Miller & Partner before it is published, and responsibility for what appears here rests with us.

Our regulatory status

Miller & Partner Ltd is an Appointed Representative of Gauntlet Risk Management Ltd, which is authorised and regulated by the Financial Conduct Authority (FRN 308081). Miller & Partner Ltd is entered on the FCA Register under reference 1029698. Registered in England and Wales, company number 16206282. Registered office: Vivian House, Roman Bridge Close, Mumbles, Swansea, SA3 5BG.

Spotted something wrong?

We'd rather know. Email [email protected] or call 01792 001350 and we'll review and correct it.

For advice on your own insurance arrangements, speak to us directly — that's when we can take your circumstances into account and give you a recommendation.

Ready to protect your business?
Get expert advice and a tailored commercial insurance quote today.

✔ Independent broker
✔ Access to leading UK insurers
✔ Fast turnaround

[Request a quote]

[[email protected]]
[Call 01792 001350]

Exclusive Offer

Free Insurance Review
& Zero Broker Fee

Let us review your current insurance and see if we can improve your cover while reducing the cost.

✓
Free no-obligation insurance review tailored to your business
£
Zero broker fee on all new policies
⚡
Fast response from a real insurance specialist

You're in 🎉

Thanks for requesting your free review. We'll be in touch shortly.

🔒 No spam, ever. Your details are safe with us.

We're an Appointed Representative of Gauntlet Risk Management Ltd, which is authorised and regulated by the FCA. You can check our entry on the FCA Register.

MEET THE Director

Hey, I'm John!

I started Miller & Partner with the aim to bring back personable, approachable broking to UK businesses who were tired of large corporate brokers and feeling like they were just another number.

I have built this brokerage up with no pushy sales techniques or big business tactics, just honest, approachable and professional relationships with my clients.

Over 13 years experience in business insurance

Client first approach

5* rated broker on Google

Office: Vivian House, Roman Bridge Close, Mumbles, Swansea, SA3 5BG

Miller & Partner Ltd is an Appointed Representative of Gauntlet Risk Management Ltd, which is authorised and regulated by the Financial Conduct Authority (FRN 308081). Miller & Partner Ltd is entered on the Financial Services Register under firm reference number 1029698. You may check this on the Financial Services Register by visiting the FCA website at https://www.fca.org.uk/firms/financial-services-register or by contacting the FCA on 0800 111 6768. Miller & Partner Ltd is registered in England & Wales, company number 16206282. Registered office: 20 Vivian House, Roman Bridge Close, Swansea, SA3 5BG.




