


Property Guardian Insurance UK: Owners & Guardian Firms
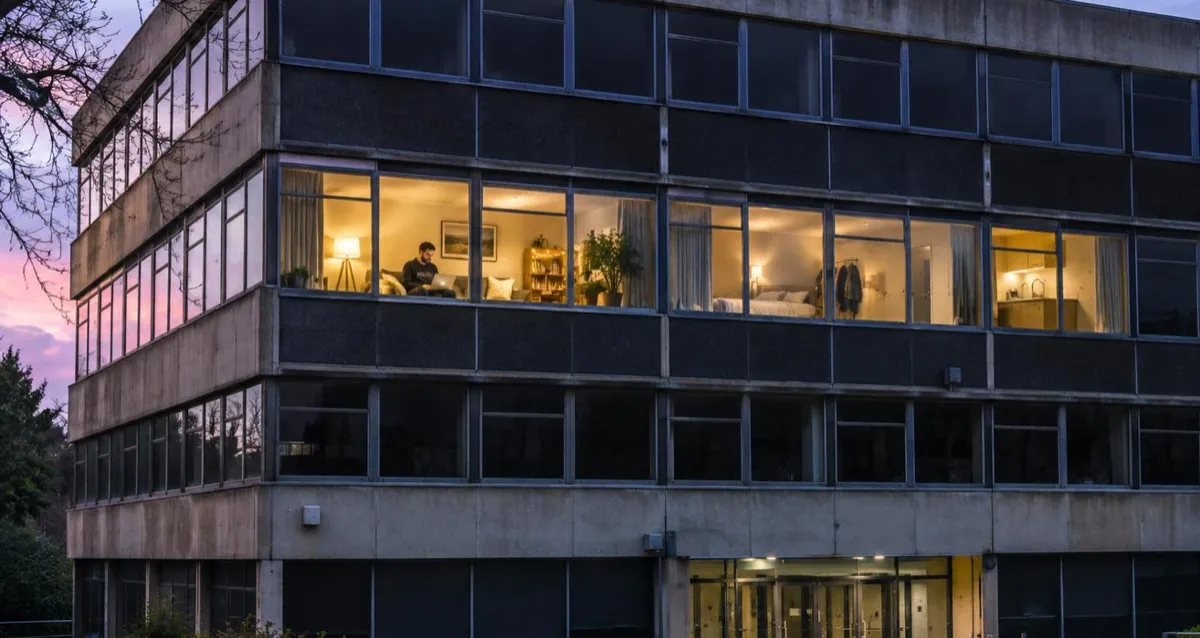
Property guardian insurance covers two parties: the guardian company that places people to live in empty buildings, and the owner of the building they live in. The guardian company needs public liability, employers' liability and professional indemnity that reflects the fact that it is managing residential occupation of buildings never designed for it, such as offices, schools, pubs and care homes. The building owner needs buildings cover and property owners' liability that recognises the building is neither empty nor let in the normal way. Most standard unoccupied property policies don't fit, because the building is occupied, and most landlord policies don't fit either, because the occupiers are licensees rather than tenants. Insurers want to see the fire risk assessment, how many guardians live there, which floors are used, and how the guardian company carries out its checks.
Key facts at a glance
- It is not an empty building. Once guardians move in, a standard unoccupied policy may no longer describe the risk correctly.
- It is not a normal let either. Guardians usually occupy under a licence, and many landlord policies only cover tenancies.
- Two sets of cover are needed. The owner insures the building; the guardian company insures its own operation and liability.
- Fire safety is the deciding factor. Insurers look closely at alarms, escape routes and the fire risk assessment for residential use.
- Some guardian properties are HMOs. Where the HMO rules apply, insurers ask about licensing.
Who needs property guardian insurance?
We arrange cover for both sides of a guardianship arrangement, and for owners weighing guardians against other ways of securing an empty building.
- Guardian companies. Firms that recruit, vet and manage guardians and hold the agreements with building owners.
- Commercial landlords. Owners of empty offices, retail units and pubs waiting for a buyer, a tenant or planning consent.
- Developers. Sites held for redevelopment, where the building has to be kept secure until work starts.
- Councils and public bodies. Former schools, libraries, police stations and care homes awaiting disposal.
- Charities and churches. Surplus buildings that would otherwise sit empty.
- Housing associations. Blocks held empty before regeneration.
What does property guardian insurance cover?
The owner's and the guardian company's policies do different jobs. The table shows where each cover usually sits.
| Cover | Who buys it | What to check |
|---|---|---|
| Buildings | Building owner | The insurer knows the building is guardian occupied |
| Property owners' liability | Building owner | No exclusion for residential occupation of a commercial building |
| Public liability | Guardian company | Covers injury to guardians and visitors arising from its management |
| Employers' liability | Guardian company | A legal requirement once it employs staff |
| Professional indemnity | Guardian company | Errors in vetting, inspections or advice to the owner |
| Contents | Each guardian | Guardians need their own cover for belongings |
If the building will later be stripped out or redeveloped, read our guide to derelict building insurance, because the cover will need to change again when the guardians leave.
Why won't a normal unoccupied policy do?
Unoccupied property policies are written on the basis that nobody lives in the building. Guardians change that, for better and for worse.
The good news is that people living in a building tend to deter squatters, arson and metal theft, which are the claims that make empty buildings so expensive to insure. Several insurers will give better terms for a guardian-occupied building than for one that is boarded up and visited once a week.
The catch is that the building now has people sleeping in it. A former office has kitchens put in, extension leads run between rooms and portable heaters brought in during the winter. That is a residential fire risk in a building designed for nine-to-five use, and insurers will want to see that it has been thought about. If the insurer believes the building is empty and a guardian's heater starts a fire, you may find the claim disputed.
Changing from empty to guardian occupied is a material change. Notify your insurer before the first guardian arrives, not at renewal.
What do insurers ask about guardian-occupied buildings?
Expect questions about the building, the guardians and the company managing them.
- The building's former use, construction and size
- Number of guardians and which floors or areas they occupy
- Fire risk assessment for residential use, with alarms, detection and escape routes
- Kitchen and washing facilities, and how they were installed
- Rules on heaters, cooking and smoking
- How often the guardian company inspects
- How guardians are vetted and what the licence agreement says
- Whether the property is a licensable HMO, and the licence position
- Security of the parts of the building not in use
How do you get the best terms?
- Agree responsibilities in writing. The agreement between owner and guardian company should say who insures what.
- Get a residential fire risk assessment. Done for guardian occupation, not the old commercial use.
- Close off unused areas. Lock and alarm floors nobody lives on.
- Keep inspection records. Dated visits with photos help at claim time.
- Check the HMO position. Deal with licensing before an insurer asks.
- Use a broker who knows vacant property. The markets that like guardian-occupied buildings are specialist ones.
Frequently asked questions
Usually not. Most insurers treat it as occupied, but on its own terms, so it must be described accurately.
Normally the owner. The guardian company insures its own liability and operation.
Guardians usually occupy under a licence rather than a tenancy, although the courts look at the reality of the arrangement. Insurers care about how the building is used either way.
Yes, for their belongings. The building owner's policy will not cover guardians' personal possessions.
Often, compared with a building that is empty, because the risk of squatting, arson and theft is lower.
Some do, depending on the number of occupiers and the local licensing scheme. Insurers may ask.
A fire risk assessment for residential occupation, working detection and alarms, clear escape routes and rules on heaters and cooking.
Yes. It covers claims that the company failed to vet, inspect or manage properly.
The building becomes unoccupied, and you should tell your insurer straight away so the cover can be adjusted.
Related guides from Miller & Partner

Miller & Partner Limited (FRN 1029698) is an Appointed Representative of Gauntlet Risk Management Ltd (FRN 308081), which is authorised and regulated by the Financial Conduct Authority. Miller & Partner Limited is registered in England and Wales (company number 16206282) and trades from Vivian House, Roman Bridge Close, Mumbles, Swansea SA3 5BG. This article is general information, not a personal recommendation or an offer of cover. Cover is subject to insurer acceptance and the full terms, conditions and exclusions of the policy issued.







Instagram
LinkedIn