

FS Register FRN 1029698

Five Star Rated on Google

13+ years specialist broking experience

General information, not advice. Written for general guidance and drawing on external sources as well as our own experience. It isn't a personal recommendation and doesn't take account of your circumstances — full disclaimer and sources.

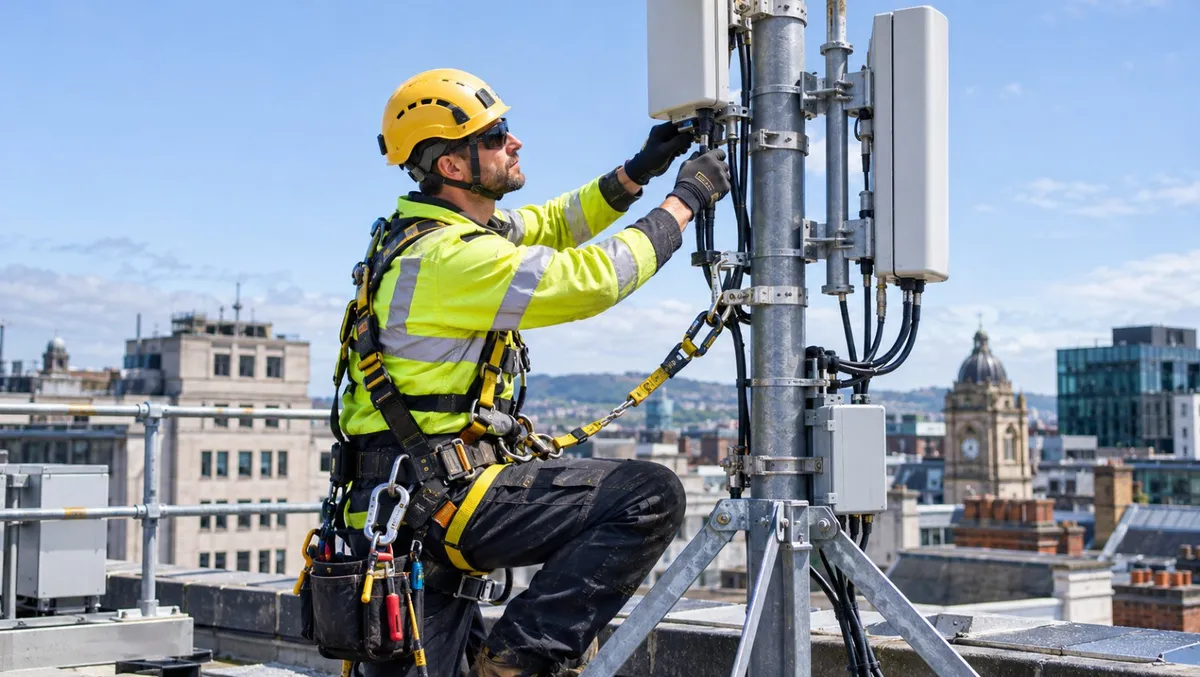
Telecoms rigger in a climbing harness installing antennas on a city rooftop mast, illustrating mast and rooftop installer insurance

Mast & Rooftop Telecoms Installer Insurance UK

November 04, 2026

Published: 4 November 2026 | Reading time: 7 minutes | Category: Contractors | Author: John Miller, Miller & Partner

Last reviewed by John Miller, Director & Principal Broker — 4 November 2026
FS Register FRN 1029698 13+ years specialist commercial broking Lloyd's & specialist MGA market access Independent UK broker

Mast and rooftop telecoms installers need public liability with no restrictive height limit, employers' liability for climbers and rope access technicians, and cover for contract works, hired-in plant and lifting, placed with a market that accepts tower work. Climbing lattice towers and monopoles, working on rope and installing antennas on other people's roofs creates a risk profile many standard contractor policies will not accept. The claims that hurt most are often not falls but water ingress: a pierced membrane or badly sealed penetration can damage the floors below for months before anyone notices. Insurers will ask your maximum working height, whether technicians hold IRATA or equivalent qualifications, how you control dropped objects, who plans crane lifts, whether you hire in cranes or MEWPs, how you manage RF exposure on live sites and how much work you pass to labour-only or bona fide subcontractors. Accurate answers at proposal stage keep claims payable, and main contractors will check your certificates before you go up.

Need insurance for mast or rooftop installs?

Cover for tower, rope access and rooftop crews. Get a quote online or speak to a specialist broker directly.

Key facts at a glance

  1. Height limits are common. Many standard policies cap working height well below tower work.
  2. Roof leaks drive claims. Water ingress after a rooftop install can damage a whole building.
  3. Rope access is a separate question. Insurers ask about IRATA or equivalent training and rescue plans.
  4. Lifting changes who is liable. Crane hire and contract lifts carry different responsibilities.
  5. Contracts set your limits. Main contractors and network operators commonly set minimum liability limits in their subcontract terms.

What does mast and rooftop installer insurance cover?

It is usually a contractors' combined policy written for work at height on towers and roofs. Public liability and employers' liability form the core, with sections for contract works on the equipment you install, own and hired-in plant, and tools. The business description must name tower climbing and rope access.

For the wider sector, see our fibre and telecoms contractor insurance page.

CoverWhy it matters on masts and roofs
Public liabilityRoof membrane damage, water ingress, dropped objects onto people and property
Employers' liabilityFalls and injuries to climbers and rope access technicians
Contract worksAntennas, cabinets, steelwork and cabling damaged or stolen before handover
Hired-in plantCranes, MEWPs and hoists hired on terms that make you responsible
Tools and own plantClimbing, rigging and test equipment

Why do tower climbing and rope access change the risk?

Because severity rises with height, and both employee and public claims can be serious. Many policies carry a height limit that tower work exceeds, and some exclude rope access. Insurers want your maximum height, access methods, IRATA or equivalent qualifications and how you would rescue a casualty from the structure.

Give your real maximum height, not a typical one. The Work at Height Regulations 2005 require planning, supervision and competent people, and insurers expect training records, climb plans and rescue kit checks to show it. If you also climb wooden poles, our telegraph pole and overhead line worker guide covers that work.

Who pays if a rooftop install causes a leak?

Usually the installer's public liability, provided the damage is accidental and the policy has no relevant exclusion. Roof membranes are easily punctured by ballast frames, cable trays and foot traffic, and water ingress can spread through ceilings, stock and tenants' fit-outs before it is found.

Rectifying your own faulty work is generally not covered, but resulting damage to the building usually is. Underwriters look for:

  • Pre-start roof condition surveys with photographs
  • Protection boards under frames and walkways
  • Approved sealing methods for penetrations
  • Sign-off from the building owner at handover

How do lifting, cranes and dropped objects affect cover?

Lifting antennas and steelwork is a frequent source of property damage and injury. Insurers ask who plans the lift, whether you hire a crane with an operator or buy a contract lift, and how you control dropped objects through exclusion zones, tool lanyards and secured fixings at height.

Under many crane hire terms, the hirer takes responsibility for the crane and the lift, so you need hired-in plant insurance and liability that responds to lifting. A contract lift usually places more responsibility on the lifting company, but check the terms and keep their certificates.

Does RF exposure affect insurance?

It can. Working near live antennas exposes technicians to radio frequency fields, and insurers may ask how RF exposure is managed on shared sites. Evidence of RF awareness training, site-specific information from the operator and procedures for powering down or keeping clear supports your proposal.
Check how RF is treated Some wordings are silent on RF exposure and others restrict it. Disclose live-site work, check with your broker how the policy responds, and follow the site operator's access and RF procedures.

Does employers' liability cover climbers and rope access teams?

Yes, if they fall within the policy's definition of employee, which often includes labour-only subcontractors under your direction. Bona fide subcontractors with their own insurance are usually treated differently. Check and keep evidence of their cover, because an uninsured technician injured on your job may become your claim.

Splicing teams on the same sites face the same issue, covered in our fibre splicing and jointing subcontractor insurance guide.

Frequently asked questions

Often not. Many standard policies carry height limits or exclude tower and rope access work. Check the business description and any height condition before relying on one.

Only if you have contract works cover or your client's project policy includes you. Check your contract to see who bears the risk of loss or damage until handover.

Most will ask whether rope access technicians hold IRATA or an equivalent qualification and whether a rescue plan is in place. Clients usually ask the same.

Accidental damage to the building and contents is usually covered under public liability, subject to the excess. Repairing your own faulty work is generally not.

Main contractors and network operators commonly set minimum liability limits in their subcontract terms. Arrange at least that, and consider more for high-value buildings.

Usually, through specialist and Lloyd's markets. Expect questions on what happened and what has changed. Our guide to cover after a claim explains how to approach renewal.

Related guides from Miller & Partner

Climbing towers or working on roofs? Tell us how your crews work and we will approach the markets that understand it.

John Miller, Director and Principal Broker at Miller & Partner, specialist broker for mast and rooftop telecoms installers
Written and reviewed by John Miller Director & Principal Broker, Miller & Partner Over 13 years of specialist commercial insurance experience, formerly with Brown & Brown and AXA. Places hard-to-place commercial risks through Lloyd's syndicates and specialist MGAs, including telecoms, rope access and work-at-height contractors.
Our regulatory status Miller & Partner Limited (FRN 1029698) is an Appointed Representative of Gauntlet Risk Management Ltd (FRN 308081), which is authorised and regulated by the Financial Conduct Authority. Miller & Partner Limited is registered in England and Wales (company number 16206282) and trades from Vivian House, Roman Bridge Close, Mumbles, Swansea SA3 5BG. This article is general information, not a personal recommendation or an offer of cover. Cover is subject to insurer acceptance and the full terms, conditions and exclusions of the policy issued. Height, rope access and RF terms vary by insurer, so check your own wording.
Back to Blog
About this article General information, not advice. Published for general guidance and drawing on external sources as well as our own experience. It is not a personal recommendation, a quotation, or an offer of cover, and it doesn't take account of your circumstances. Read more + Close −

Where the information comes from

Our articles are compiled from a range of sources: regulators and public bodies such as the FCA, the Civil Aviation Authority, the Health and Safety Executive and Companies House; government publications and legislation; industry and trade bodies; insurer and market documentation; and published research and news reporting. Not everything stated originates from Miller & Partner. Where information comes from a third party we believe it to be accurate at the date of publication, but we haven't independently verified every external source and we don't warrant its accuracy or completeness. Where a point matters to a decision you're making, go to the original source and check it.

Figures, examples and case studies

Premium ranges, cost figures, limits and worked examples are illustrative only. They are not quotations, not offers of cover, and no cover is provided or implied on the basis of them. What you're actually charged depends on underwriting, and what you're actually covered for depends on the policy wording issued to you. Where an article includes a claim example, scenario or case study, it is illustrative unless we say otherwise — such examples are typically composites written to show how a policy section responds, and they don't describe an identifiable client, claim or settlement.

Interactive tools

Any calculators, cover checkers, risk assessors or similar tools on our site produce general guidance from the small number of answers you give them. They can't see your business, and their output is not a personal recommendation, an assessment of your actual risk, or a quotation.

Rules and market conditions change

Law, regulation, tax treatment, insurer appetite and policy wordings all change, sometimes at short notice. Content is accurate to the best of our knowledge on the date shown on the article and we don't undertake to update it as things move. An article you're reading some time after publication may be out of date.

Third parties and external links

References to insurers, underwriters, trade bodies, software, training providers or other organisations are for information only. They don't imply endorsement, recommendation, partnership or affiliation in either direction unless stated. We're not responsible for the content of external websites we link to.

Not legal, tax or accounting advice

Nothing here is legal, tax, accounting or regulatory advice. Where an article discusses statutory duties, contract terms or compliance obligations, take advice from an appropriately qualified professional on your own position before acting.

How we write these

We use AI tools in researching and drafting our published content. Every article is reviewed and signed off by a named, accountable person at Miller & Partner before it is published, and responsibility for what appears here rests with us.

Our regulatory status

Miller & Partner Ltd is an Appointed Representative of Gauntlet Risk Management Ltd, which is authorised and regulated by the Financial Conduct Authority (FRN 308081). Miller & Partner Ltd is entered on the FCA Register under reference 1029698. Registered in England and Wales, company number 16206282. Registered office: Vivian House, Roman Bridge Close, Mumbles, Swansea, SA3 5BG.

Spotted something wrong?

We'd rather know. Email [email protected] or call 01792 001350 and we'll review and correct it.

For advice on your own insurance arrangements, speak to us directly — that's when we can take your circumstances into account and give you a recommendation.

Ready to protect your business?
Get expert advice and a tailored commercial insurance quote today.

✔ Independent broker
✔ Access to leading UK insurers
✔ Fast turnaround

[Request a quote]

[[email protected]]
[Call 01792 001350]

Exclusive Offer

Free Insurance Review
& Zero Broker Fee

Let us review your current insurance and see if we can improve your cover while reducing the cost.

✓
Free no-obligation insurance review tailored to your business
£
Zero broker fee on all new policies
⚡
Fast response from a real insurance specialist

You're in 🎉

Thanks for requesting your free review. We'll be in touch shortly.

🔒 No spam, ever. Your details are safe with us.

We're an Appointed Representative of Gauntlet Risk Management Ltd, which is authorised and regulated by the FCA. You can check our entry on the FCA Register.

MEET THE Director

Hey, I'm John!

I started Miller & Partner with the aim to bring back personable, approachable broking to UK businesses who were tired of large corporate brokers and feeling like they were just another number.

I have built this brokerage up with no pushy sales techniques or big business tactics, just honest, approachable and professional relationships with my clients.

Over 13 years experience in business insurance

Client first approach

5* rated broker on Google

Office: Vivian House, Roman Bridge Close, Mumbles, Swansea, SA3 5BG

Miller & Partner Ltd is an Appointed Representative of Gauntlet Risk Management Ltd, which is authorised and regulated by the Financial Conduct Authority (FRN 308081). Miller & Partner Ltd is entered on the Financial Services Register under firm reference number 1029698. You may check this on the Financial Services Register by visiting the FCA website at https://www.fca.org.uk/firms/financial-services-register or by contacting the FCA on 0800 111 6768. Miller & Partner Ltd is registered in England & Wales, company number 16206282. Registered office: 20 Vivian House, Roman Bridge Close, Swansea, SA3 5BG.





